


Biohaven (BHVN), What Is Behind The Fresh Attention?
Biohaven (BHVN) has moved back into focus after signing a regional licensing deal with Ono Pharmaceutical for its IgG degrader platform, along with a new oncology collaboration expansion with Regeneron.
Despite the Ono and Regeneron announcements, Biohaven’s recent share price performance has been weak, with the 7 day share price return down 11.01% and the 30 day share price return down 24.28%. The year to date share price return of 9.59% contrasts with a 1 year total shareholder return that has declined 22.56%, suggesting short term momentum has faded even as investors weigh a more mixed longer term experience.
Scan beyond Biohaven and see how other biopharma players with under-pressure charts but active deal pipelines line up in our hand picked 20 high quality undiscovered gems.
Biohaven now trades at a clear discount to both its analyst target and intrinsic estimate after a sharp pullback. So where does a fair value anchor really sit before the valuation work begins?
Most Popular Narrative: 69% Undervalued
Biohaven’s most followed valuation narrative points to a fair value of $38.35 against a last close of $11.88, so the recent pullback leaves a wide gap that bullish investors focus on when they look at the pipeline and deal activity.
The planned pivotal studies for BHV-1400 in IgA nephropathy and advanced trials for oncology candidates BHV-1510 and BHV-1530, including a Regeneron combination study, open up additional indications that could layer on new revenue lines and allow fixed R&D and SG&A costs to be spread over a wider product mix, which can support margin expansion over time.
See why 0 investors see Biohaven as 69% undervalued.
Result: Fair Value of $38.35 (UNDERVALUED)
Still, the opakalim clinical hold and the heavy cash burn behind Biohaven’s late stage trials could both erode confidence in that 69% undervalued narrative.
Find out about the key risks to this Biohaven narrative.
Another View: Biohaven Through The P/B Lens
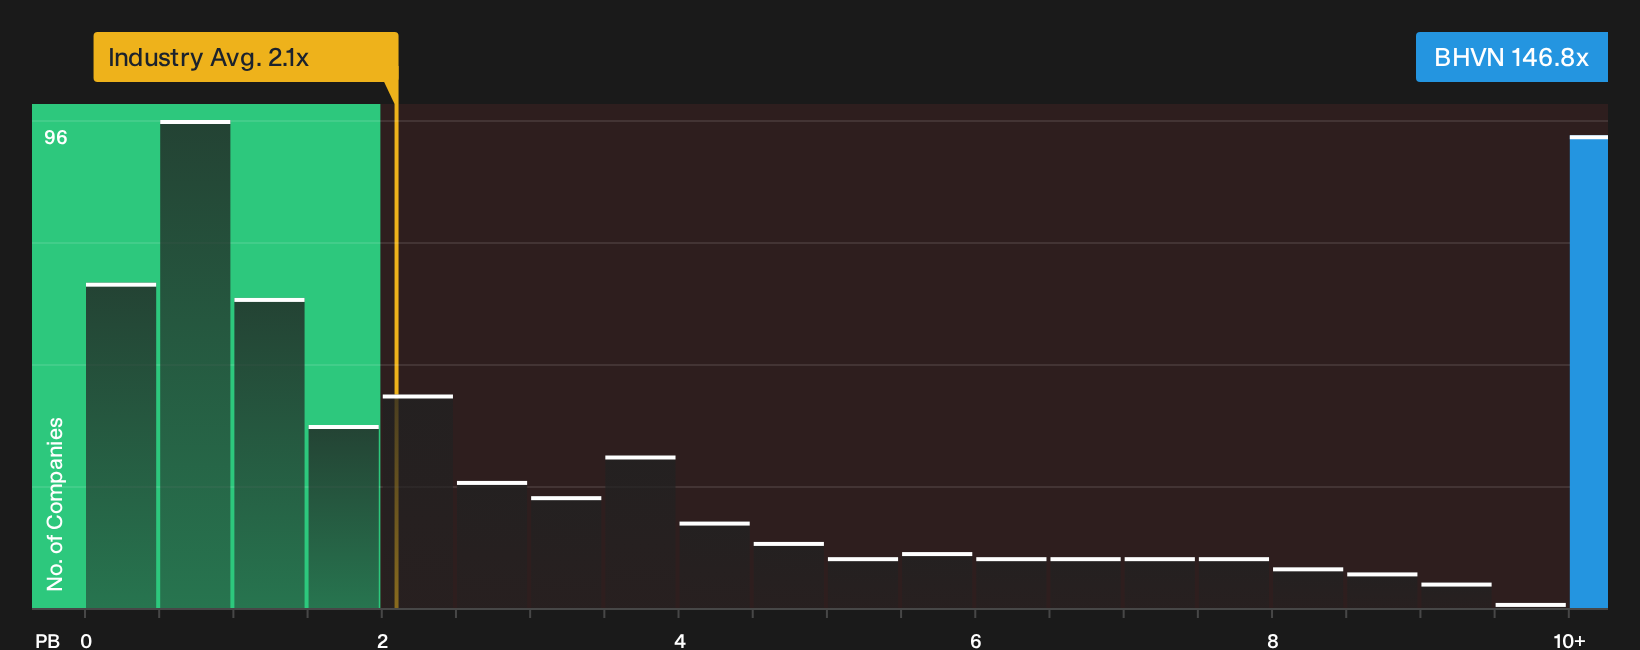
The SWS DCF model paints Biohaven as deeply undervalued, yet the market is not pricing it that way when using a simple balance sheet yardstick. On a P/B basis, the stock trades at 146.8x, while the US Biotechs industry sits at 2x and peer companies average 4.7x.
That gap is very wide and leans toward valuation risk rather than a clear bargain, because even a small move toward sector or peer levels could mean a sharp reset in the share price. The fair ratio is unavailable, so investors are left judging which signal to trust more at this point.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Biohaven’s valuation and risk reward profile can feel confusing, so move quickly, pull up the data, and test the story against your own assumptions using the 2 key rewards and 5 important warning signs.
Looking For More Investment Ideas Beyond Biohaven?
Biohaven gives you a lot to think about, but your next strong idea might come from a very different corner of the market. Do not leave those on the table.
- Target resilient opportunities with lower perceived downside by scanning a 31 resilient stocks with low risk scores that filters for businesses aiming to balance return potential with stability.
- Zero in on quality first and valuation second by running through a list of solid balance sheet and fundamentals (25 results) that highlights companies with healthier fundamentals backing their share prices.
- Hunt for mispriced potential by reviewing a 29 high quality undervalued stocks focused on stocks where underlying metrics and current pricing appear meaningfully out of sync.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com