


Guangdong Investment (SEHK:270) Has Rallied, But Does The Valuation Still Stack Up
Guangdong Investment (SEHK:270) has come onto investors’ radar after its recent share move, with the stock last closing at HK$8.74. The water focused conglomerate now carries a market value of about HK$57.1b.
Recent trading has cooled slightly, with the 7 day share price return down 1.63% and the 30 day move also softer. Yet Guangdong Investment still shows building momentum, supported by a 15.30% 90 day share price return and a 35.11% one year total shareholder return.
Capitalize on Guangdong Investment’s recent momentum by comparing it with a hand picked 182 high quality undervalued stocks that features companies with stronger balance sheets and current market skepticism.Guangdong Investment has already rewarded holders who sat through the recovery, so the real tension now is whether that recent strength still leaves enough upside to justify fresh risk as the valuation math comes into focus.
Preferred P/E of 11.6x: Is it justified?
Valuation now hangs on whether Guangdong Investment’s current P/E of 11.6x is a fair price for its recent recovery and earnings profile. The last close at HK$8.74 already bakes in a strong one year total shareholder return, so the question is whether the ratio still leaves enough compensation for fresh risk.
The P/E multiple compares what you pay today for each dollar of earnings. For a utility focused business like Guangdong Investment that runs water resources, roads, bridges, hotels and retail, investors often look at this yardstick to judge how much the market is willing to pay for its profit stream.
On an absolute basis, the stock screens as expensive against two different anchors. Management’s current P/E of 11.6x sits above the estimated fair P/E of 9.4x, a level that the market could move towards if sentiment cools. It also trades richer than the peer average P/E of 7.4x. That combination points to investors already paying up for the company’s 13.4% recent earnings growth and improved 25% net margin, even though return on equity is still only 9% and forecast profit and revenue growth are slower than the wider Hong Kong market.
Compared with the broader Asian water utilities group, Guangdong Investment looks slightly cheaper on this same metric, since its 11.6x P/E sits just under the regional sector average of 12x. The gap to both the peer group at 7.4x and the 9.4x fair P/E estimate is much wider though, which suggests plenty of optimism already in the price for a conglomerate that still relies entirely on external borrowing for funding and has an unstable dividend history.
Explore the SWS fair ratio for Guangdong Investment.
Result: Price-to-earnings of 11.6x (OVERVALUED)
Still, Guangdong Investment faces pressure if earnings soften or funding costs rise. This could prompt investors to reassess that 11.6x P/E premium.
Find out about the key risks to this Guangdong Investment narrative.
Another View on Guangdong Investment’s value
The P/E premium paints Guangdong Investment as expensive, yet the SWS DCF model points in the opposite direction. At HK$8.74, the share price sits about 62.8% below an estimated future cash flow value of HK$23.47. That gap hints at a very different risk reward trade off. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
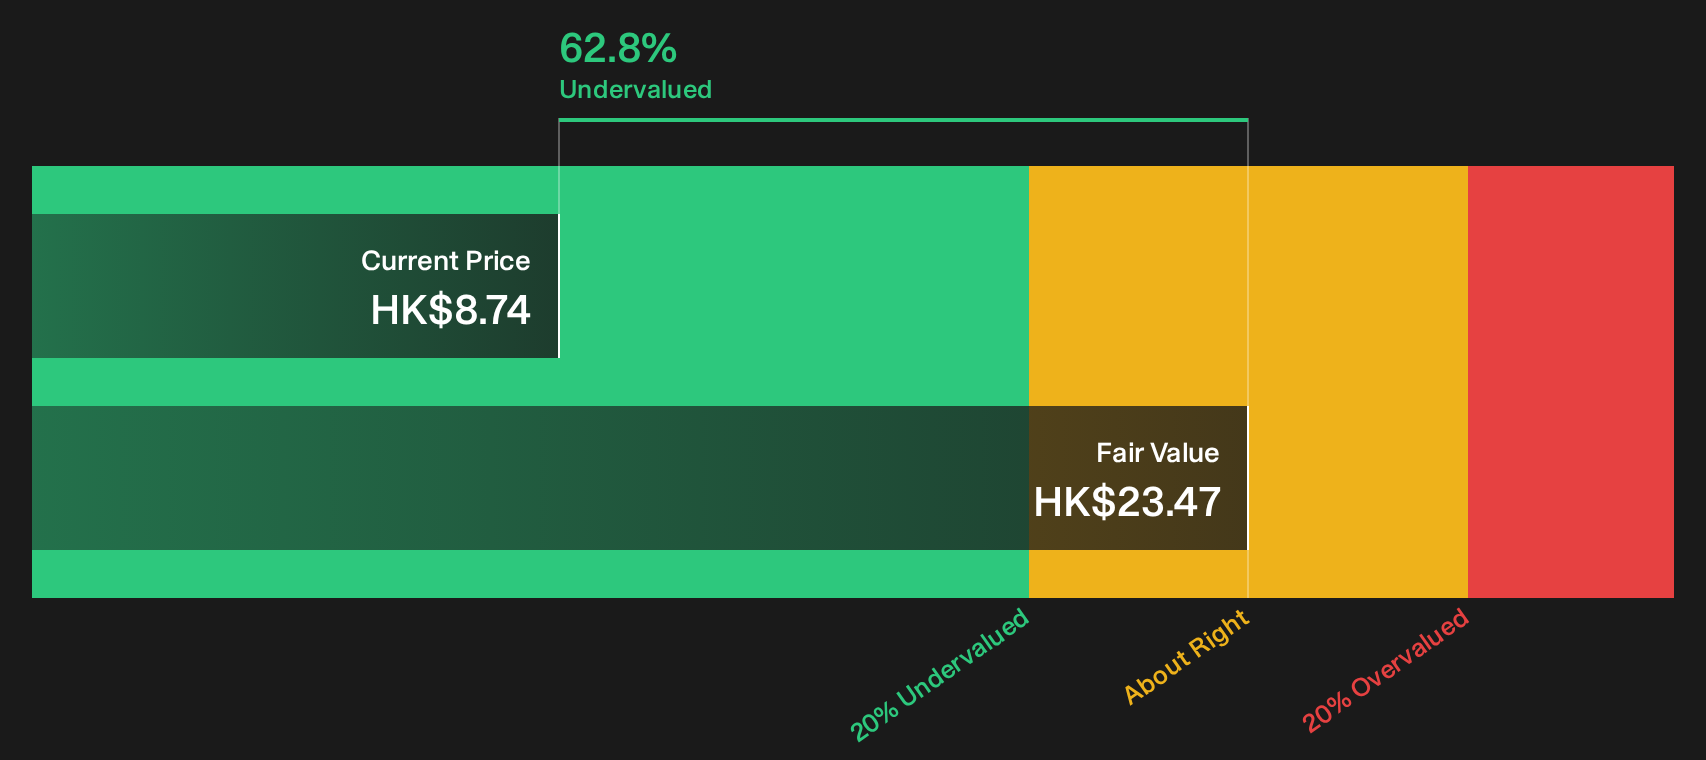
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Guangdong Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Guangdong Investment’s value and risk profile make this a judgment call, so move quickly, review the data, and ground your own decision in the 2 key rewards and 1 important warning sign.
Looking for more Guangdong Investment sized ideas?
If Guangdong Investment is on the watchlist, it makes sense to line it up against other opportunities that could sharpen your overall portfolio mix.
- Target income resilience and compare Guangdong Investment’s yield profile against a hand picked pool of income ideas using the 224 dividend fortresses.
- Hunt for quality at a discount by lining this stock up beside a curated 619 high quality undiscovered gems that highlights underfollowed businesses with robust fundamentals.
- Dial down portfolio risk and stress test Guangdong Investment against a carefully filtered 225 resilient stocks with low risk scores that focuses on resilient balance sheets and steadier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com