


Following Tilray Earnings, Here's What Comes Next for TLRY Stock
Tilray (TLRY) stock is in the red this morning even though the cannabis firm posted record revenue of $257.1 million for its first financial quarter — up 23% on a year-over-year basis. But the options market sentiment suggests the selloff is temporary, and TLRY could actually move meaningfully to the upside in the sessions ahead.
While gross margin expanded to 30% in Q1, Tilray shares are down about 60% versus the start of this year.
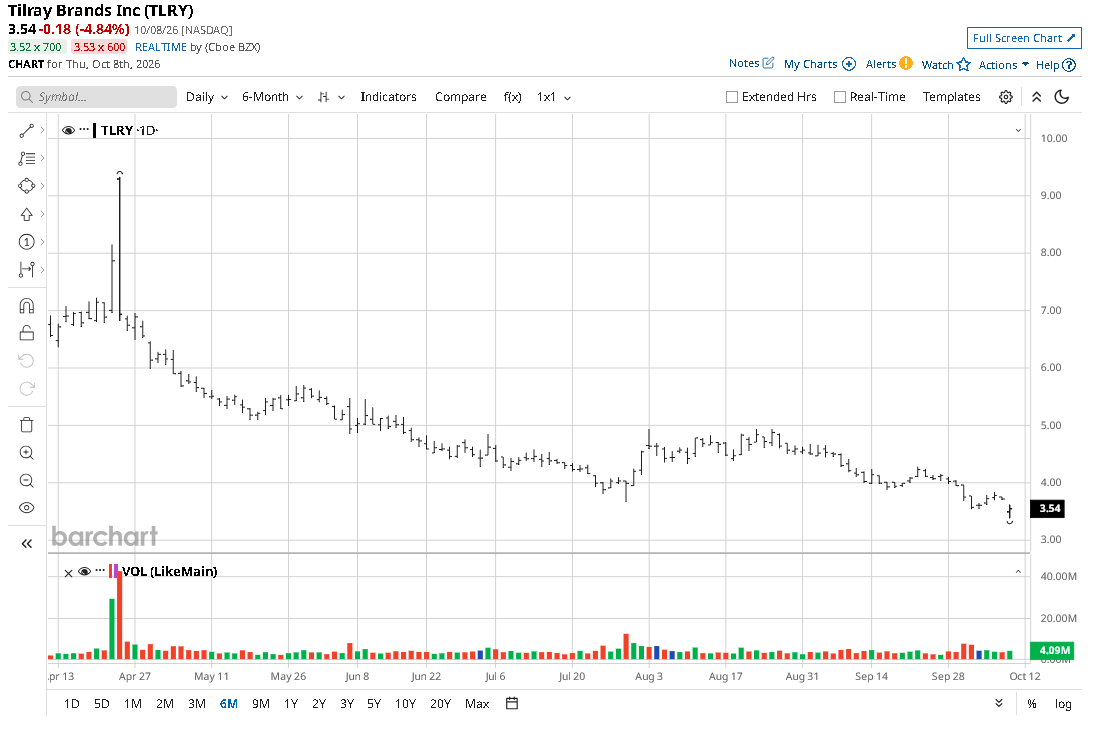
Where Options Data Suggests Tilray Stock Is Headed
Options traders seem to believe that the near-term headwinds are already priced into TLRY stock, which is now trading at a price-to-sales (P/S) multiple of about 0.56x.
The put-to-call ratio on contracts expiring Oct. 16 sits at 0.25x at the time of writing, with a reading below 1.00x typically characterized as favoring bears.
And the upper price on those contracts, according to Barchart, is set at $3.88 currently, indicating the cannabis stock could rally more than 8.3% from here through the end of next week.
That said, Tilray has a history of closing each of the final three months of the year in the red — a seasonal pattern that makes it rather unattractive for the near term.
Why Are TLRY Shares Slipping Today?
Despite top-line gains, Tilray stock is slipping on Thursday because the cannabis firm swung to a notable net loss of $40 million in Q1 — down from net income of $1.5 million a year ago.
Adjusted EBITDA also slipped slightly to over $9 million due to rising operational costs, including $1.7 million in global fuel surcharges.
Further dampening sentiment, core cannabis net revenue fell 13% year-over-year to $56.1 million, illustrating persistent pricing pressures in Canada.
Combined with negative free cash flow of $27.4 million and ongoing dilution concerns, investors prioritized these bottom-line headwinds over headline sales growth.
How Wall Street Recommends Playing TLRY Shares
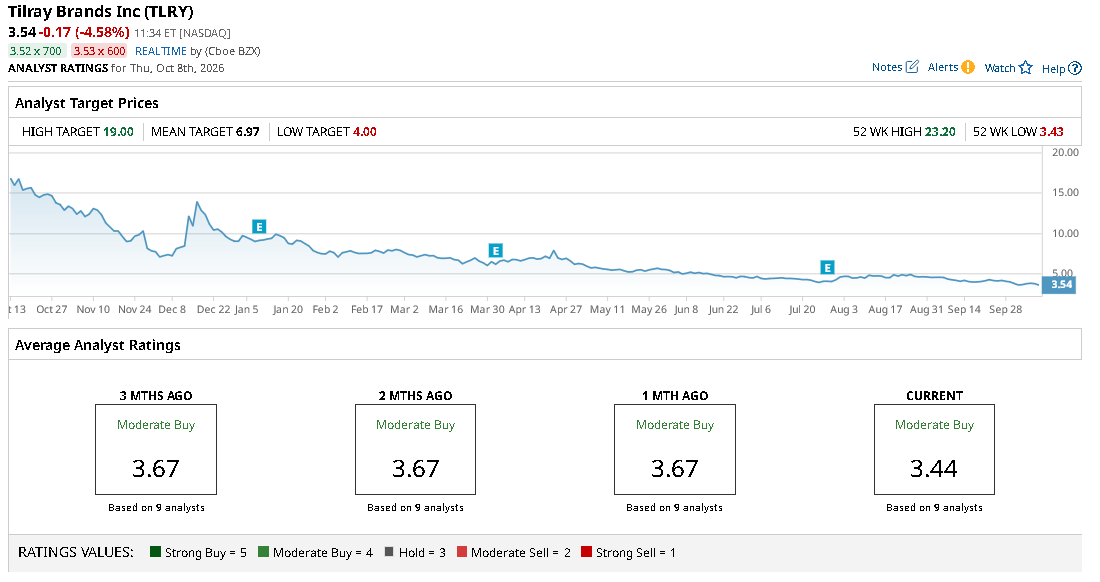
Investors should note, however, that Wall Street firms haven’t thrown in the towel on TLRY shares.
The consensus rating on Tilray sits at “Moderate Buy,” with the mean price objective of roughly $7 indicating potential upside of a whopping 90% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.