


Earnings Expectations Build for Cadence Stock Ahead of Q3 Results
- Cadence Design Systems recently presented at the 2026 North American Marketing Leadership Summit in Phoenix, where Digital Marketing Director Phil Massano outlined the company’s approach to positioning its electronic design automation and IP portfolio.
- The focus on marketing execution around complex AI-driven design tools indicates that Cadence Design Systems is investing in how it communicates product value and drives demand alongside its technical roadmap.
- We will now look at how this emphasis on marketing execution might shape Cadence Design Systems' broader investment narrative ahead of earnings.
Cadence Design Systems Investment Narrative Recap
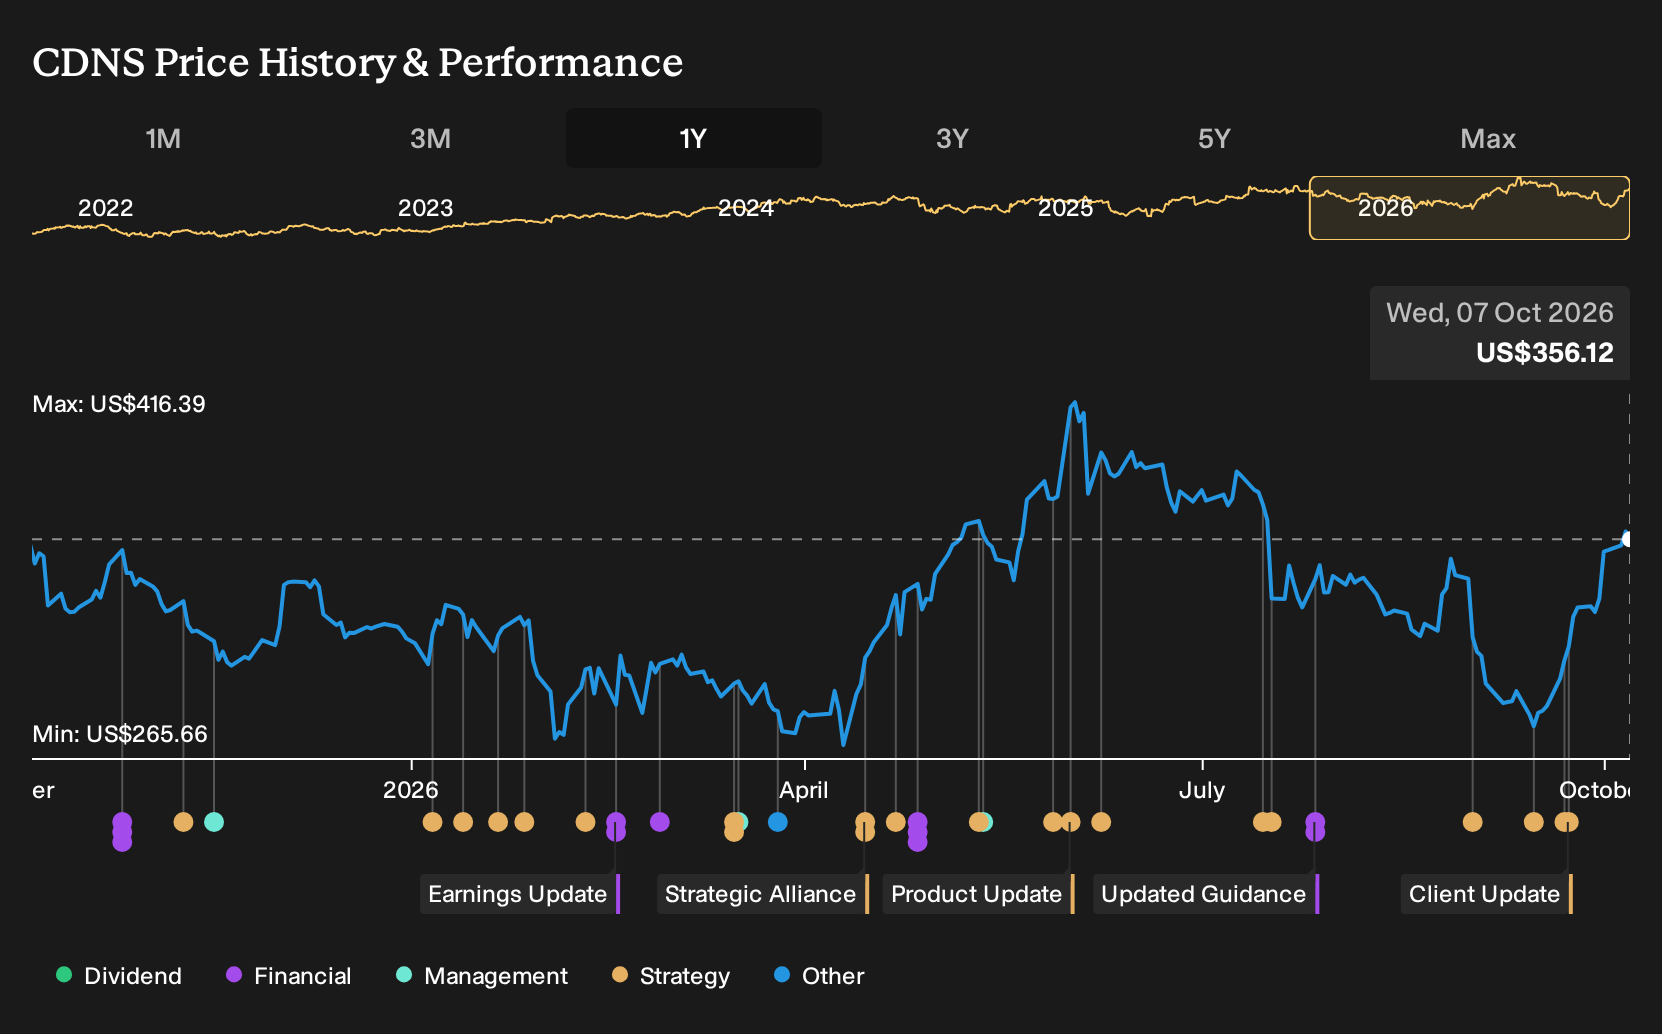
For a shareholder in Cadence Design Systems, the core belief is that AI driven design tools, IP and system analysis can keep pulling more spend from chipmakers and systems customers. The marketing summit appearance fits that story. It signals that management is putting real attention on how these AI super agents and complex workflows are explained to buyers ahead of the 26 October earnings release.
The near term swing factor remains execution on AI agent adoption, IP demand and integration of Hexagon Design & Engineering, against a backdrop of premium valuation and insider selling. Any stumble on growth or margins could matter more than this marketing update, which by itself does not look like a material shift to the operating outlook.
The most relevant recent datapoint for this marketing push is the upcoming Q3 2026 earnings release, with analysts expecting earnings and revenue growth and pointing to high recurring revenue and a record US$8.1b backlog. That backlog gives Cadence Design Systems solid contracted visibility into near term demand across EDA, IP and hardware.
Into that event, the key question is whether the rollout of agentic AI super agents and higher value IP can support those expectations while absorbing Hexagon related costs and any China or export control pressure. Stronger marketing execution can help explain the AI and IP offering, but the real test sits in usage trends, pricing traction and integration progress disclosed at earnings.
Cadence Design Systems' current analyst narrative points to US$8.4b in revenue and US$2.0b in earnings by 2029, based on a projected 12.9% yearly revenue growth rate and an earnings increase of about US$0.6b from US$1.4b today.
Uncover why Cadence Design Systems' fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on valuation risk and more on Cadence Design Systems potentially turning AI agents and IP into a much bigger profit engine. Before this marketing summit, the bullish camp was modeling revenue of about US$9.3b and earnings of US$2.7b by 2029. That is far above consensus and could shift again once this fresh marketing push is fully reflected in updated views, so treat it as one of several perspectives to compare as you build your own take.
Explore 5 other Cadence Design Systems fair value estimates, including one that suggests potential upside of 32% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Cadence Design Systems research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Cadence Design Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cadence Design Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cadence Design Systems?
Once the Cadence Design Systems story is on your radar, it can help to line it up against other opportunities that share similar qualities or offer a different risk and return profile. The Simply Wall St Screener can help you quickly surface stocks that match the kind of traits you care about most.
- If you want income to play a bigger role in your portfolio, consider dividend payers screened through 8 dividend fortresses that combine higher yields with an emphasis on resilience.
- When capital preservation sits near the top of your checklist, look at companies surfaced in the 31 resilient stocks with low risk scores and see which businesses pair steadier balance sheets with lower risk scores.
- For investors hunting for mispriced quality, scan the 29 high quality undervalued stocks and compare those candidates against Cadence Design Systems on fundamentals and valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com