


Hydro One (TSX:H) Stock May Still Have Value Despite Its 94% Run
Hydro One has delivered a strong 93.6% share price gain over the past 5 years, which naturally raises a question for anyone looking at the stock today. Is the current price of $50.83 on the Toronto Stock Exchange adequately supported by the utility's earnings power, or has the valuation run ahead of what the business is generating?
- The 93.6% return over 5 years has materially changed what investors are paying for each dollar of Hydro One's profits. The key issue now is whether earnings have kept pace with that climb.
- As a regulated electricity transmission and distribution business, Hydro One's earnings profile is closely tied to allowed returns, capital spending plans, and how efficiently it can convert that investment into stable profit streams that justify the current P/E multiple.
- The analysts covering Hydro One have run their own numbers. See what analysts think Hydro One's shares could be worth.
The issue now is whether Hydro One's present share price can be explained by its earnings when judged against the Fair Ratio benchmark.
To pressure test whether Hydro One's current P/E still feels reasonable, you can run the same earnings lens across a broader group of utilities and infrastructure stocks using 43 power grid technology and infrastructure stocks
Does Hydro One Look Undervalued on Earnings?
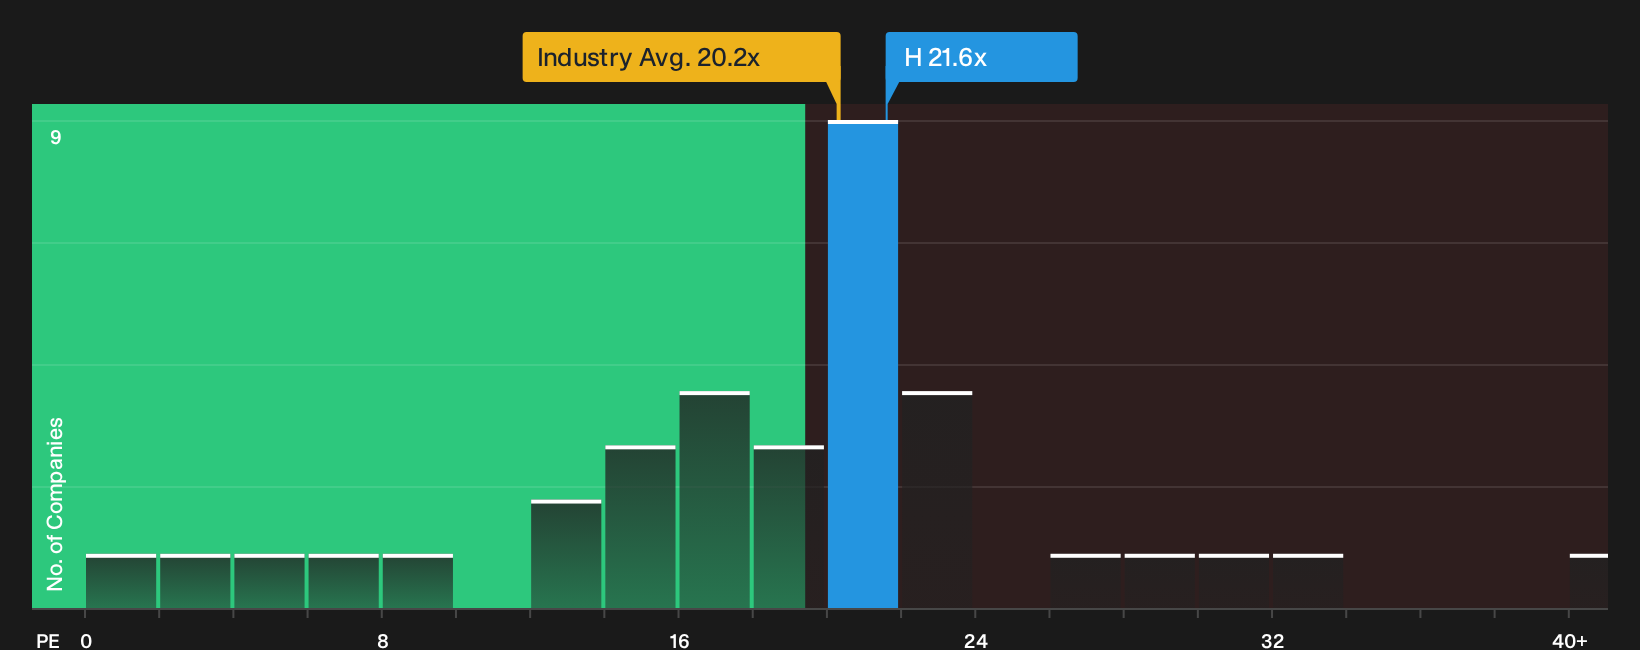
The P/E lens fits Hydro One because earnings remain the main anchor for how investors judge a regulated utility. On this yardstick, the stock trades at about 21.6x, which is a premium to the wider Electric Utilities industry on roughly 14.6x. That tells you the market is willing to pay more for each dollar of Hydro One's profit than for the sector overall.
The comparison shifts when you stack Hydro One against closer peers. The current 21.6x P/E sits slightly above the peer average of about 20.8x, yet below the tailored Fair Ratio implied by its own earnings quality and risk profile. That gap suggests the shares screen as undervalued on this framework, even after the strong run in the price. For anyone weighing an entry or add, the key question is whether Hydro One's regulated cash flows and capital plan justify the market paying closer to that higher reference multiple over time. Explore the numbers behind Hydro One's P/E valuation.
The Hydro One Narrative: What Would Justify Today's Price?
Narratives for Hydro One pick up where the valuation question leaves off and explain what kind of future would need to unfold in terms of growth, profitability and earnings resilience for the stock to be worth meaningfully more or less than its current level. All of this is housed on Simply Wall St's Community page. Instead of a single number from a ratio or model, they lay out the specific future that figure rests on so you can watch whether those conditions actually show up over time.
One of the top community narratives on Hydro One: 11% undervalued
"Government policy and grid modernization initiatives position Hydro One for sustained, regulated earnings growth through expanded capital investment and increased rate base..."
Discover why this Narrative puts Hydro One at 11% undervalued.
One more Hydro One check that belongs beside the earnings lens
Before you move on, it is worth asking who is actually steering Hydro One and how their pay lines up with the results you have just compared on price and earnings. See who runs Hydro One and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com