


Can Penumbra (PEN) Justify Its Valuation As STORM PE Data Strengthens Its Recovery Story?
Penumbra trial data ties wearables to real-world recovery
Penumbra (PEN) drew fresh attention after new STORM-PE trial data linked consumer wearable step counts with standard 6 minute walk tests in pulmonary embolism patients treated with its computer assisted vacuum thrombectomy system.
Penumbra’s share price has eased slightly over the past month, even as the stock holds a modest year to date share price gain of 2.24% at about US$316.35. That softer near term momentum contrasts with a 22.17% total shareholder return over one year and 46.76% total shareholder return over three years, which reflects how investors have reacted to its broader pulmonary embolism data and other recent updates.
Scan other pulmonary and thrombectomy players moving on real world outcomes data with the hand picked 34 healthcare AI stocks that blend medtech hardware and AI driven monitoring.
After a strong three year run and only a modest pullback in recent weeks, Penumbra now sits at a level where the key consideration is whether the current tag still offers enough potential reward relative to the risk involved.
Most Popular Narrative: 13% Undervalued
Penumbra’s most followed narrative pegs fair value at about $361.83, which sits above the recent $316.35 close and frames the current price as implying a discount to that assessment.
The embolization franchise, led by Ruby XL and Swift coils with strong middle meningeal artery embolization uptake and backed by a dedicated embolization sales team of more than 50 people, is emerging as a second pillar alongside thrombectomy. It can increasingly contribute to revenue diversification and operating margin leverage.
See why 5 investors see Penumbra as 13% undervalued.
The narrative is built using a 7.52% discount rate and combines trial data, expected earnings trends and the pending Boston Scientific acquisition into a single fair value anchor of $361.83 per share. That reference point sits about 12.6% above the last closing price. This means the story being told by that framework is more optimistic than the message from the current market quotation.
For readers weighing the STORM-PE result against Penumbra’s track record and analyst assumptions, the key question is whether the implied earnings power and margin profile that support the $361.83 figure feel realistic enough to close that gap over time, or whether the recent 46.76% three year total shareholder return already reflects the bulk of the opportunity.
Result: Fair Value of $361.83 (UNDERVALUED)
Still, the Penumbra story can change quickly if the integration with Boston Scientific drags on earnings or if margin progress stalls after the Q1 2026 shortfall.
Find out about the key risks to this Penumbra narrative.
Another View On Penumbra’s Valuation
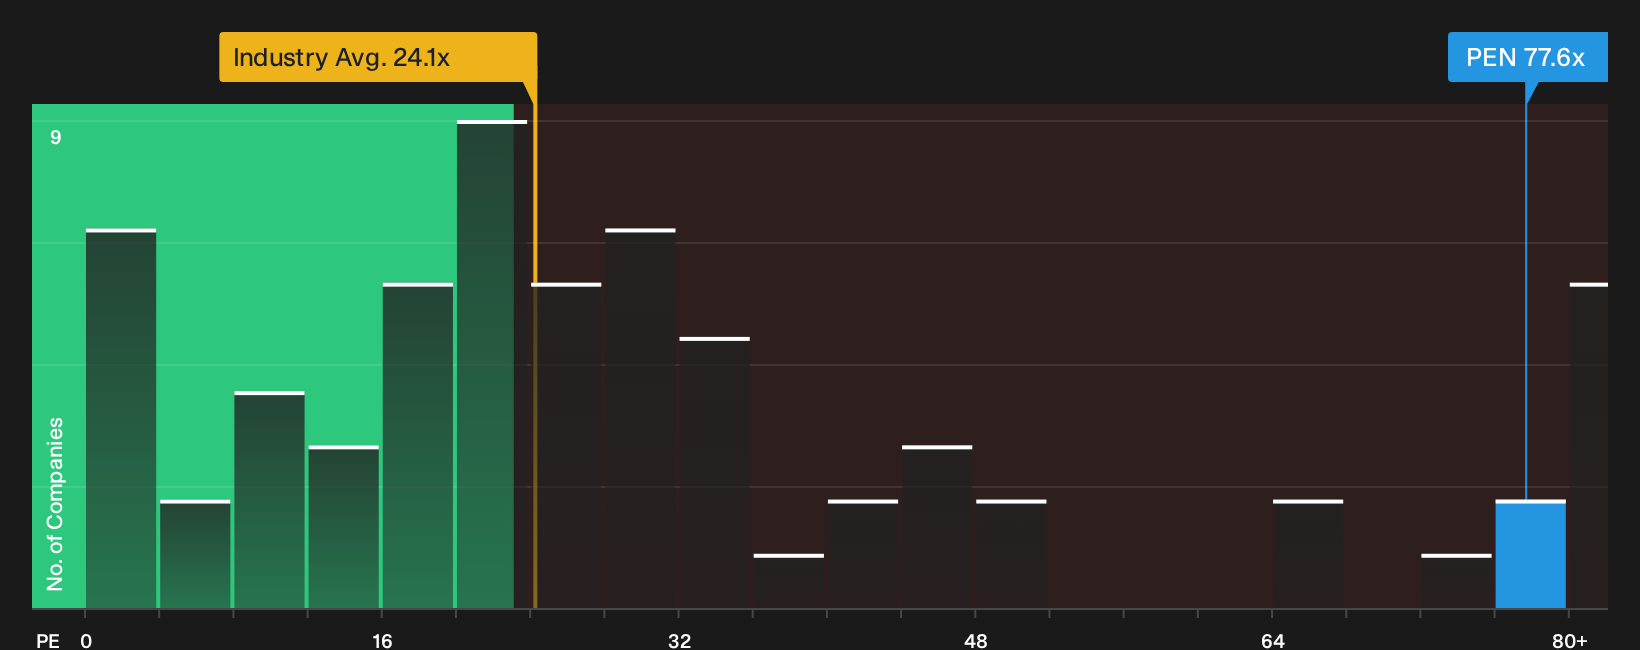
That fair value story clashes with what the market is paying for Penumbra today. The stock trades on a P/E of about 77.6x, compared with 24.5x for the US Medical Equipment group and a peer average of 22.4x. The fair ratio sits closer to 28.3x, which points to a rich tag and raises the question of how much execution risk investors are willing to accept at this price.
For a closer look at how that P/E gap could compress or persist over time, review the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment in this piece skews optimistic. If you feel the clock is ticking on Penumbra, stress test the upside yourself and then see how that compares with the 2 key rewards.
Looking for more Penumbra-like investment ideas?
If Penumbra has caught your eye, do not stop there. Cast the net wider now so you are not relying on a single story.
- Target rock solid balance sheets and durable fundamentals by screening a curated list of solid balance sheet and fundamentals (25 results) that can handle rougher market patches.
- Hunt for mispriced quality by running the 29 high quality undervalued stocks and compare businesses where price and underlying strength look out of sync.
- Stack potential income and resilience together by scanning a focused 8 dividend fortresses that leans on higher yields backed by stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com