


Is Robert Half (RHI) Fully Priced On Its Forbes Best Employers Recognition?
Why Forbes recognition matters for Robert Half stock
Robert Half (RHI) has just been named to Forbes' World's Best Employers 2026 list, an event that puts the spotlight on its culture, employee satisfaction, and how that might intersect with long term shareholder value.
The accolade is based on a large scale independent survey of more than 300,000 employees across 50 countries, with respondents evaluating workplace culture, inclusivity, career development, work life balance, and broader corporate reputation. Investors tracking Robert Half as a talent solutions and consulting business now have fresh third party data on how workers inside the organisation view those dimensions.
Recent trading tells a mixed story. Robert Half’s share price is up 24.18% year to date with a 4.14% 90 day gain, yet it has fallen 20.27% over the past month and 7.62% across the last week. The 1 year total shareholder return of 9.48% sits against a much weaker 3 year total shareholder return, which has declined 48.43%, and a 5 year total shareholder return that has dropped 60.85% as investors reassess both growth prospects and risk after periods of stronger performance.
Scan beyond Robert Half and see how other employers with strong workplace reputations are priced today by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
That mix of long term share price damage and a fresh short term slide raises a simple question. Are investors reassessing Robert Half’s fundamentals, or just swinging with sentiment? And how does the current valuation reflect that?
Most Popular Narrative: 3% Undervalued
Robert Half’s most followed valuation story pegs fair value at $35, slightly above the last close of $33.95. This points to a modest implied discount and puts the Forbes recognition in the context of a business already priced for gradual repair rather than perfection.
Protiviti’s technology consulting business, now roughly one third of segment revenue and delivering record quarterly revenue, is benefiting from client demand for platform and technology modernization, data, cyber and IT infrastructure work. This can help offset weaker risk and compliance work and support segment revenue and operating margin improvement over time.
See why 18 investors see Robert Half as 3% undervalued.
Result: Fair Value of $35 (UNDERVALUED)
Still, the Robert Half story can break if Protiviti margins stay under pressure or if the recent multiyear revenue and EPS declines persist longer than expected.
Find out about the key risks to this Robert Half narrative.
Another View on Robert Half’s valuation
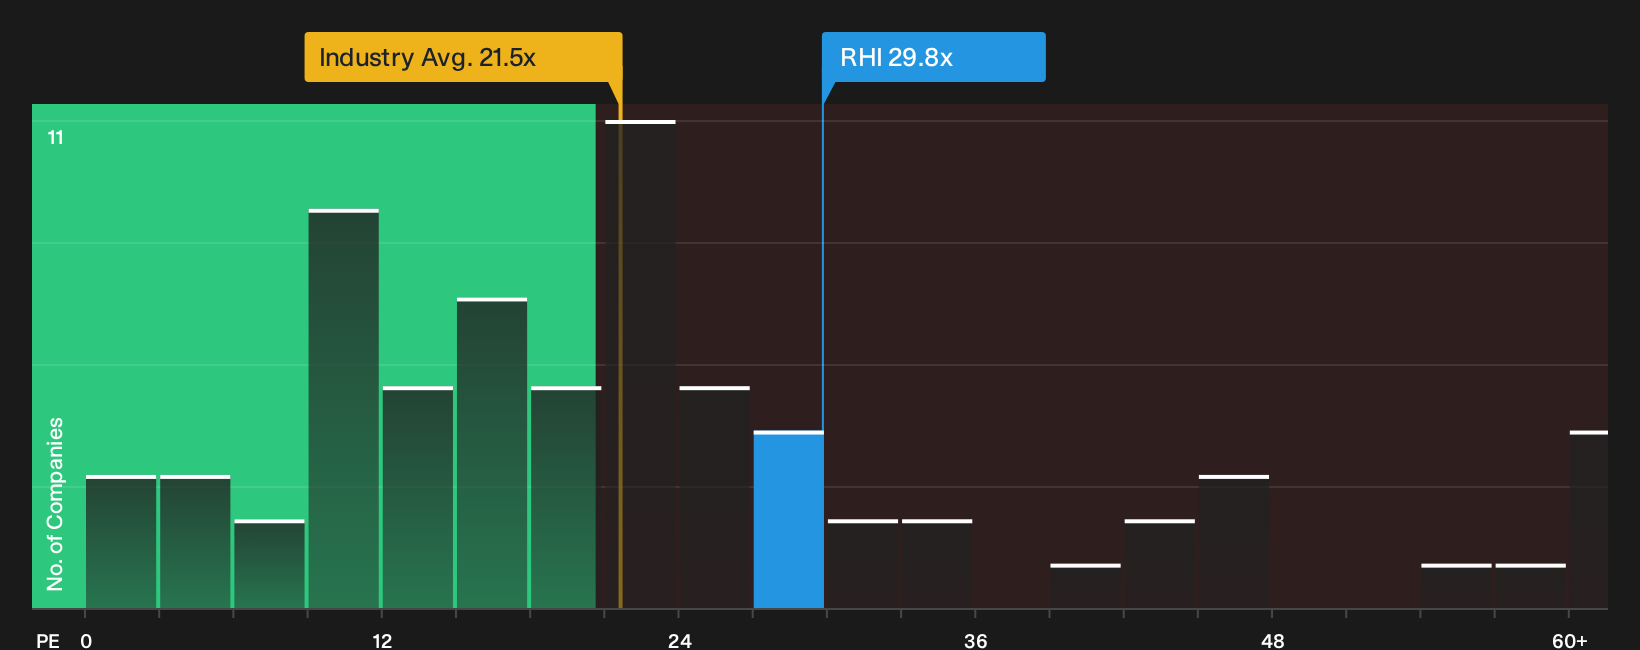
The story changes when you look at Robert Half through its P/E. The stock trades on 29.8x earnings, which is richer than both the US Professional Services sector at 21.5x and its peer group at 16.1x. The fair ratio of 29x suggests less cushion if sentiment turns.
That kind of premium can reflect confidence in the recovery story, or it can leave little room for disappointment if earnings slip again. It is therefore worth stress testing your own expectations against the valuation spread before making any move. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Robert Half’s story so far. If you want to move quickly and rely on your own judgement, start by weighing 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Robert Half?
If Robert Half has sharpened your focus on quality and pricing, do not stop here. Fresh ideas often come from comparing very different types of opportunities.
- Target potential mispricing by scanning 29 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying businesses.
- Strengthen your income stream by reviewing 8 dividend fortresses that pair higher yields with balance sheets that support ongoing payouts.
- Dial back portfolio stress by filtering for 31 resilient stocks with low risk scores built on resilient finances and steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com