


Japan Post Holdings (TSE:6178) Shares Dropped, So What Is Drawing Attention Now?
Japan Post Holdings (TSE:6178) has drawn fresh attention after recent trading, with the share price closing at ¥2,376.5. The move comes as investors reassess the group’s long-running mix of postal, banking, and insurance operations.
In the short term, momentum has cooled, with the share price declining 2.18% over the past day and 5.28% over the past week. However, Japan Post Holdings still carries a strong year to date share price return of 37.37% and a five year total shareholder return of 219.10%, which reflects long running strength.
Scan how Japan Post Holdings compares with other large, income-focused financials by reviewing our curated list of 32 dividend fortresses.
After a strong run and a short term pullback, Japan Post Holdings now trades only slightly below one valuation estimate. Does that set up a reasonable entry today, or justify waiting for a cheaper shot later on?
Price-to-Earnings of 15x: Is it justified?
Japan Post Holdings now trades on a P/E of 15x, which leaves the stock priced above both its peer group and the wider Asian insurance sector.
The P/E ratio compares the current share price to earnings per share. For a diversified financial group like Japan Post Holdings, it shows how much investors are willing to pay today for each unit of current profit.
Japan Post Holdings reports net profit margins of 3.8% compared with 3.2% last year. Forecasts indicate earnings growth of about 15.1% per year, quicker than the wider JP market. This may help explain why the market is assigning a higher multiple, even though the current Return on Equity of 4.9% is described as low and expected to reach only 7.4% in three years.
That premium is clear when compared with both peers and the estimated fair ratio. The current 15x P/E is described as expensive relative to the peer average of 11.6x and the Asian insurance industry average of 10.6x. However, it is viewed as good value versus an estimated fair P/E of 17.6x.
Explore the SWS fair ratio for Japan Post Holdings.
Result: Price-to-Earnings of 15x (ABOUT RIGHT)
Still, the narrative around Japan Post Holdings could be knocked off course if growth in its core insurance and banking operations slows, or if regulatory changes affect profitability.
Find out about the key risks to this Japan Post Holdings narrative.
Another View Using Our DCF Model
The DCF lens tells a slightly different story on Japan Post Holdings. Our model points to a fair value around ¥2,390, with the current price at ¥2,376.5. That is only a 0.6% gap. If the P/E looks a bit rich while the SWS DCF model looks fair, which signal would you trust more?
Look into how the SWS DCF model arrives at its fair value.
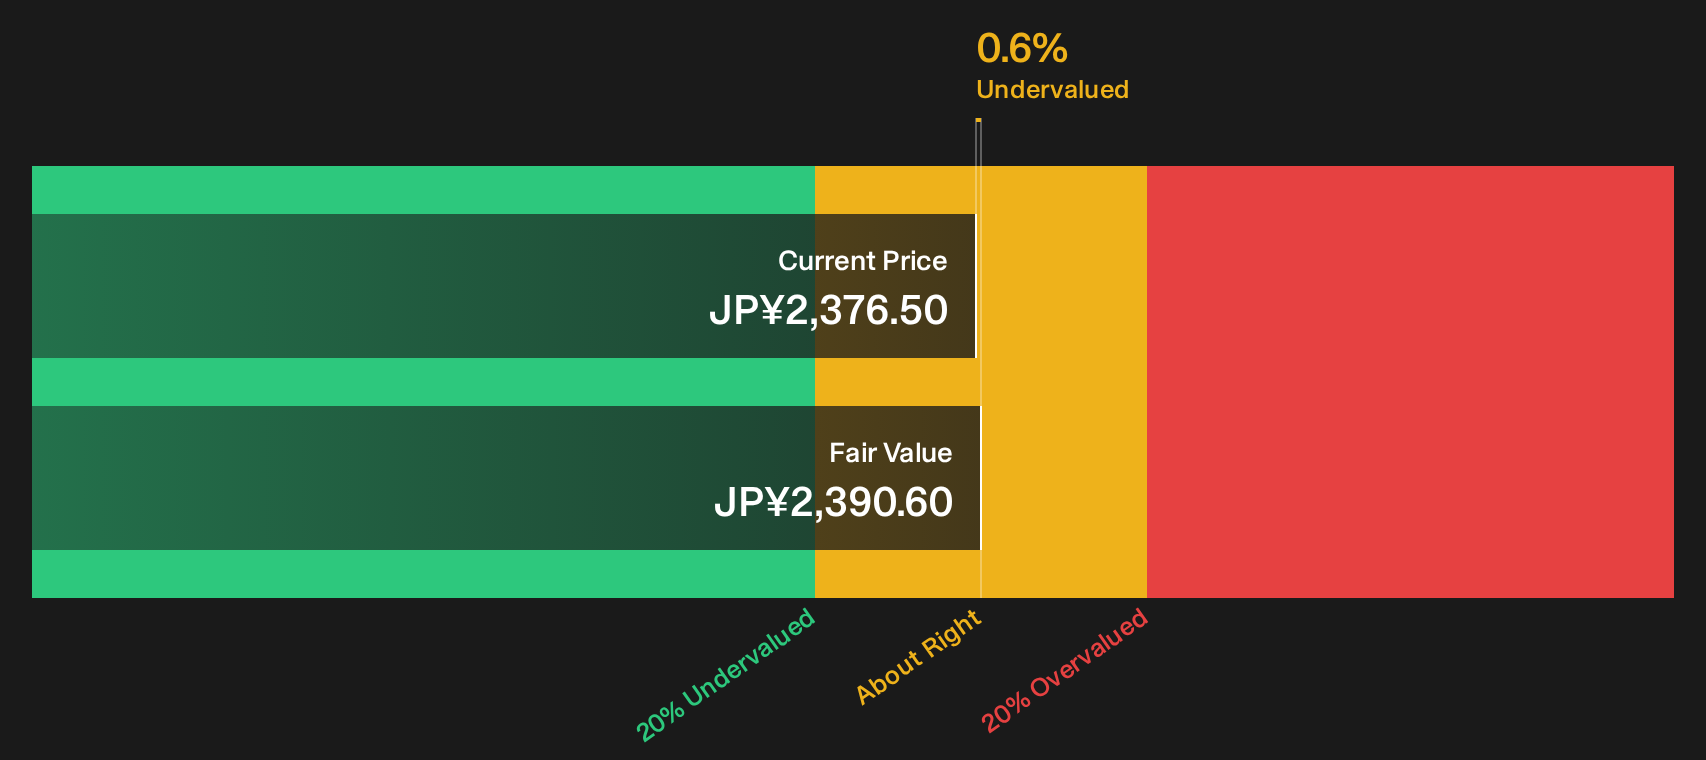
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Post Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Japan Post Holdings so far. If you want to move quickly and build your own conviction, start by weighing its 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Japan Post Holdings?
If Japan Post Holdings has sharpened your focus, do not stop here. Fresh ideas often come from comparing very different opportunities side by side.
Use these tailored screeners to pressure test your thinking and spot setups that might not stay available for long.
- Target steadier potential outcomes by reviewing companies screened for resilience and lower overall risk profiles through the 22 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price by checking companies that combine fundamentals with attractive pricing using the 14 high quality undervalued stocks.
- Spot opportunities with strong financial footing by scanning the list of solid balance sheet and fundamentals (23 results) and seeing which businesses keep their balance sheets in robust shape.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com