


Dear JPMorgan Stock Fans, Mark Your Calendars for Oct. 13
JPMorgan Chase (JPM) has been quietly flexing its muscle in 2026, rewarding investors with stable returns even as major peers such as Bank of America (BAC) and Wells Fargo (WFC) have struggled with negative returns this year. Backed by superior financials, a highly diversified business model, and conservative leadership, JPMorgan continues to strengthen its position as the undisputed heavyweight of the global banking industry.
With a market capitalization of roughly $880.60 billion, JPMorgan is now knocking on the door of the coveted $1 trillion milestone, and it remains by far the world’s most valuable bank. Its sheer scale is a key part of the story. JPMorgan has built a powerful presence across the United States and around the world, spanning consumer, commercial, and investment banking, while its wealth management business oversees trillions of dollars in assets under management (AUM).
Now, investors are turning their attention to the bank’s next potential catalyst. JPMorgan is set to lift the curtain on its fiscal 2026 third-quarter earnings report before the market opens on Tuesday, Oct. 13. With the results just around the corner, the big question is whether the banking giant can once again deliver the financial strength that has helped it outperform its peers. So, ahead of the highly anticipated earnings event, here’s a closer look at JPM stock.
About JPMorgan Stock
JPMorgan Chase is a leading U.S.-based financial services powerhouse with a global footprint spanning markets worldwide. As of June 30, JPMorgan Chase boasted a staggering $5 trillion in assets and $375 billion in stockholders’ equity, underscoring the sheer scale and financial strength of the banking giant.
The Firm is a dominant force across the financial landscape, with leadership positions in investment banking, financial services for consumers and small businesses, commercial banking, financial transaction processing, and asset management. Operating under the J.P. Morgan and Chase brands, JPMorgan serves millions of customers across the U.S., while also catering to many of the world’s most prominent corporate, institutional, and government clients globally.
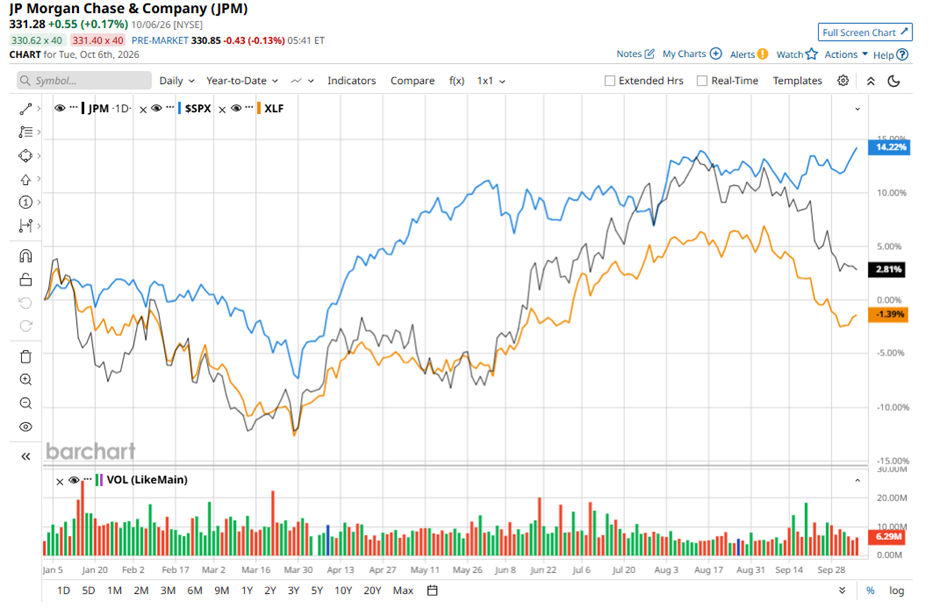
Turning to JPM’s stock performance, the bank’s shares have delivered stellar returns over the long term, although its performance in 2026 has been comparatively subdued. Over the past three years, JPM stock has surged nearly 123.8%, comfortably outpacing the S&P 500 Index’s ($SPX) 80.7% gain and underscoring the bank’s strong shareholder performance.
However, that winning streak has lost some momentum this year. JPM stock is up just 2.8% in 2026, significantly trailing the broader market’s 14.2% year-to-date advance. But despite falling behind the broader market, JPMorgan has remained one of the stronger performers among its banking peers. Bank of America stock has declined 1.7% so far in 2026, while Wells Fargo has suffered a much steeper 12.5% drop.
JPM’s relative strength becomes even clearer when compared with the broader financial sector. The State Street Financial Select Sector SPDR ETF (XLF), which provides exposure to major U.S. financial companies, is down nearly 1.4% this year. In other words, while JPMorgan has not kept pace with the broader stock market in 2026, it has continued to hold its ground better than several major banking peers and the financial sector overall.
Inside JPMorgan’s Financial Health
JPMorgan delivered a blockbuster fiscal 2026 second-quarter performance, with earnings soaring to levels rarely seen in the U.S. banking industry. The banking giant posted headline net income of $21.2 billion, up a whopping 41.2% year over year, the highest quarterly profit ever recorded by a U.S. bank. A powerful combination of big-ticket IPOs and dealmaking propelled investment banking fees to their highest level since 2021, while heightened market volatility gave JPMorgan’s trading desk another major tailwind.
Even after stripping out significant one-off gains, including a $4.6 billion net gain related to Visa shares and $1 billion in equity investment gains, JPMorgan’s core net income came in at $16.9 billion, or $6.14 per share. That easily topped Wall Street’s consensus estimate of $5.80 per share, highlighting the strength and breadth of momentum across the bank’s massive global franchise.
The top line was equally impressive. Total net revenue jumped 27% year over year to $57.35 billion on a reported basis, smashing Wall Street’s $51.30 billion expectation. Net interest income (NII) climbed 10% to $25.6 billion, while noninterest revenue surged 45% to $32.4 billion. More importantly, JPMorgan delivered records across every major line of business, underscoring the broad-based nature of the quarter’s strength.
The Corporate & Investment Bank (CIB) was a major growth engine, with revenue rising 27% annually to $24.85 billion, exceeding management’s expectations. Within CIB, Markets revenue jumped 35%, fueled by elevated client activity, strong trading performance, and continued demand for financing in Equities. Investment banking activity also accelerated, with IB fees soaring 30% to their highest level since 2021, while constructive market sentiment points to the potential for continued dealmaking activity.
Elsewhere, Payments and Securities Services each delivered double-digit revenue growth, supported by continued deposit and fee growth. In Consumer & Community Banking (CCB), revenue increased 8% year over year to $20.27 billion. Meanwhile, Asset & Wealth Management (AWM) remained another bright spot, with revenue climbing 19%. Strong client demand translated into $50 billion of net inflows into long-term AUM, helping push total assets under management above the $5 trillion mark, up 18% year over year.
Looking ahead, JPMorgan’s guidance remains firmly in focus. The bank expects fiscal 2026 NII of approximately $105.5 billion, although the outlook remains dependent on market conditions. Excluding its Markets business, fiscal 2026 NII is projected at around $96.5 billion. JPMorgan also expects full-year adjusted expenses of approximately $107.5 billion, setting the stage for another closely watched year as investors assess whether the bank can sustain its exceptional earnings momentum.
What Do Analysts Think About JPMorgan Stock?
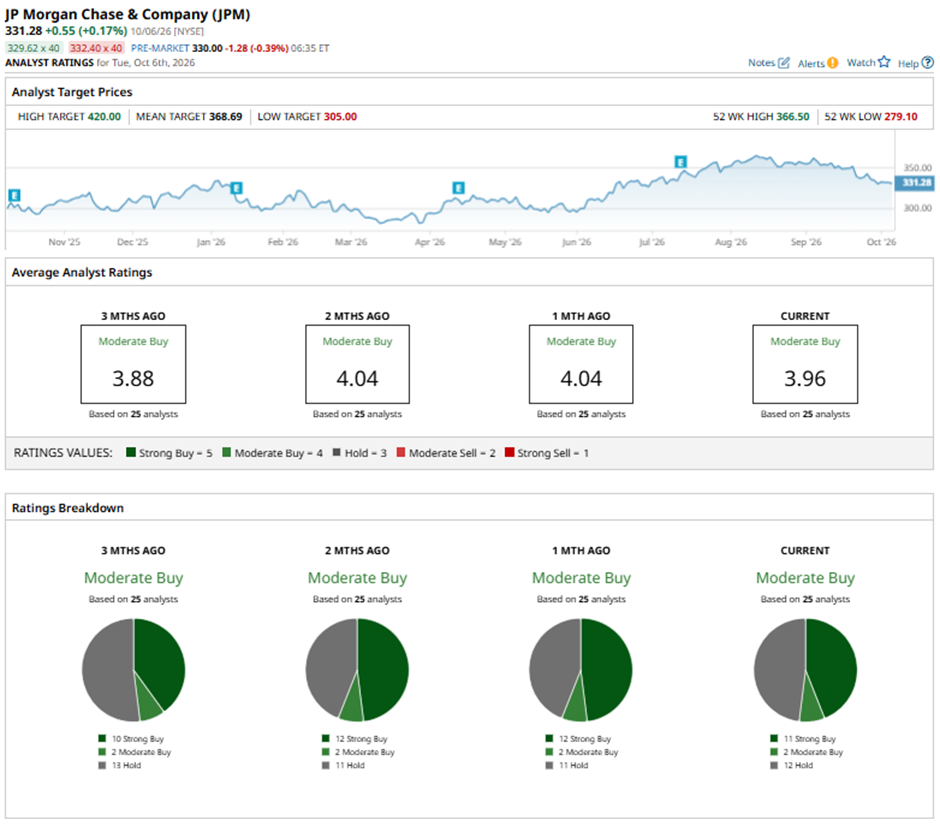
Overall, Wall Street remains firmly bullish on JPMorgan, with the stock carrying a consensus “Moderate Buy” rating. Among the 25 analysts covering the stock, 11 rate it a “Strong Buy,” two recommend a “Moderate Buy,” while 12 maintain a “Hold” rating, reflecting a broadly positive, though somewhat divided, outlook.
The Street’s price targets point to further room for JPMorgan to climb. The average target of $368.69 points to an 11.3% gain from current levels, while the Street-high target of $420 represents a potential 26.8% advance.
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.