


Marqeta (MQ) Earnings Optimism Puts Its Valuation Story Back In Focus
Why Marqeta Stock Is Back in Focus Ahead of Earnings
Marqeta (MQ) is drawing fresh attention after analysts lifted third quarter earnings estimates, pointing to very strong projected year over year profitability gains ahead of the 3 November 2026 results release.
Recent trading shows Marqeta regaining some momentum, with a 90 day share price return of 9.99% and a 1 day move of 3.08%. However, the year to date share price return is down 8.08% and the 1 year total shareholder return is down 16.21%.
Scan beyond Marqeta and explore other fast-moving fintech and financial services players by using our hand picked list of 20 high quality undiscovered gems for ideas at a similar stage of the story.
After a sharp 90 day rebound yet a weaker track record over one and five years, Marqeta now asks a simple question of investors: Does the current valuation still leave enough upside to justify the risk from here?
Most Popular Narrative: 18% Undervalued
Marqeta’s most followed valuation story pegs fair value at $20.74 per share, which sits above the recent $17.06 close and frames the latest earnings optimism through a longer term lens.
The completed TransactPay acquisition gives Marqeta full program management and EMI capabilities in Europe, enabling entry into larger enterprise opportunities, uniformity of service across North America and Europe, and easier multi market expansion for clients. This unlocks new revenue streams, increases take rates, and improves earnings scalability.
See why 13 investors see Marqeta as 18% undervalued.
Result: Fair Value of $20.74 (UNDERVALUED)
Still, the Marqeta narrative rests heavily on a small group of big customers and faces rising competitive and regulatory pressure. Those forces could quickly reshape those upbeat assumptions.
Find out about the key risks to this Marqeta narrative.
Another Way To Look At Marqeta’s Valuation
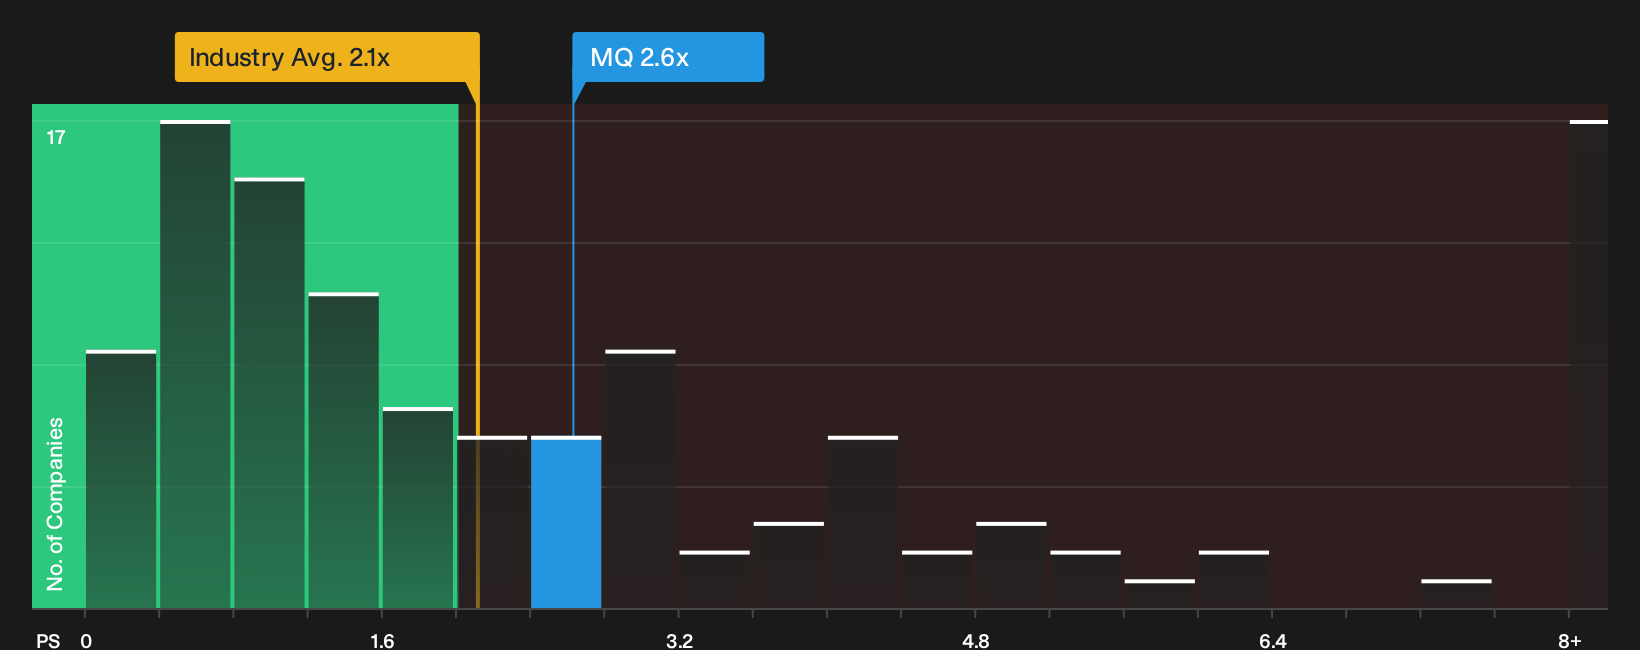
The story shifts once the focus moves to Marqeta’s revenue multiple. The stock trades on a P/S of 2.6x compared with 2.1x for the wider US Diversified Financial group and a fair ratio of 2.1x. That premium points to less room for error if growth or margins fall short. Which version of value matters more to you: the narrative fair value or what peers are actually priced at?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the mixed tone around Marqeta’s recent move and valuation debate. Act quickly, stress test the optimism yourself, and see what analysts highlight in the 2 key rewards.
Looking For More Investment Ideas Beyond Marqeta?
If Marqeta has your attention, do not stop here. Broaden your watchlist now, or risk missing opportunities that fit your style far better.
- Target potential mispricing by scanning companies that screen well on quality and value through our 29 high quality undervalued stocks.
- Prioritise resilience by checking out a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks and funding pressure.
- Sharpen your income focus by reviewing a curated pool of 8 dividend fortresses that combine yield with staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com