


Novanta (NOVT) Draws Undervalued Interest, Is The Premium P E Too High?
Novanta (NOVT) drew fresh attention after its recent share move, with the price closing at $143.64. Investors are weighing that level against the group’s current size, earnings profile, and recent return pattern.
Recent trading has been choppy, with a 1-day share price return that declined 3.66% and a 90-day share price return down 5.29%. However, Novanta still carries a strong year-to-date share price gain of 29.24% and a 1-year total shareholder return of 39.87%, which points to longer term momentum holding up despite near term volatility.
Scan beyond Novanta and evaluate other robotics and automation plays with resilient fundamentals using the curated 88 robotics and automation stocks to see how this move compares across the sector.
Bulls point to Novanta’s recent momentum and revenue and earnings growth. Bears focus on the rich valuation signals. As you weigh what the stock is actually worth, which side do the current numbers lean toward?
Most Popular Narrative: 26% Undervalued
Against Novanta's last close at $143.64, the most followed narrative pegs fair value at $194.50. The thesis therefore leans on a sizable gap that hinges on recurring medical and automation demand actually flowing through to margins.
Expansion of minimally invasive and robotic surgery, together with the Riverpoint Medical acquisition that roughly doubles recurring medical consumables revenue to about US$300 million and lifts medical exposure to around 60% of sales, increases Novanta's mix of repeat consumables that can support more resilient revenue and gross margin over time.
See why 6 investors see Novanta as 26% undervalued.
Result: Fair Value of $194.50 (UNDERVALUED)
Still, the Novanta narrative can wobble if Medical Solutions margins stay pressured, or if the Riverpoint Medical deal delivers slower integration and cash flow benefits than expected.
Find out about the key risks to this Novanta narrative.
Another View: Novanta Through The P/E Lens
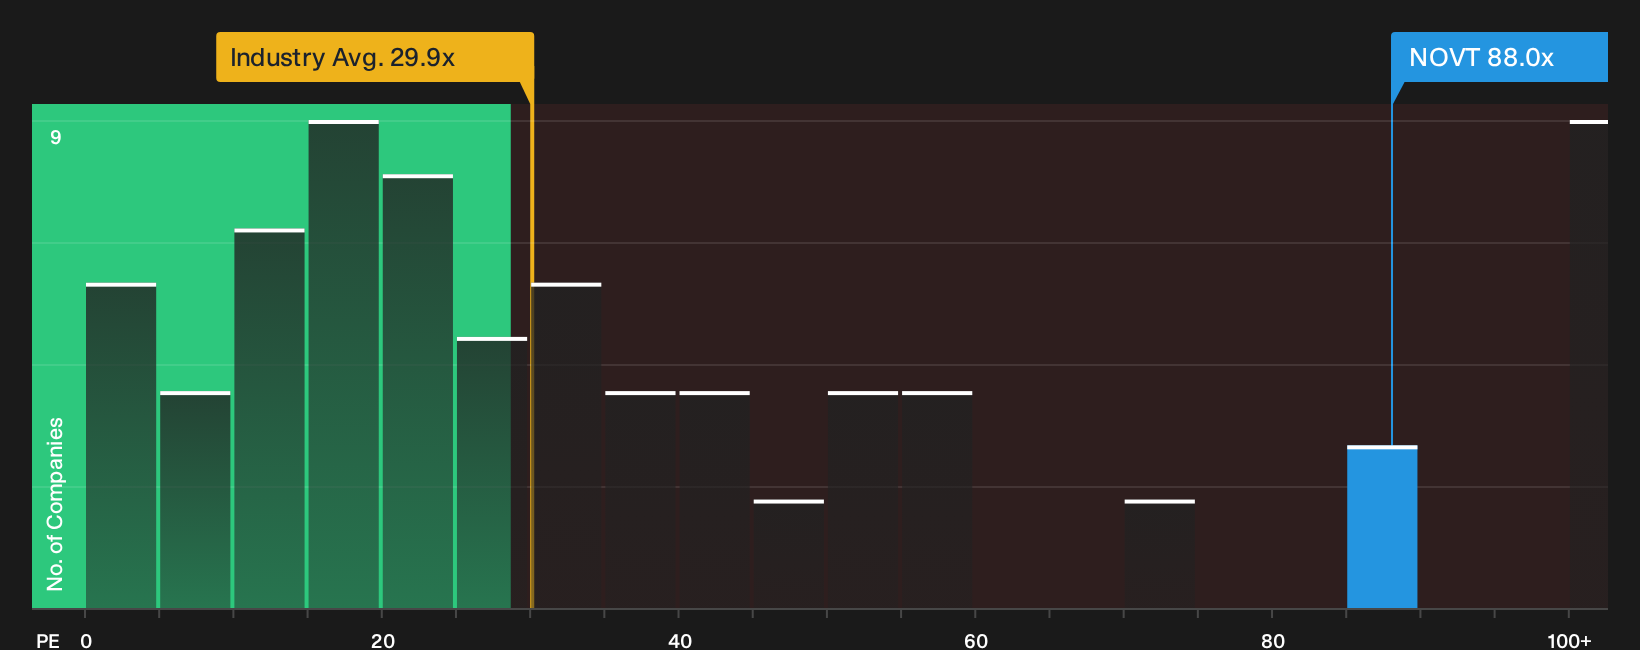
The story around Novanta shifts once valuation is framed through the current P/E rather than the $194.50 fair value narrative. The stock trades on roughly 88x earnings versus about 30.3x for the US Electronic industry and 54.5x for peers. The fair ratio sits even lower at 40.7x.
That gap suggests investors are already paying a heavy premium for the future earnings profile. If profits or margins fall short of expectations, the share price could have more to lose than a typical peer. How comfortable are you with that kind of valuation stretch?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Novanta story can be useful if you treat them as a prompt to inspect the figures yourself and stress test your own thesis. To weigh both the upside potential and the concerns being flagged, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Novanta?
If Novanta has sharpened your thinking, do not stop here. Broaden your watchlist and give yourself better odds of spotting opportunities before the crowd.
- Target value first and see which companies combine quality fundamentals with discounted prices through the 29 high quality undervalued stocks.
- Focus on resilience and inspect a 31 resilient stocks with low risk scores that could help steady your portfolio when volatility picks up.
- Hunt for early-stage potential by scanning a 12 elite penny stocks with strong financials that filters for stronger financial profiles instead of pure speculation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com