


NorthWestern Energy Group (NWE) Jumps As Fair Value Debate Tightens
NorthWestern Energy Group (NWE) rose 8.5% after Barclays maintained its Overweight rating while slightly lowering its price target. Heavier trading suggested strong institutional activity around the utility.
That sharp move comes on top of a 14.24% year to date share price return and a 30.31% total shareholder return over the past year. NorthWestern Energy Group has delivered 71.10% total shareholder return over three years, suggesting momentum has been building rather than fading.
Scan for other utilities showing similar momentum and institutional interest with our curated list of 43 power grid technology and infrastructure stocks alongside NorthWestern Energy Group's latest move.
After an 8.5% jump and a one year total return above 30%, NorthWestern Energy Group now trades slightly above the Barclays target. Is most of the upside already spent, or does the valuation still leave room?
Most Popular Narrative: 0% Overvalued
NorthWestern Energy Group closed at $73.97, almost exactly in line with the most followed fair value estimate of $73.75. This leaves sentiment tightly anchored to the success of its growth and merger plans rather than a clear pricing gap.
NorthWestern Energy Group’s 2026 to 2030 capital plan of about US$3.2b in regulated generation and transmission projects, alongside potential regional transmission opportunities such as the North Plains Connector and Colstrip path upgrades, provides a visible pipeline of rate base investments that can support regulated revenue and earnings growth.
See why 7 investors see NorthWestern Energy Group as 0% overvalued.
The widely followed narrative applies a 7.24% discount rate and lands on a fair value of $73.75, almost identical to where NorthWestern Energy Group trades after the latest rally. With only a rounding difference between price and this estimate, the story hinges on whether the planned data center load, capital program, and Black Hills merger all play out broadly in line with expectations rather than on a clear mispricing today.
Result: Fair Value of $73.75 (ABOUT RIGHT)
Still, NorthWestern Energy Group could face real pressure if higher secured debt costs squeeze cash flows or if Colstrip related expenses are not fully recovered through regulators.
Find out about the key risks to this NorthWestern Energy Group narrative.
Another View On NorthWestern Energy Group’s Valuation
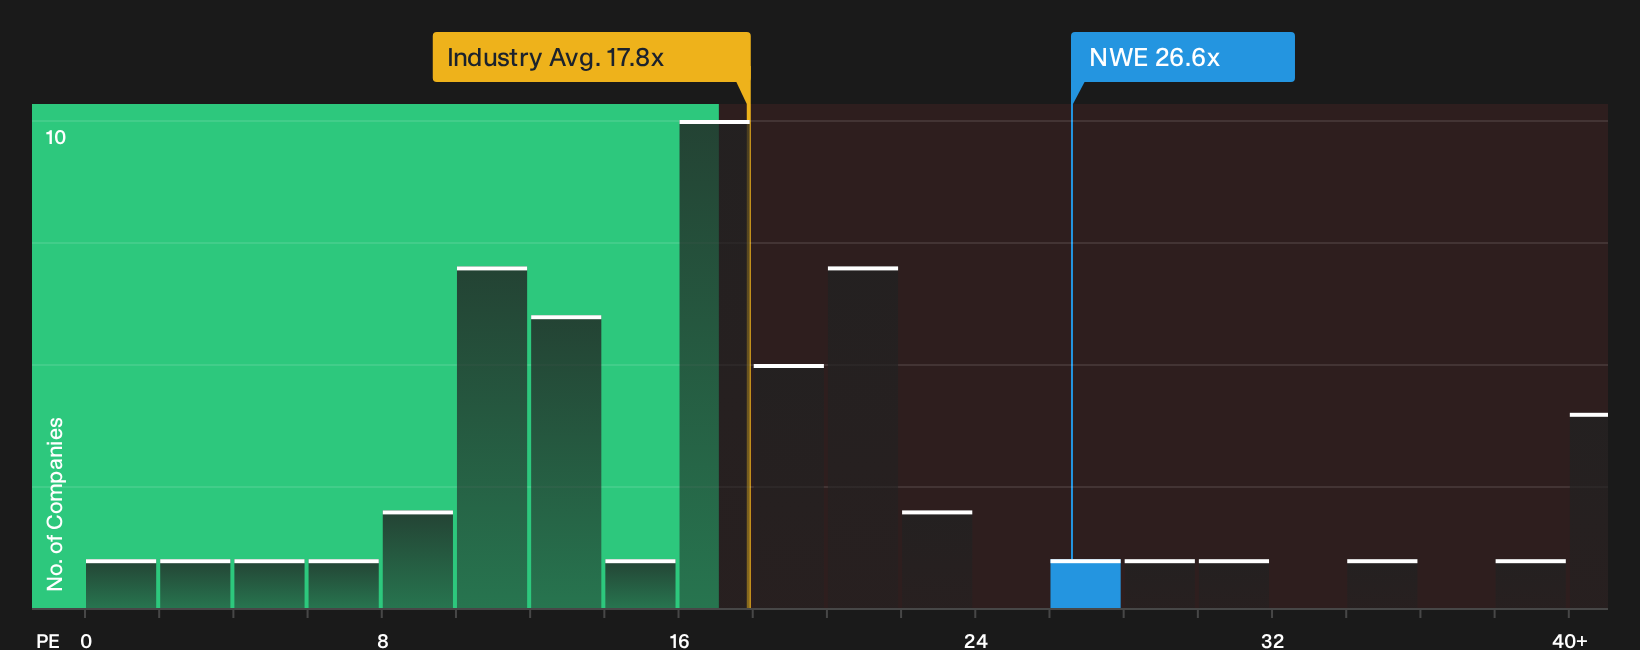
The fair value story around $73.75 sounds tidy, yet NorthWestern Energy Group screens very differently when you look at its P/E. The stock trades on 26.6x earnings compared with a 19x fair ratio estimate and a 17.8x industry average, while peers sit around 28.1x. That kind of gap points to limited margin for error rather than a clear bargain. How comfortable are you paying up for this earnings profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on NorthWestern Energy Group’s valuation and risk profile can be confusing, so review the underlying data, weigh both sides of the story, and then check the 1 key reward and 3 important warning signs
Looking for more investment ideas beyond NorthWestern Energy Group?
If NorthWestern Energy Group has sharpened your focus on quality and pricing, do not stop here. Broader idea hunting can help you build a more resilient portfolio.
- Target reliable cash generators by scanning for 29 high quality undervalued stocks that combine solid finances with prices that look out of step with their fundamentals.
- Strengthen your core holdings with a list of solid balance sheet and fundamentals (25 results) that can help you focus on companies carrying less financial strain.
- Stay early to potential opportunities by reviewing a 20 high quality undiscovered gems that the wider market may not be paying attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com