


How India Seating Venture Could Impact Forvia Stock Investors
- Forvia recently agreed with India's Anand Group to create Faurecia Anand Seating India Private Limited, a joint venture producing seat frames and complete seats. Forvia will retain control and is targeting about 10% share of the local seating market over five years.
- The move deepens Forvia's manufacturing footprint in India, linking its seating know how to Anand Group's local relationships, which may influence cost efficiency, sourcing decisions, and the mix of future regional earnings.
- We will now look at how Forvia's India seating joint venture could reshape its investment narrative built around localization and deleveraging.
Scan how Forvia's push into localized auto components compares with other potential reshoring beneficiaries by reviewing our curated list of list of solid balance sheet and fundamentals (207 results).
Forvia Investment Narrative Recap
For an investor to own Forvia, belief needs to center on its ability to turn a broad auto technology portfolio into steadier cash generation while working through heavy restructuring and leverage. The core near term swing factor remains execution on cost programs and asset disposals, because interest costs are stretching current earnings and refinancing risk sits in the background.
The India seating joint venture fits the localization and regional mix story, but it does not change those near term priorities in a big way yet. The main risk still comes from high transformation spend and exposure to China, where any trade barriers or weak pricing could pressure already thin margins.
The Anand Group seating partnership in India looks most relevant here. It speaks directly to one of Forvia's key catalysts, which is shifting more production closer to end markets in Asia to support interiors and seating volumes. That sort of local build out can influence operating margins and help diversify revenue away from more exposed regions.
For an investor watching catalysts, the India move matters if it feeds into higher quality orders and a better regional balance alongside electronics and interiors growth. The bigger test will be whether this expansion can coexist with deleveraging efforts, given interest costs are not well covered and management is relying on significant disposals and savings projects.
Forvia's narrative references analyst expectations for revenue of €21.3b and earnings of €484.8 million by 2029, compared with a loss of €1.5b today. This implies a very large earnings improvement in value terms but only flat top line performance, since analysts describe revenue as remaining fairly stable over the next 3 years.
Uncover how Forvia's fair value indicates a 54% potential upside to its current price that could narrow quickly if sentiment toward Forvia shifts.
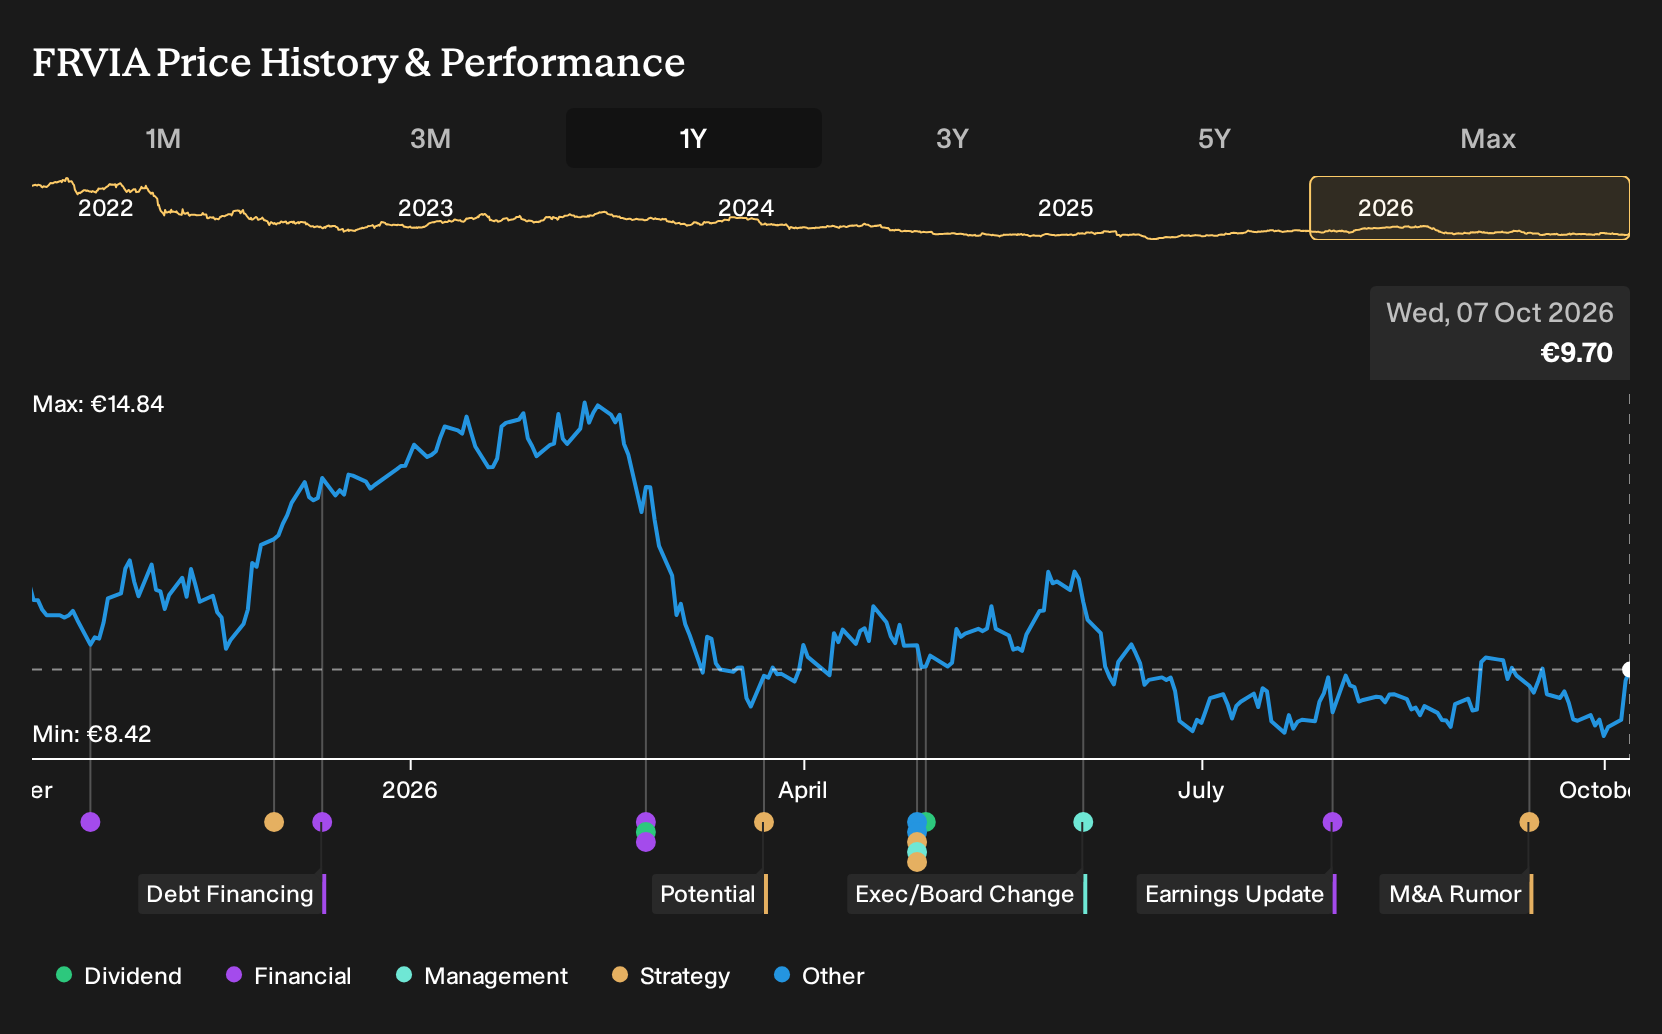
Exploring Other Perspectives
Some of the most optimistic analysts frame the India joint venture as a springboard for faster earnings recovery rather than just a localization story. They were already pencilling in revenue of €29.6b and earnings of €914.9 million by 2028 for Forvia. Views like that could shift again once this new deal is fully reflected.
Explore 2 other Forvia fair value estimates, including one that suggests as much as 158% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Forvia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Forvia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Forvia's overall financial health at a glance.
Looking for more investment ideas beyond Forvia?
If Forvia is on your radar, it often pays to compare it with a few other opportunities that match your preferred risk, income, or quality profile. The Simply Wall St Screener lets you scan wider and keep your watchlist focused on businesses that actually fit your approach.
- If capital preservation is top of mind, start with companies screened as 225 resilient stocks with low risk scores so you can focus on businesses with steadier profiles.
- If income matters more to you right now, look at stocks filtered as 228 dividend fortresses and see which payers align with your yield and sustainability preferences.
- If you want potential mispricing combined with solid fundamentals, review our curated set of 183 high quality undervalued stocks and compare how they stack up against Forvia on quality and price.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com