


Great Wall Motor (SEHK:2333) Following Softer September Volumes Is This Cheap Enough Yet
Great Wall Motor (SEHK:2333) just put fresh operating data on the table. September 2026 unaudited figures show softer monthly sales and production compared with last year, while year-to-date volumes look closer to flat.
Against that operational backdrop, Great Wall Motor’s shares trade at HK$7.115, with the 30 day share price return down 6.81% and the year to date share price return down 52.94%. The 1 year total shareholder return has fallen 56.55%, signalling pressure on sentiment. However, 3 and 5 year total shareholder returns show smaller declines over the medium term than over the past year.
Compare Great Wall Motor’s recent pressure with other hand picked auto and manufacturing peers by scanning the list of solid balance sheet and fundamentals (207 results) that may pair steadier operations with stronger balance sheets.
Great Wall Motor’s share price slide and softer recent volumes set up a clear fork in the road. Do you treat today’s level as enough of a reset, or hold out for a cheaper valuation before stepping in?
Preferred P/E of 8.7x: Is it justified?
Great Wall Motor trades on a P/E of 8.7x, which sits well below several comparison points, even as the HK$7.115 share price reflects recent share price pressure.
The P/E ratio compares what investors currently pay for each dollar of earnings with the profits the business generates. For an automaker with sizeable operations in China and overseas, it gives a simple temperature check on how the market is weighing current profitability against future earnings potential.
On relative terms, the gap is wide. Great Wall Motor’s 8.7x P/E is described as good value versus the Asian auto industry average of 13.5x and also looks low against the peer group average of 23.7x. At the same time, the P/E sits slightly above an estimated fair P/E of 8.3x, which implies the market could shift toward that level if sentiment and expectations converge toward the fair ratio over time.
Explore the SWS fair ratio for Great Wall Motor.
Result: Price-to-Earnings of 8.7x (UNDERVALUED)
Still, Great Wall Motor faces risks if global demand for its vehicles softens further or if competitive pricing in China tightens its already pressured profitability.
Find out about the key risks to this Great Wall Motor narrative.
Another View on Great Wall Motor’s Valuation
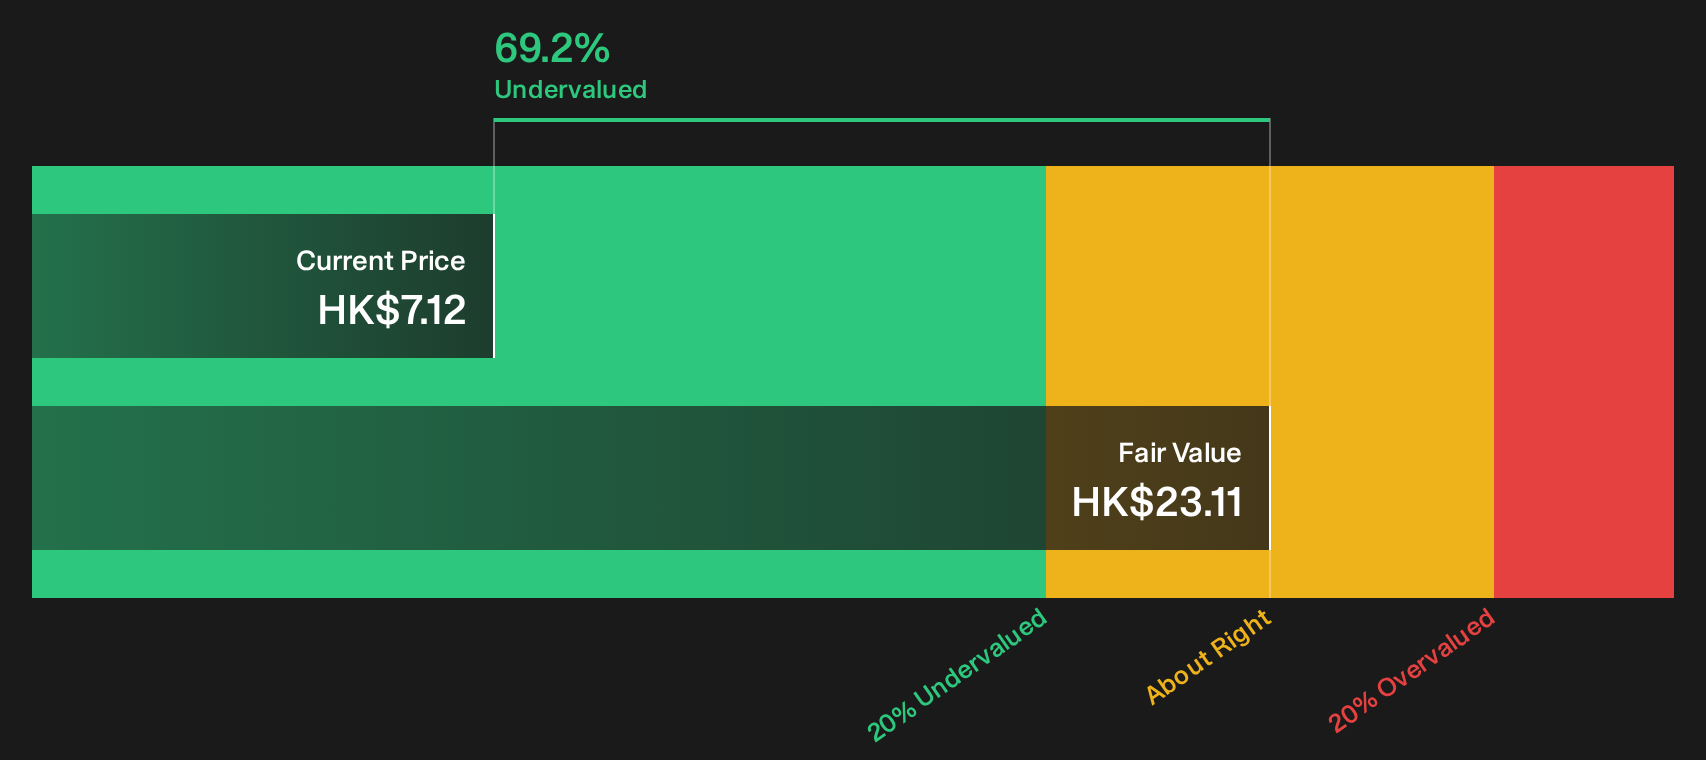
The P/E points to Great Wall Motor looking cheap, but the SWS DCF model tells a stronger story. On that approach, the HK$7.12 share price sits well below an estimated fair value of HK$23.11, which presents the stock as heavily undervalued on cash flow assumptions.
That is a sizable valuation gap for any investor to weigh. It raises a simple question: Are the DCF inputs too optimistic, or is market sentiment pricing in more risk than the earnings multiple alone suggests?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Great Wall Motor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Great Wall Motor is clearly split, with pressure on recent trading data but a valuation gap that some investors may find intriguing. If you want to move quickly and form your own view using both angles, start with the 2 key rewards and 3 important warning signs
Looking for more Great Wall Motor sized investment ideas?
You do not have to stop with Great Wall Motor. Use these focused screens to spot other opportunities that might better match your risk and return goals.
- Target stronger downside protection by reviewing companies in the 225 resilient stocks with low risk scores that score well on resilience and financial stability.
- Hunt for mispriced potential by scanning the 619 high quality undiscovered gems with solid fundamentals that have not yet attracted broad market attention.
- Build a portfolio with staying power by assessing dividend payers through the 224 dividend fortresses that combine higher yields with robust underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com