


Atmus Filtration Technologies (ATMU) Could Be 32% Undervalued As Margin Pressure Draws Focus
Profit Pressure Puts Atmus Filtration Technologies In Focus
Atmus Filtration Technologies (ATMU) is drawing fresh investor attention as slower annual revenue growth, supply chain challenges, and high production costs converge to keep its gross margin and overall profitability under pressure.
Recent trading has echoed those profit concerns, with Atmus Filtration Technologies’ share price slipping 4% in the last session and down 15.8% year to date to US$44.12, even though the 3 year total shareholder return of 119.1% still points to a much stronger longer term journey.
Spot undervalued industrial filtration peers to compare with Atmus Filtration Technologies by scanning our curated list of 20 high quality undiscovered gems.That drop in Atmus Filtration Technologies now leaves a puzzle. Are investors finally reacting to the low margin profile and slower growth, or has sentiment swung harder than the underlying business justifies as valuation resets come into focus?
Most Popular Narrative: 32% Undervalued
Atmus Filtration Technologies carries a narrative fair value of $65.20 against the last close at $44.12, which frames the recent share price weakness as a discount rather than a verdict on the long term earnings story.
The expansion into industrial filtration through Koch Filter, with Industrial Solutions guided to US$155 million to US$165 million of 2026 revenue at roughly 20% EBITDA margins, gives Atmus a new platform tied to data centers, healthcare and HVAC that can support revenue growth and margin diversification.
See why 2 investors see Atmus Filtration Technologies as 32% undervalued.
Result: Fair Value of $65.20 (UNDERVALUED)
Still, the Atmus Filtration Technologies narrative hinges on sustaining record quarterly revenue and successfully integrating Koch Filter while maintaining those targeted Industrial Solutions margins.
Find out about the key risks to this Atmus Filtration Technologies narrative.
Another View: Cash Flows Paint A Tougher Picture
Analyst targets and narrative fair value numbers suggest Atmus Filtration Technologies looks attractively priced at $44.12 against a $65.20 fair value. The SWS DCF model tells a different story. On future cash flows, Atmus is valued at $26.71 per share, which points to an overvalued stock on that framework.
This gap between earnings based and cash flow based estimates matters. The first lens leans on projected profit growth and multiples. The DCF view implies investors are already paying ahead of those long term cash returns. The key question is which yardstick you trust most for a filtration business with high debt and evolving margins, and why.
Look into how the SWS DCF model arrives at its fair value.
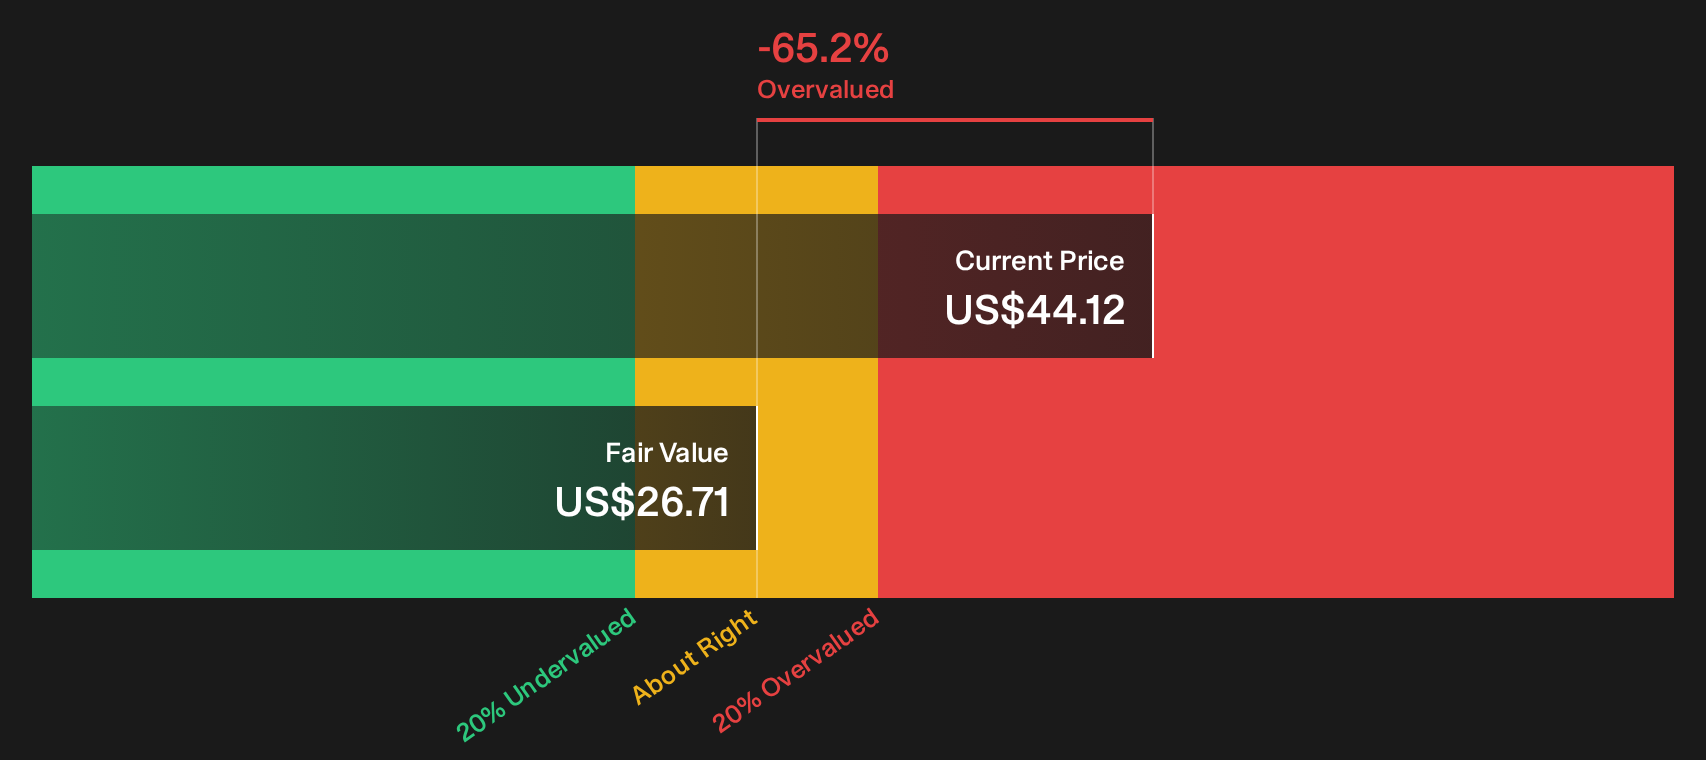
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atmus Filtration Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Atmus Filtration Technologies story feels pulled between optimism and caution, move quickly to study the underlying data and decide where you land. A balanced next step is to weigh both sides by checking the 5 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Atmus Filtration Technologies?
Do not stop at Atmus Filtration Technologies. Use the Simply Wall St screener to widen your watchlist with stocks that fit your risk, income, and value preferences.
- Target robust value opportunities by scanning our curated set of 29 high quality undervalued stocks that combine quality fundamentals with appealing entry prices.
- Build a steadier income stream by reviewing a focused group of 8 dividend fortresses that aim to pair strong balance sheets with meaningful yields.
- Reduce portfolio stress by filtering for 31 resilient stocks with low risk scores that score well on resilience so you are not caught off guard when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com