


Why Mizuho Leasing Company (TSE:8425) Is Getting Attention Today
Mizuho Leasing Company (TSE:8425) drew investor attention after recent trading left the share price near ¥1,268, with the stock down over the past week, month and past 3 months.
For context, the recent slide in Mizuho Leasing Company’s share price, with the latest close at ¥1,268 and the stock down over the past week and month, comes after a much stronger run. The 1-year total shareholder return is 1.82% and the 5-year total shareholder return is 118.24%. This suggests that short-term momentum has cooled while longer-term holders have still seen meaningful gains.
Look beyond Mizuho Leasing Company and compare its recent pullback with a curated group of resilient stocks on our 22 resilient stocks with low risk scores that pair steadier price action with lower risk profiles.
Mizuho Leasing Company now trades at a steep discount to estimated fair value, even after its strong multi year return. Is the market being sensibly cautious, or is this pullback mispricing the underlying business?
Price-to-Earnings of 7.1x: Is it justified?
On simple earnings terms, Mizuho Leasing Company changes hands at a P/E of 7.1x, while peers in the JP Diversified Financial industry average 13.8x and the broader peer set sits near 13.2x. That gap is wide enough for investors to ask whether the recent pullback has taken expectations too far in the other direction.
The P/E ratio compares the current share price with earnings per share and gives a quick sense of how much the market is willing to pay for each unit of profit. For a business like Mizuho Leasing Company that earns income from leasing, financing and related services, P/E is a direct read on how the market is weighing its profit engine against alternative opportunities in the same sector.
There are a few moving parts here. Earnings have grown 23.2% per year over the past 5 years, while the most recent year showed 17% growth, slightly slower than that longer trend and just behind the industry’s 17.6%. Net profit margins are steady to slightly higher at 6.1% compared with 6% a year earlier, and return on equity of 12.2% is described as low relative to a 20% benchmark. That combination suggests a solid but not exceptional profitability profile, which can help explain why the market assigns a lower multiple even with a history of earnings expansion.
Relative pricing against peers is still striking. A P/E of 7.1x compared with an industry average of 13.8x implies the stock trades at roughly half the earnings multiple of similar diversified financial firms, and also below the broader peer group on 13.2x. The Simply Wall St valuation framework also points to a steep discount, with the shares trading 62.3% below its estimate of fair value and at ¥1,268 compared with an estimated future cash flow value of ¥3,360.37 according to the SWS DCF model. Investors weighing Mizuho Leasing Company against sector alternatives are effectively being asked to decide whether this deep P/E and DCF discount reflect real concerns around leverage and funding, or whether they overshoot the risks attached to debt that is not well covered by operating cash flow and a dividend that is not fully supported by free cash flow.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 7.1x (UNDERVALUED).
Still, Mizuho Leasing Company faces real pressure points, including debt that relies heavily on operating cash flow and a dividend that is not fully backed by free cash generation.
Find out about the key risks to this Mizuho Leasing Company narrative.
Another View on Mizuho Leasing Company’s Value
The P/E gap makes Mizuho Leasing Company look inexpensive, yet the SWS DCF model paints an even starker picture. With the share price at ¥1,268 and an estimated future cash flow value of ¥3,360.37, the stock screens as heavily undervalued on cash flows as well as earnings. This raises the question of whether both gauges might be missing something important about risk and the durability of growth.
Look into how the SWS DCF model arrives at its fair value.
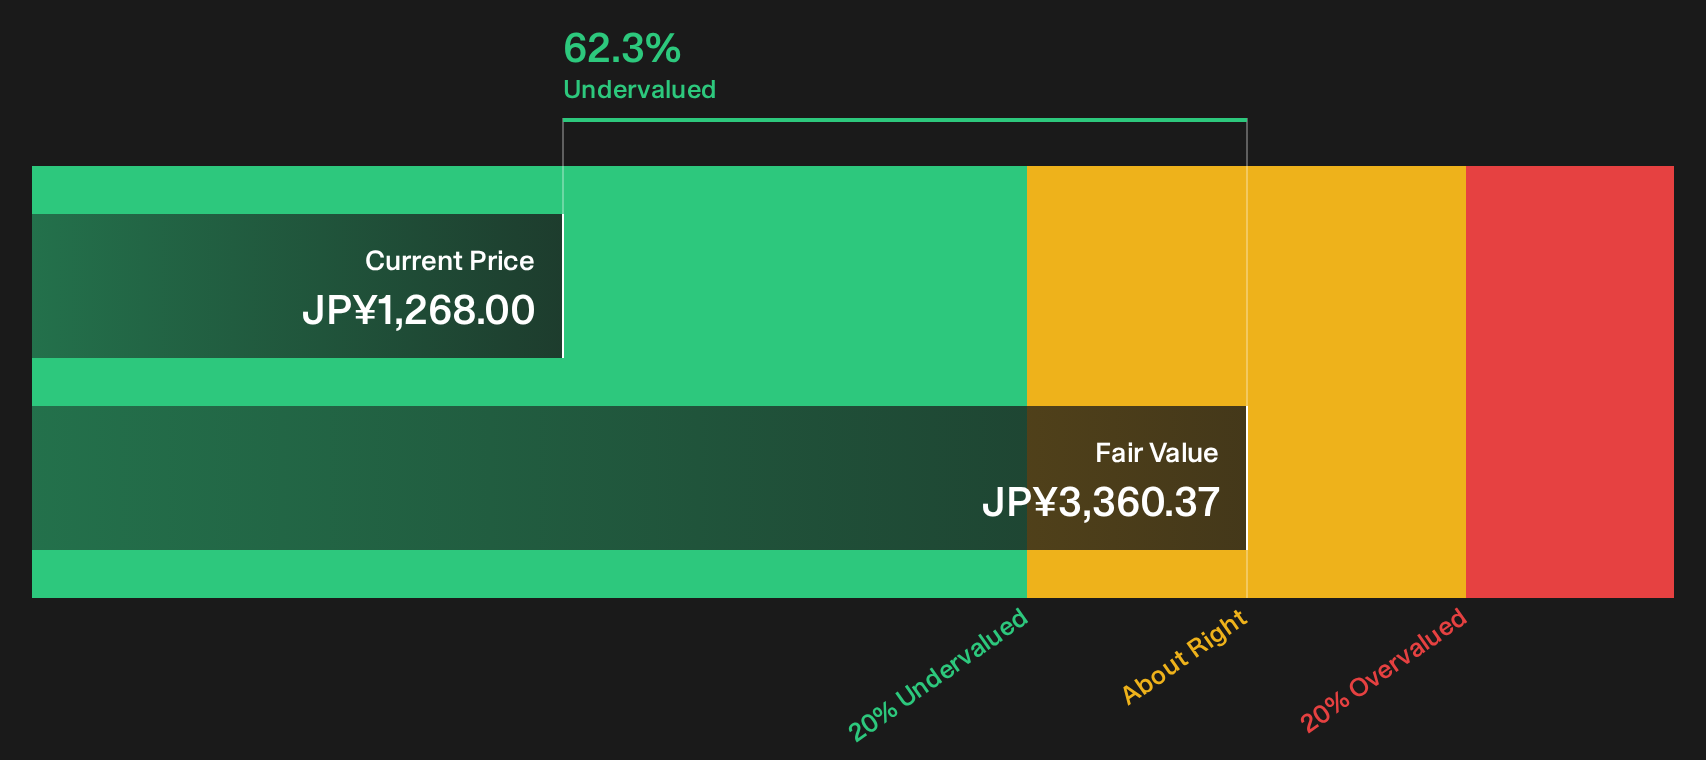
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mizuho Leasing Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mizuho Leasing Company so far. If you want to move fast and base your own view on the underlying data, start by weighing the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Mizuho Leasing Company?
If Mizuho Leasing Company has you rethinking your watchlist, use the Simply Wall Street screener to uncover fresh ideas that match your style and risk tolerance.
- Target potential value opportunities by tracking companies that screen as attractively priced with strong fundamentals through the 15 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that offer meaningful yields and resilient payouts via the 28 dividend fortresses.
- Raise the quality bar by focusing on companies with sturdy finances and consistent metrics using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com