


Takashimaya Company (TSE:8233) Draws Valuation Focus, Is The Recovery Story Already Priced In?
Takashimaya Company (TSE:8233) is drawing attention as a direct play on Japan's wage and inflation cycle, with forecast earnings growth closely linked to domestic consumer spending and cost trends.
Recent trading points to a mixed picture. The share price is up 1.35% over the last day and 3.20% over the past week, yet it is down 5.56% across three months. At the same time, a 31.56% year to date share price return and a 25.77% one year total shareholder return suggest momentum for Takashimaya Company has been building rather than fading.
Scan Takashimaya Company's peers exposed to Japan's consumer and wage cycle by reviewing our hand picked 75 high quality undiscovered gems for ideas that may be flying under most radars.
Takashimaya Company's recent surge, along with earlier volatility, highlights a straightforward tension. Has most of the accessible upside already materialized, or does the current valuation still leave meaningful room for further gains?
Preferred Price-to-Sales of 1.6x: Is it justified?
Takashimaya Company trades on a P/S ratio of 1.6x, and that tag looks demanding when set against both its own fundamentals and the wider multiline retail space.
The P/S metric compares the market value of the equity to its annual revenue, so it tells you how much investors are paying for each ¥1 of sales. For a retailer with cyclical exposure to consumer spending and wages, it is a simple way to see how strongly the market rates the current business model and its ability to turn top line into durable profits.
Here the picture is mixed. On one hand, Takashimaya Company is currently loss making, with a reported net loss of ¥4,108m and a negative return on equity of 0.55%, while its dividend yield of 1.84% is flagged as not well covered by earnings. On the other hand, forecasts point to earnings expanding by 45.47% per year and a move into profitability within three years, with revenue expected to grow 8.1% annually, which is described as faster than the wider JP market. The market may be paying up for that turnaround profile. However, compared to an estimated fair P/S of 1.5x, the 1.6x multiple looks rich and represents a level the valuation could gravitate back toward if expectations cool.
Against peers, the contrast is even sharper. The JP Multiline Retail industry average P/S is 0.6x, so Takashimaya Company's 1.6x ratio is described as expensive relative to sector norms, which suggests investors are assigning a much stronger recovery and earnings quality story here than the typical retailer.
Explore the SWS fair ratio for Takashimaya Company.
Result: Price-to-Sales of 1.6x (OVERVALUED)
Still, the recent net loss of ¥4,108m and a dividend flagged as not well covered by earnings could quickly challenge the upbeat Takashimaya Company recovery story.
Find out about the key risks to this Takashimaya Company narrative.
Another View on Takashimaya Company’s Value
The SWS DCF model tells a different story. At ¥2,174, Takashimaya Company trades well above an estimated future cash flow value of ¥1,012.87, which points to the shares looking expensive on this lens. If the cash generation does not catch up, how comfortable are you paying this premium?
Look into how the SWS DCF model arrives at its fair value.
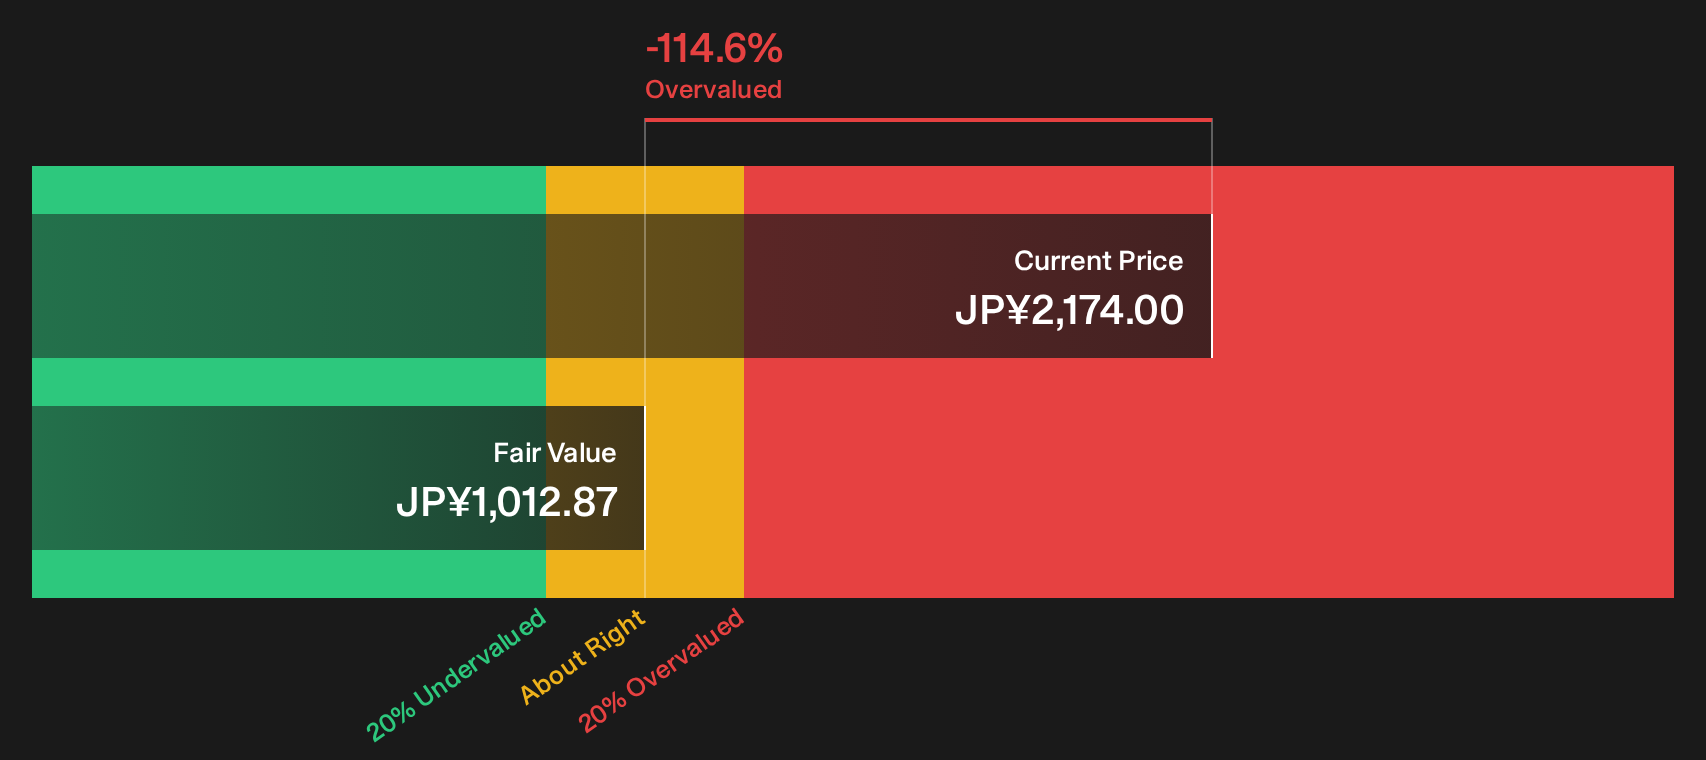
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Takashimaya Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Takashimaya Company is clearly split, which is exactly why it can be useful to move early, inspect the numbers yourself and decide where you land. To see how the upside case compares with the downside risks, review the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Takashimaya Company?
If Takashimaya Company has caught your attention, do not stop here. Use the Simply Wall Street screener to quickly surface other opportunities that might fit your approach.
- Target potential mispriced opportunities by running through the 15 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Strengthen your income focus by reviewing the 28 dividend fortresses that highlights companies offering higher yields with an emphasis on durability.
- Dial down portfolio risk by scanning the 22 resilient stocks with low risk scores which filters for businesses with more resilient profiles and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com