


Did Record Earnings Just Shift Carpenter Technology (CRS) Investment Narrative?
- Carpenter Technology reported record fiscal 2026 earnings, supported by strong aerospace and defense demand, on-track brownfield capacity expansion, and shareholder approval of key governance proposals.
- The combination of peak profitability and added high purity melt capacity highlights how Carpenter Technology is leaning into long-cycle aerospace and defense demand rather than treating current conditions as temporary.
- We will look at how Carpenter Technology's record earnings reshape the investment narrative as capacity expansion and governance decisions converge.
Scan the aerospace and defense supply chain beyond Carpenter Technology by reviewing our hand picked list of solid balance sheet and fundamentals (25 results), which could also be positioned for long-cycle demand.
Carpenter Technology Investment Narrative Recap
To own Carpenter Technology, you need to believe that demand for specialty alloys in aerospace, defense and energy stays healthy enough to support high utilization of its two segments: Specialty Alloys Operations and Performance Engineered Products. The record fiscal 2026 earnings confirm that the business can translate current demand into strong profitability when volumes and mix line up.
The key near term swing factor is execution on the brownfield expansion while end markets remain supportive. Management is spending heavily to add high purity melt capacity, so any stumbles in timing, budget, or customer appetite could pressure free cash flow. Dependence on cyclical aerospace and defense also remains the biggest operational risk.
The record fiscal 2026 earnings announcement is the clearest recent data point for investors. It shows Carpenter Technology operating at a very high level of efficiency and pricing, supported by aerospace and defense demand, at the same time that the brownfield expansion is reported as on schedule and within budget to support growing customer needs.
That pairing directly links the main catalyst and the main risk. The company is leaning into long cycle contracts and higher value alloys while committing around US$400m to new capacity over several years. If volumes and product mix hold up as that capacity comes online, the expansion can support higher throughput. If demand softens, those same assets could weigh on margins and cash generation.
Carpenter Technology's current earnings of $529.6 million are set against analyst expectations for earnings of $958.8 million by 2029 and revenue of $4.3b in the same year. That scenario assumes revenue growth of 11.0% per year and an earnings increase of about $429 million from today's level to the 2029 consensus forecast.
Uncover why Carpenter Technology's fair value indicates a 56% potential upside to its current price, which could narrow quickly.
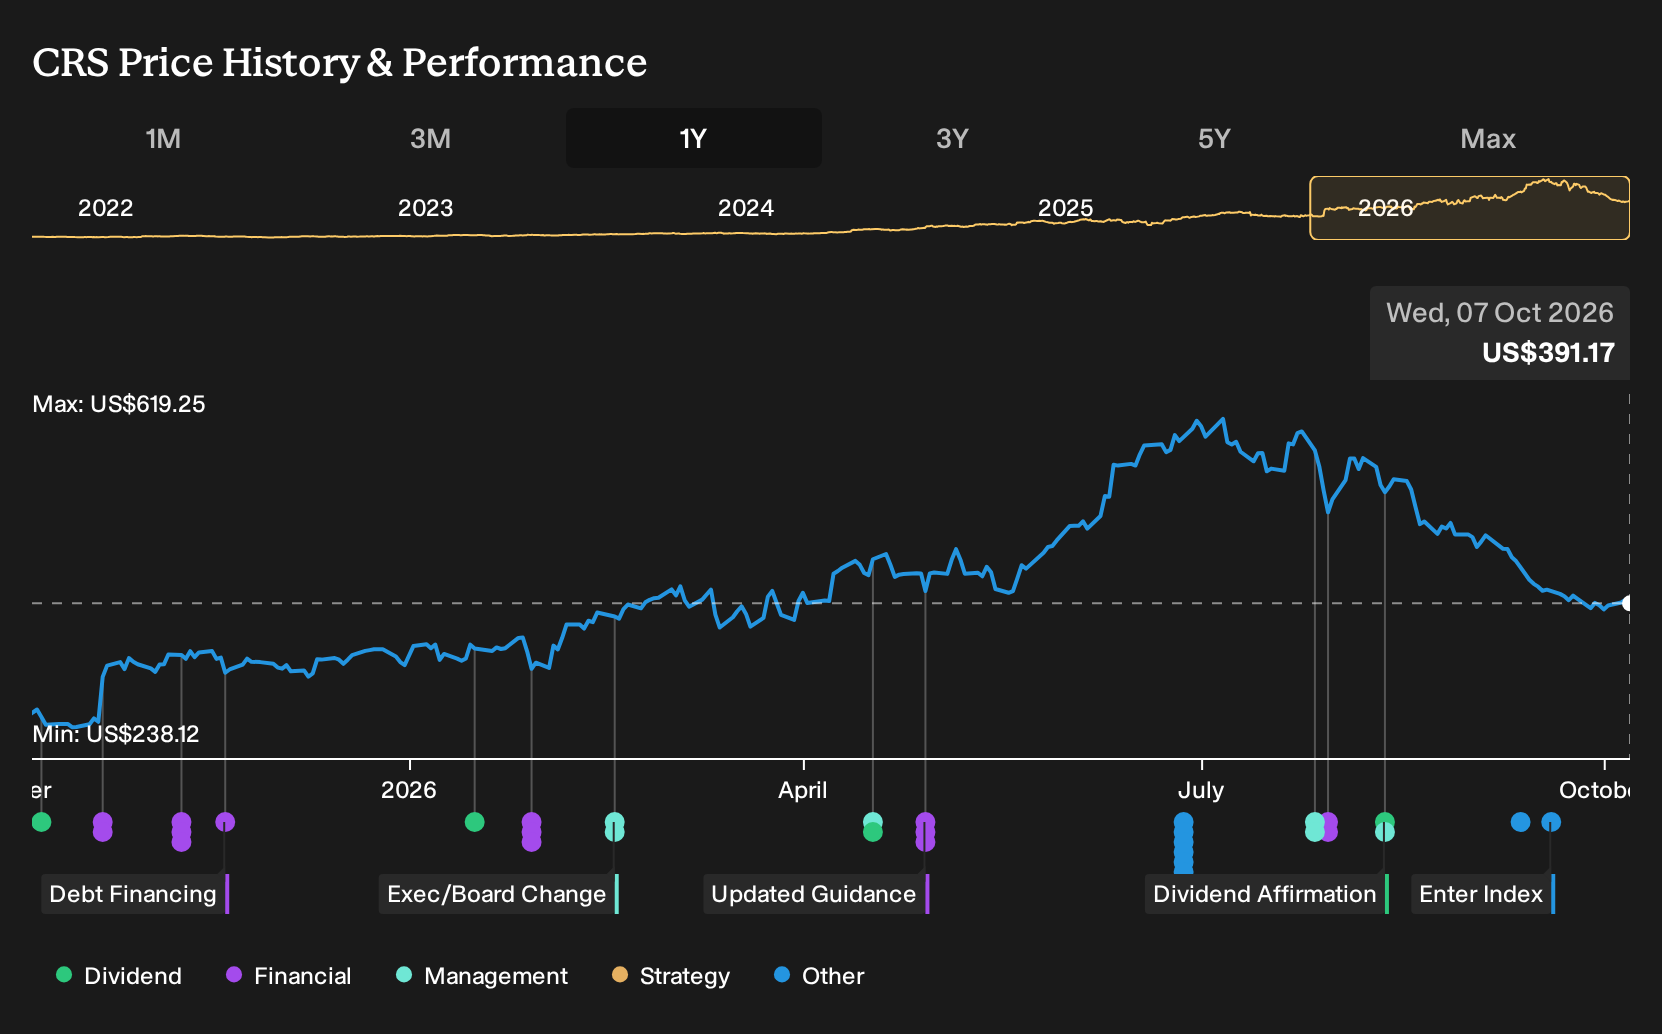
Exploring Other Perspectives
One alternate view focuses on Carpenter Technology’s brownfield expansion as the key upside catalyst rather than a major risk. The most optimistic analysts were already penciling in 12.3% annual revenue growth to about US$4.4b and earnings of US$984.6 million by 2029. Those forecasts came before this fiscal 2026 earnings news, so opinions and models may shift from here.
Explore 2 other Carpenter Technology fair value estimates, including one that indicates up to 56% potential increase from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Carpenter Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Carpenter Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carpenter Technology's overall financial health at a glance.
Looking for more investment ideas beyond Carpenter Technology?
If Carpenter Technology has sharpened your focus on quality and resilience, it can be useful to compare it with other businesses that share some of the same traits. The Simply Wall St Screener lets you quickly filter for different types of opportunities that might complement or contrast with this stock.
- If you prioritize financial strength and cleaner balance sheets, start with a list of solid balance sheet and fundamentals (25 results) that already clear basic quality hurdles.
- If value is your main lens, review 29 high quality undervalued stocks that combine stronger fundamentals with prices that screens currently flag as potentially low relative to those profiles.
- If you are hunting for future leaders that the market may not be fully focused on yet, scan 20 high quality undiscovered gems with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com