


Is Dynex Capital (DX) Undervalued As Its Share Price Slide Raises Fresh Doubts?
Dynex Capital (DX) has drawn fresh attention after its share price closed at US$10.57 on 8 October 2026. Recent declines over the past month and past 3 months have prompted closer scrutiny from income-focused investors.
For Dynex Capital, the recent slide matters more than a single trading day. The share price is down 18.06% over the past month and 24.93% year to date, while the 1 year total shareholder return is down 5.62%. Over longer horizons, the company shows a 36.07% 3 year and 14.54% 5 year total shareholder return, which points to fading short term momentum against a still positive multi year record.
Scan how Dynex Capital compares with other income-focused plays by reviewing a curated set of 8 dividend fortresses that have recently caught investor attention.
After a drop of nearly 25% this year, Dynex Capital now asks a simple question of income investors: Does the current valuation still tip the risk reward balance toward buyers, or not?
Price-to-Earnings of 6.1x: Is it justified?
On the numbers alone, Dynex Capital looks cheap, with a P/E of 6.1x at a share price of $10.57, compared with both the broader US market and its own mortgage REIT peers. That low earnings multiple raises a direct question for income investors about whether the market is discounting genuine risks or overdoing caution.
The P/E ratio compares what you pay per share with the earnings that Dynex Capital generates per share. It is essentially the price tag on each dollar of profit. For a mortgage REIT that depends on its income stream, this is a straightforward way to see how generously or cautiously the market is valuing that profit engine.
Dynex Capital is trading at a P/E of 6.1x, which is below the US market on 18x and below the US Mortgage REITs industry average of 7.8x. It also sits under an estimated fair P/E of 11.2x that our fair ratio work points to. This is a level the market could reasonably move toward if current earnings forecasts and quality hold.
Explore the SWS fair ratio for Dynex Capital.
Result: Price-to-Earnings of 6.1x (UNDERVALUED).
Still, the recent 25% year to date slide and declining annual revenue raise the risk that Dynex Capital is being priced for deeper earnings pressure ahead.
Find out about the key risks to this Dynex Capital narrative.
Another View on Dynex Capital's Value
There is a catch. Our DCF model points to a future cash flow value of $6.04 per share for Dynex Capital, which is below the current $10.57 price and indicates potential overvaluation. That kind of gap places greater emphasis on the earnings story.
Look into how the SWS DCF model arrives at its fair value.
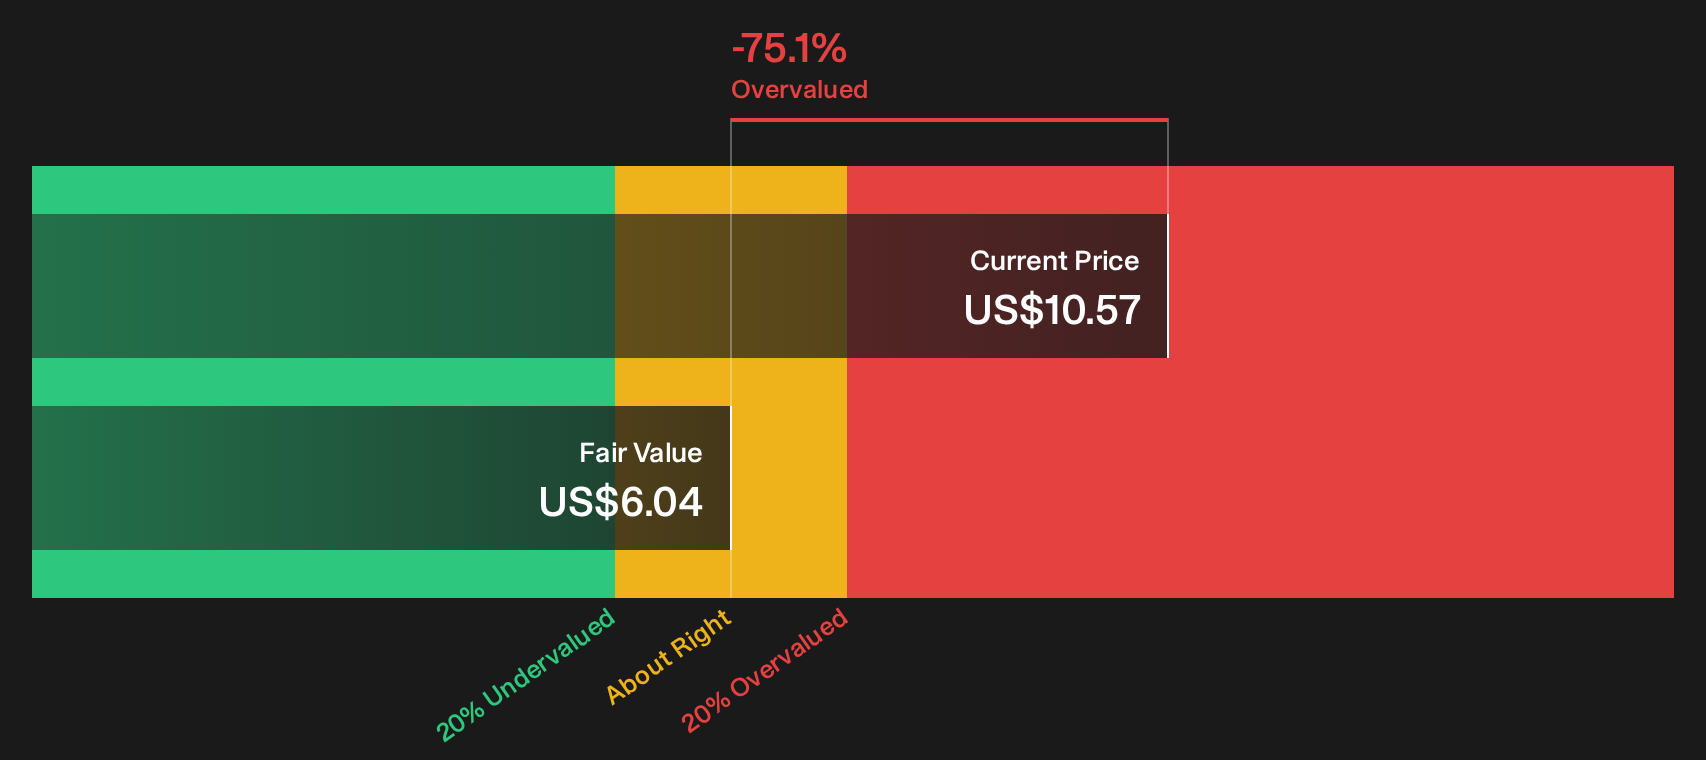
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dynex Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Views on Dynex Capital are mixed after all of that. Use the data, weigh the trade-off between risk and reward for yourself, then review the 5 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Dynex Capital?
If Dynex Capital is on your radar, broaden your options with other opportunities surfaced by the Simply Wall St Screener so you do not miss stronger fits.
- Target potential mispricing by scanning a focused set of 29 high quality undervalued stocks that pair compressed valuations with solid fundamentals.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) built to handle tougher conditions without stretching their finances.
- Get ahead of the crowd by filtering for 20 high quality undiscovered gems that already show quality but have not yet drawn widespread attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com