


Zip Co (ASX:ZIP) Lands 76ers Deal As Undervalued Narrative Stays In Play
Zip Co (ASX:ZIP) just tied its brand to the Philadelphia 76ers for the 2026-27 NBA season, putting flexible payments on center court for ticketing, merchandise, and in-arena fan spending.
Recent trading tells a mixed story for Zip Co. The A$2.12 share price comes after a 1-day share price return of 2.42% and a 7-day gain of 6.27%. However, the 30-day and year-to-date share price returns are down 8.23% and 36.72% respectively, while the 1-year total shareholder return has fallen 54.99%. At the same time, the 3-year total shareholder return is very large at around 7x, which hints that investors are reassessing both growth potential and risk as Zip Co pursues higher profile partnerships such as the 76ers deal.
Scan how other listed lenders and payment platforms with strong fundamentals are trading by reviewing our hand picked list of solid balance sheet and fundamentals (12 results) alongside Zip Co today.
Zip Co now has a high profile partnership and a mixed share price record. The real issue is whether that combination is already fully reflected in today’s A$2.12 valuation.
Most Popular Narrative: 51% Undervalued
Against the last close at A$2.12, the most followed narrative for Zip Co points to a fair value near A$4.31. This frames the current price as a steep discount and puts more weight on long term earnings power than on recent share price weakness.
Scaling distribution through partnerships and embedded finance with major merchants and platforms (such as Google Pay, Stripe, and large retailers in key verticals) is decreasing customer acquisition costs and increasing take rates, which should drive further operating leverage and higher earnings.
See why 88 investors see Zip Co as 51% undervalued.
Result: Fair Value of A$4.31 (UNDERVALUED)
Still, Zip Co’s story can change quickly if regulatory scrutiny tightens in Australia or the US or if credit losses climb as new products and customers are added.
Find out about the key risks to this Zip Co narrative.
Another View On Zip Co Valuation
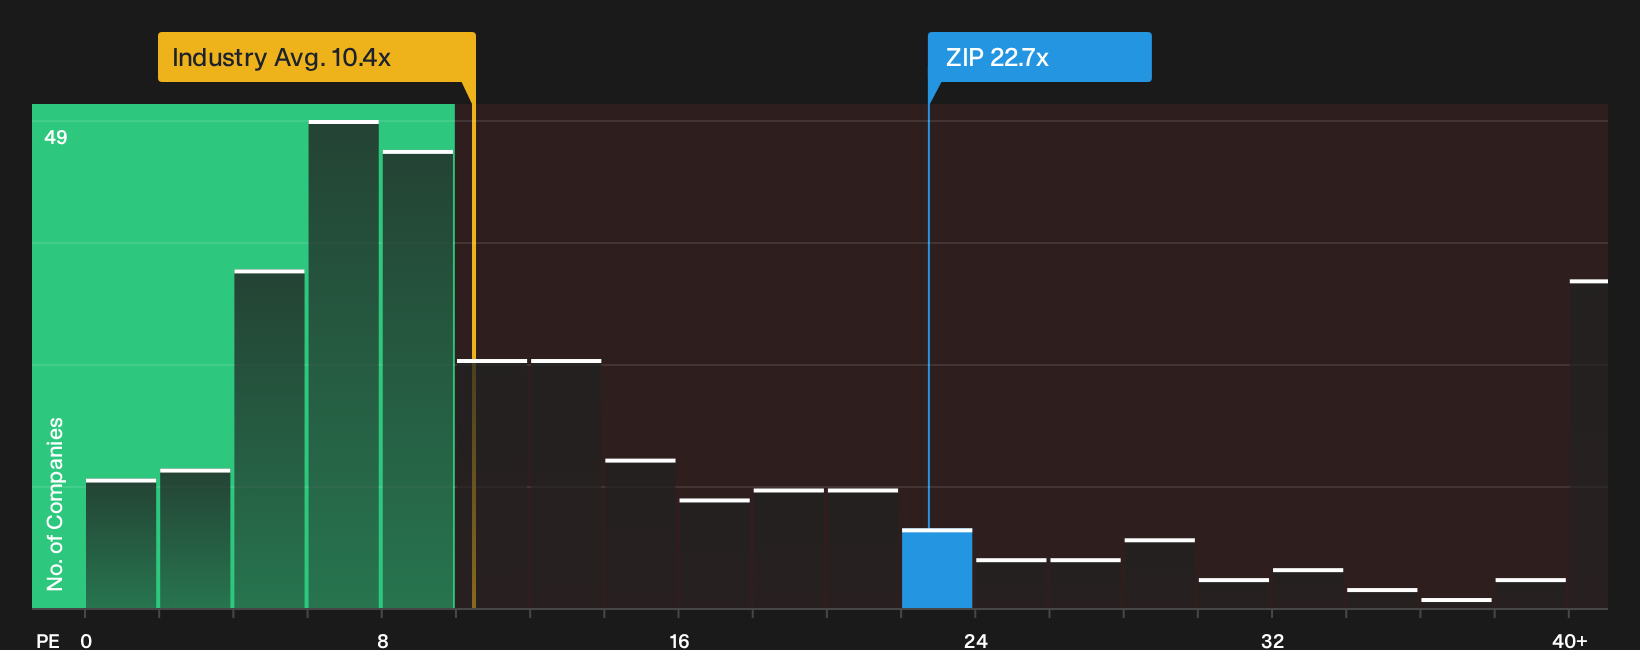
The analyst narrative and internal fair value work both flag Zip Co as undervalued around A$2.12. The P/E ratio tells a tougher story. At 22.7x earnings, the stock trades at more than double the Australian Consumer Finance industry on 10.4x and peers on 9.7x, even though the fair ratio sits higher at 28.4x.
This gap hints at potential upside if the market moves toward that fair ratio, but it also raises a simple question for investors: Is the current multiple already demanding if earnings or sentiment slip?
For a closer look at how that earnings multiple stacks up against peers and what it could mean if the market leans toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on Zip Co after the 76ers deal and valuation debate. If you want to move before sentiment flips again, review the 3 key rewards and 1 important warning sign.
Looking for more Zip Co sized ideas?
If Zip Co has you thinking about what else might be worth a closer look, do not stop at a single ticker when the market offers so many angles.
- Target higher quality potential by scanning companies that score well on value and fundamentals through the 5 high quality undervalued stocks.
- Lock in more dependable cash flows by reviewing a curated set of high yield payers with the 5 dividend fortresses.
- Protect your downside by focusing on financial strength and resilience using the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com