


Meta Platforms (META) Shares Dropped, So What Is Behind The Latest Attention?
Meta Platforms (META) just reshuffled its leadership in Southeast Asia, putting Dhruv Vohra in charge of commercial operations across six key markets where AI, messaging, and e-commerce are tightly intertwined.
Against that leadership backdrop, Meta Platforms’ recent moves around its Muse AI agent, new enterprise platform and heavy AI infrastructure spending have kept the story in focus. A 30 day share price return of 16.95% and a three year total shareholder return of 122.14% point to momentum that has slowed in the very short term, as the 1 day share price slipped 2.38%.
Scan how Meta Platforms fits into the broader AI buildout and size up other potential beneficiaries with our hand picked screener of 92 AI infrastructure stocks.
Meta Platforms now trades at a meaningful discount to both analyst targets and some intrinsic value models after a sharp run. Is that a reasonable safety margin, or is the market pricing in real AI and spending risks?
Most Popular Narrative: 29% Undervalued
Against the last close at $721.31, the most widely followed valuation story on Meta Platforms points to a fair value near $1,018.71, which implies a wide gap that the narrative tries to justify through AI driven commerce and heavy infrastructure investment.
The spending is not subtle. Meta's capital expenditure ran to $72.2 billion in 2025. Guidance for 2026 has since been lifted to a range of $125 billion to $145 billion. The company is roughly doubling its infrastructure bill in a single year. When it raised the range in April, the stock fell on the news.
See why 161 investors see Meta Platforms as 29% undervalued.
Result: Fair Value of $1,018.71 (UNDERVALUED)
Still, the Meta Platforms story can break if regulators tighten data and privacy rules, or if heavy AI and Reality Labs spending continues to pressure profitability for longer than investors expect.
Find out about the key risks to this Meta Platforms narrative.
Another View: Meta Platforms Through The Earnings Lens
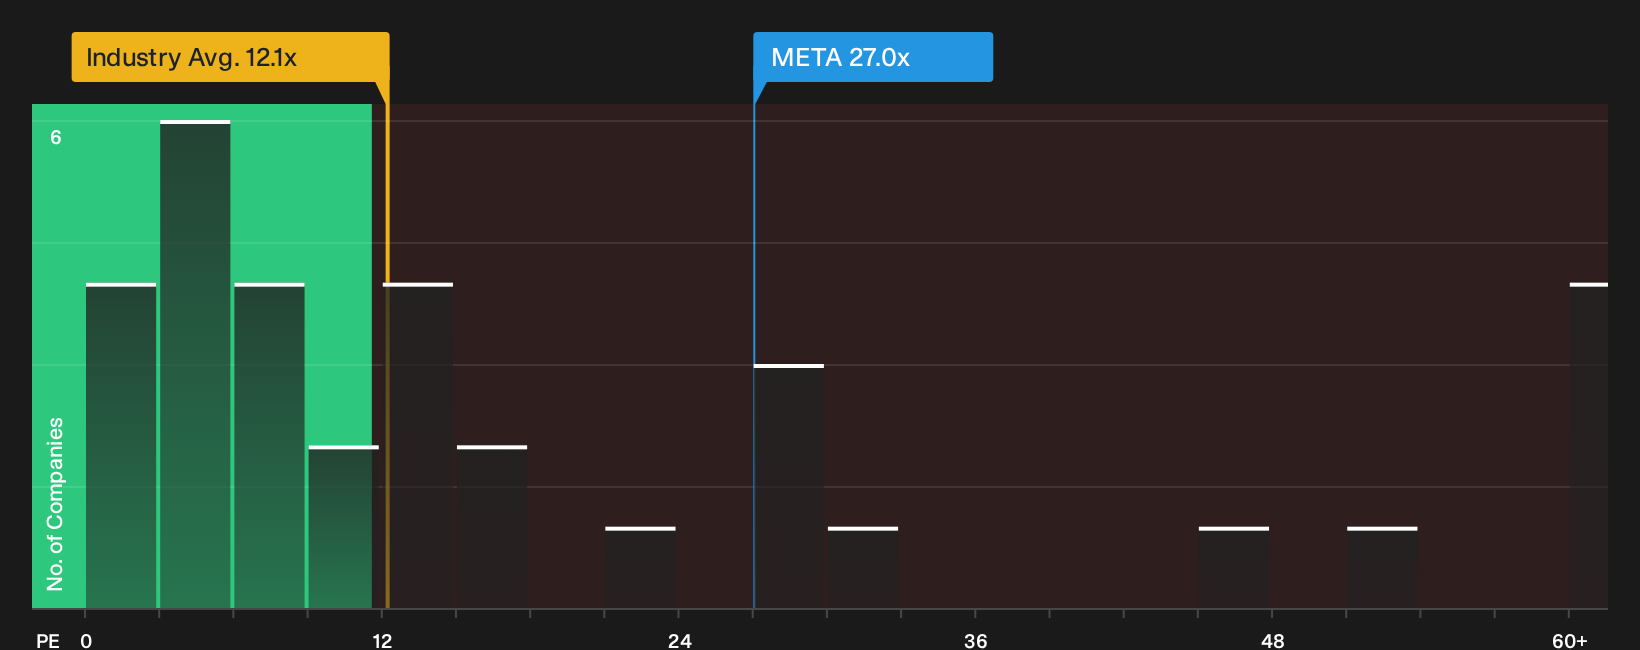
That 29% discount to a $1,018.71 fair value leans heavily on future cash flows. Look at Meta Platforms through its current P/E of 27x and the picture is less generous, with the stock slightly above a 26.6x peer average and more than double the 12.1x sector level.
Our fair ratio of 36x suggests the market could move toward a higher earnings multiple if confidence in Meta Platforms’ cash generation builds. The flip side is clear for investors. If sentiment cools, does today’s premium to peers leave less room for error than the DCF story implies, or does it just mark an entry point into a stronger franchise?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the Meta Platforms optimism in this article lines up with your own instincts about risk and reward? Move quickly, stress test the numbers yourself, and then weigh those findings against the 2 key rewards.
Looking For More Meta Platforms Investment Ideas?
If Meta Platforms has you thinking harder about opportunity and risk, do not stop here. Use the Simply Wall Street screener to pressure test fresh ideas and avoid leaving potential upside on the table.
- Target future value creators by hunting for quality companies trading below their estimated worth through 29 high quality undervalued stocks.
- Lock in potential income streams by reviewing resilient payers with the 8 dividend fortresses that screens for sturdier yields.
- Reduce sleepless nights by focusing on businesses flagged as sturdier through the 31 resilient stocks with low risk scores that filters for calmer risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com