


CTF Services (SEHK:659) Gains Focus As Annual Results And Dividend Put Valuation In Play
CTF Services (SEHK:659) drew investor attention after releasing full year results to 30 June 2026, reporting higher sales, revenue and net income, alongside a proposed final dividend and comments on future acquisition plans.
At a share price of HK$8.70, CTF Services has logged a 30 day share price return of 8.48% and a 90 day gain of 13.13%. The 1 year total shareholder return of 21.13% and 5 year total shareholder return of 146.87% point to momentum that has built over time rather than appearing only around the latest earnings and dividend news.
Scan how CTF Services fits into the wider opportunity set by comparing it with our curated 185 high quality undervalued stocks list, which pairs solid fundamentals with potential mispricing.
After a sharp run into the latest earnings and dividend news, the real choice with CTF Services is simple: step in after this move, or wait and hope for a cheaper entry as the valuation case unfolds next.
Most Popular Narrative: 19% Undervalued
CTF Services closed at HK$8.70, compared with a widely followed fair value estimate of HK$10.80 that is built on detailed earnings and cash flow forecasts using a 9.17% discount rate.
The implementation of a sustainable and progressive dividend policy, supported by stable cash flows, indicates a commitment to returning value to shareholders, which can lead to enhanced stock valuations and potential EPS growth. The synergistic collaboration with CTF Group and the focus on leveraging its brand presence in Southeast Asia is expected to create new market opportunities, drive increased customer acquisition, and enhance revenue streams from the insurance and associated wealth management business.
See why 2 investors see CTF Services as 19% undervalued.
Result: Fair Value of HK$10.80 (UNDERVALUED)
Still, pressure in the Hong Kong property construction cycle and higher gearing at CTF Services could test cash flows and reshape how investors view those analyst assumptions.
Find out about the key risks to this CTF Services narrative.
Another View On CTF Services Valuation
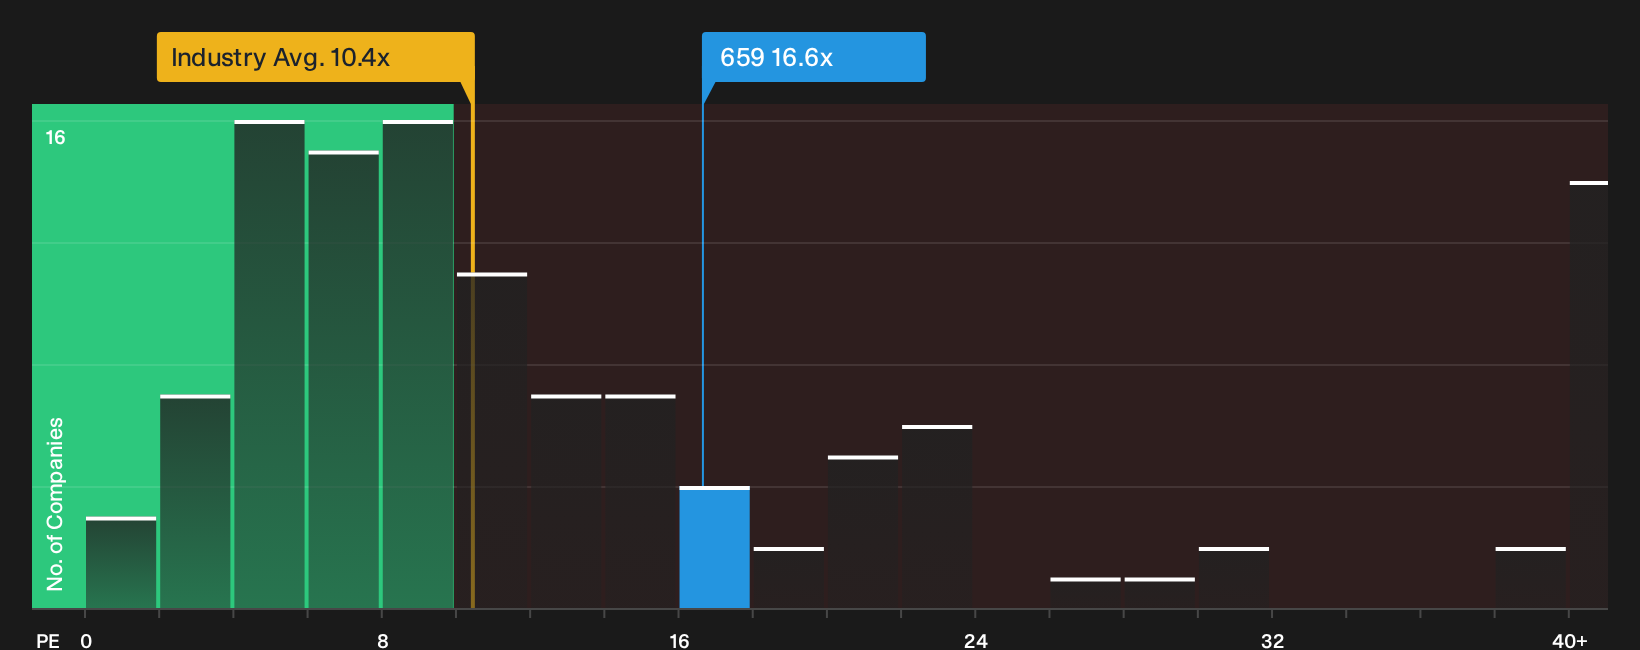
That 19% discount to fair value comes from analyst forecasts and a DCF style fair value. Yet on simple earnings maths CTF Services looks expensive. The stock trades on a P/E of 16.6x versus 9.1x for direct peers and 10.4x for the wider Asian Industrials group, while the fair ratio sits nearer 9x. Paying a much richer multiple than both the sector and that fair ratio can make any future disappointment hit harder than the DCF story suggests. Which yardstick do you trust more when expectations are already this full?
For a closer look at how those earnings and P/E gaps stack up, including where the fair ratio might matter most if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism and a few clear worries sit side by side in the CTF Services story right now, so move quickly, pull up the data, and decide where you stand based on the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond CTF Services?
If you stop at CTF Services, you risk missing other setups that could fit your goals even better, so widen the net before making your next move.
- Target potential mispricing by scanning our curated 185 high quality undervalued stocks that blends solid fundamentals with price tags that may not fully reflect them yet.
- Strengthen your defence by reviewing a list of solid balance sheet and fundamentals (207 results) that can help when markets turn choppy and weaker businesses struggle.
- Hunt for future leaders early by checking out a 619 high quality undiscovered gems that have strong numbers but limited investor attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com