


Chugoku Electric Power (TSE:9504) After Its ¥149b Loan Looks About Right At 9.5x
Chugoku Electric Power (TSE:9504) has secured a JPY 149b transition loan backed by the GX Acceleration Agency, funding nuclear safety upgrades and hydroelectric repowering tied to its 2050 carbon neutrality objective.
Recent trading has been choppy for Chugoku Electric Power, with a 30‑day share price return down 7.29% and a 7‑day share price return down 2.87%. However, the 90‑day share price return is up 7.48% and the 1‑year total shareholder return sits at 17.10%, so momentum over the past quarter looks steadier than the shorter term reactions around this latest transition loan announcement.
Scan 44 power grid technology and infrastructure stocks for other utilities pursuing grid upgrades and low carbon projects that reflect the transition story unfolding at Chugoku Electric Power.
After a sharp short term pullback but a stronger 1 year total return, Chugoku Electric Power sits at an interesting crossroads. Is most of the transition story already reflected in the share price, or is there meaningful upside left?
Price-to-Earnings of 9.5x: Is it justified?
For investors tracking Chugoku Electric Power, the current valuation story starts with earnings. At a last close of ¥998.5, the stock trades on a P/E of 9.5x, which sits below the broader JP market multiple but above the closest peer group average.
The P/E ratio compares the current share price to earnings per share and acts as a shorthand for how much investors are paying for each unit of profit. For a utility like Chugoku Electric Power, where growth forecasts are moderate and cash flows are tied to regulated and long term contracts, the P/E often reflects how confident the market is that those earnings will hold up through investment cycles such as the current GX transition loan backed upgrades.
Simply Wall St estimates a fair P/E of 11.6x for 9504, which is higher than the current 9.5x level. That suggests the present valuation sits below where the market could potentially re-rate the stock based on its own regression based fair ratio work, even though the shares look expensive against a 7.1x peer average and cheaper than the broader Asian electric utilities group at 14.1x.
Explore the SWS fair ratio for Chugoku Electric Power.
Result: Price-to-Earnings of 9.5x (ABOUT RIGHT)
Still, the GX transition loan rests on successful nuclear safety work and hydro repowering, and any policy shift or project delay could quickly challenge the current Chugoku Electric Power story.
Find out about the key risks to this Chugoku Electric Power narrative.
Another View on Chugoku Electric Power’s Value
The P/E story is only half the picture for Chugoku Electric Power. Our DCF model points to a future cash flow value of ¥856.76 per share, which sits below the current ¥998.5 price. That leaves the share price trading above this cash flow based estimate. How much weight do you give to earnings versus cash flows when they disagree?
Look into how the SWS DCF model arrives at its fair value.
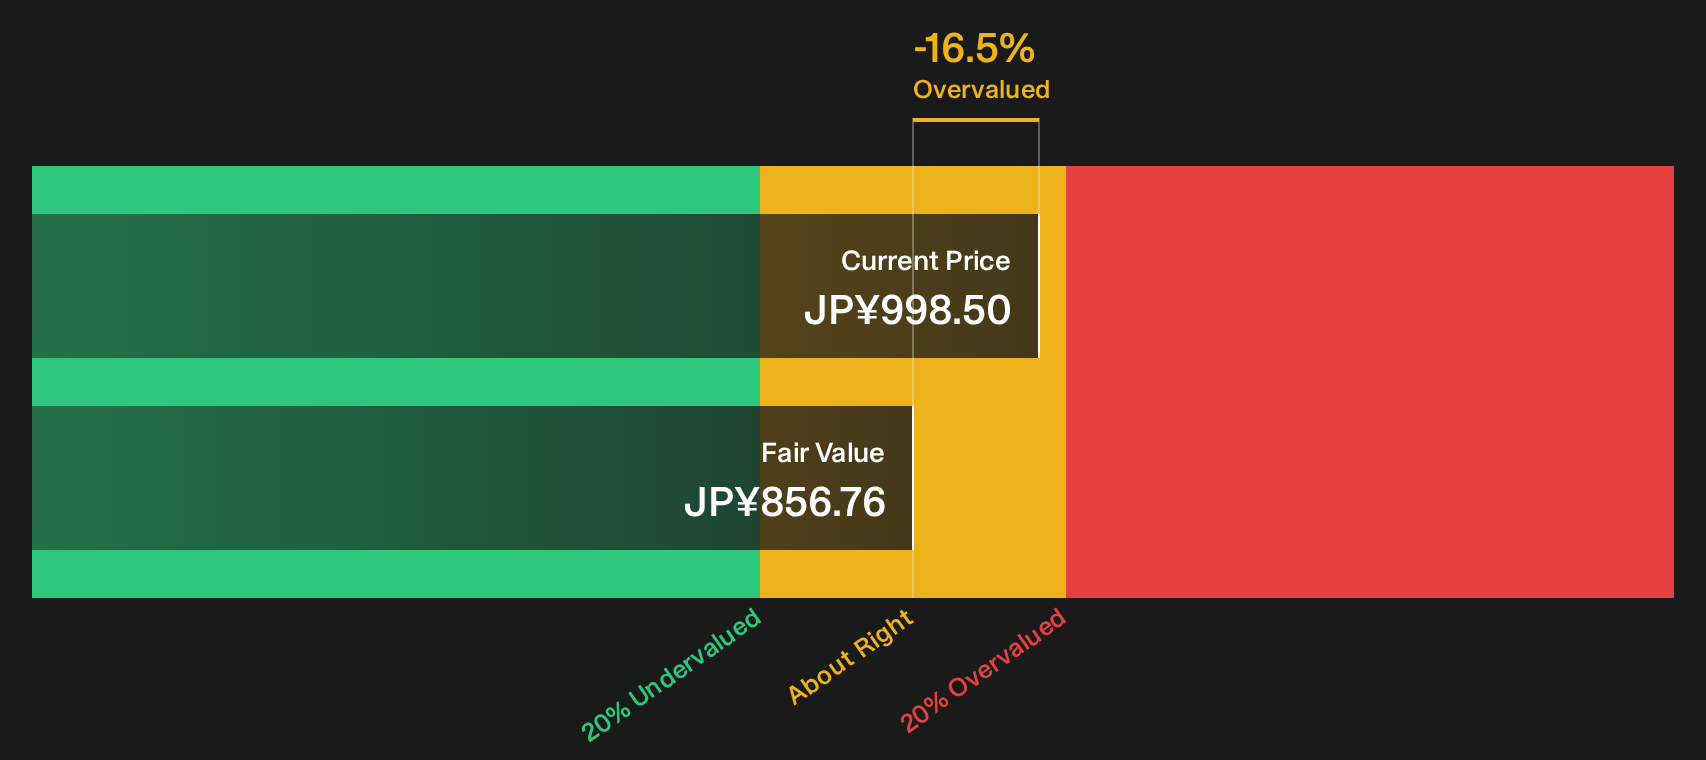
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chugoku Electric Power for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Chugoku Electric Power can feel confusing, so move quickly to review the underlying data, stress test your own assumptions, and then weigh the balance of 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Chugoku Electric Power?
If Chugoku Electric Power has you thinking more broadly about where to put fresh capital to work, use this moment to widen the opportunity set before the next move catches you off guard.
- Target resilient cash generators by scanning the 14 high quality undervalued stocks that pair solid fundamentals with prices that still look out of sync with their financial strength.
- Prioritise stability and staying power by reviewing a list of solid balance sheet and fundamentals (23 results) that can help cushion tougher market conditions.
- Get in early on less crowded stories by running through 75 high quality undiscovered gems with strong metrics that many investors are not watching closely yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com