


3 AI Stocks Trading Under 30x P E
World Bank economists now link much of East Asia’s future growth to AI related exports, which shows how central this technology has become to global trade and corporate spending plans. That focus on AI creates a window for investors who think some US listed players tied to chips, software and cloud may be priced too cautiously. This article walks through three stocks from our undervalued AI shortlist that are worth a closer look.
The three stocks below are a small sample from this AI shortlist. The full screen surfaced 44 more companies with equally detailed stories that are not covered here. To identify and analyze the highest conviction ideas across AI chips, software and cloud, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener.
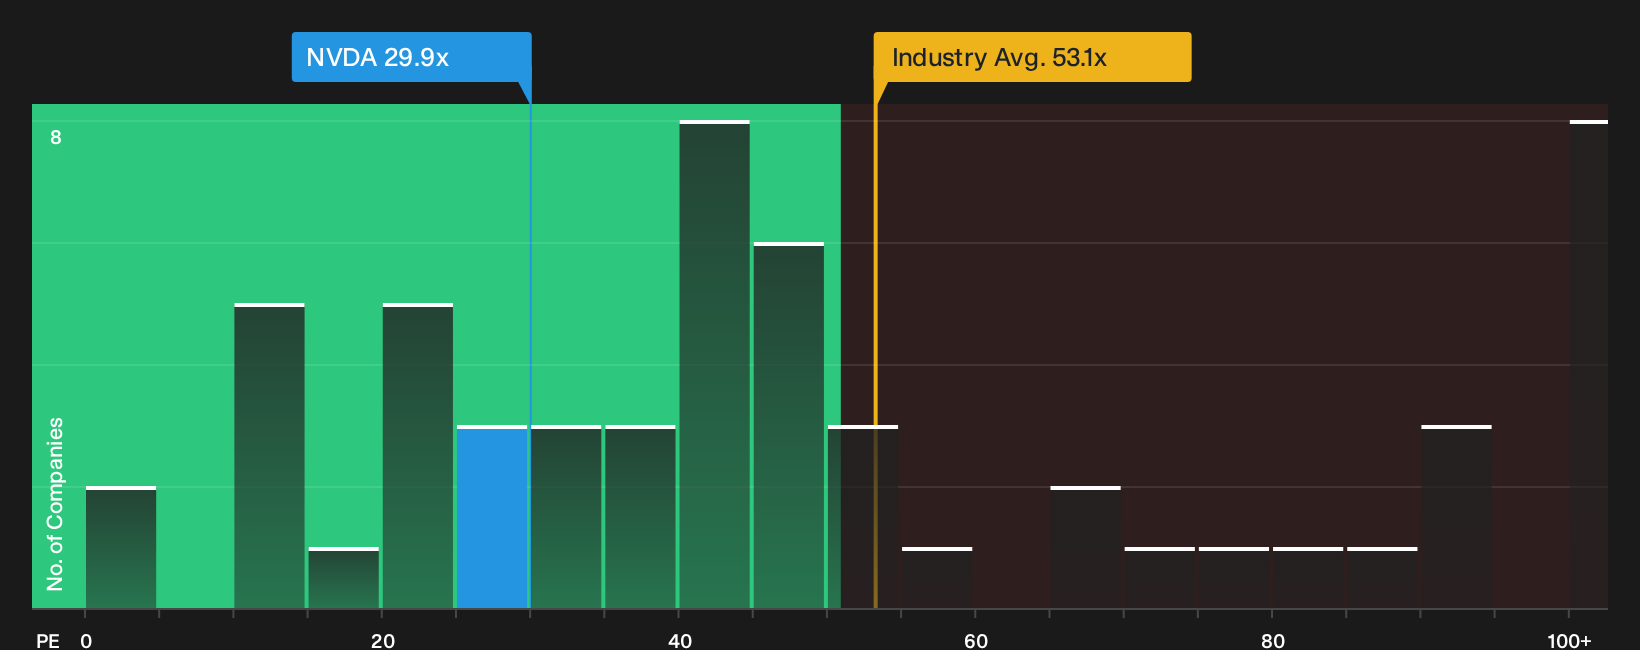
NVIDIA (NVDA)
Overview: NVIDIA is a global chip and software company whose data center GPUs and AI platforms power large language models and generative AI workloads.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, with most revenue coming from US and Taiwan customers.
Market Cap: US$5.6t
NVIDIA matters for this AI screen because its GPUs, systems and software stack are the infrastructure many ChatGPT style applications are built on.
"Uptake of an open-source, cheaper or better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
What happens to NVIDIA’s AI power if a single assumption about how tightly developers stick to its ecosystem starts to loosen?
If that grip on developers is the real swing factor, the full narrative for NVIDIA connects the dots on moat durability, pricing power and where the AI cycle could surprise next.
Broadcom (AVGO)
Overview: Broadcom supplies AI focused semiconductor networking and connectivity chips alongside infrastructure software that together support large scale data center computing.
Operations: Broadcom generates about US$59.4b from Semiconductor Solutions and US$29.7b from Infrastructure Software, with AI linked semiconductors the key theme exposure.
Market Cap: US$1.7t
For investors tracking the AI build out, Broadcom matters because its high speed networking chips and connectivity hardware help move the torrents of data that large language models like ChatGPT rely on.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
The real swing factor is what happens if one concentrated funding and customer relationship reshapes how those AI economics flow through Broadcom’s margins.
That customer concentration risk is exactly why it is worth reading the full narrative for Broadcom, which explains in detail how Broadcom’s AI momentum and cash generation could become less dependent on any single buyer.

Alphabet (GOOGL)
Overview: Alphabet runs Google Search, YouTube and Android while Google Cloud sells AI and Gemini tools that power enterprise applications.
Operations: Alphabet generates about US$367.1b from Google Services, US$77.6b from Google Cloud and US$1.5b from Other Bets, before hedging effects.
Market Cap: US$4,223.6b
Alphabet matters for this AI shortlist because Google Cloud’s Vertex AI and Gemini models give enterprises the building blocks for ChatGPT style tools, tying core infrastructure, models and productivity apps together in one place.
"Google Cloud, which crossed the $20 billion quarterly revenue threshold for the first time, saw revenue of $20.03 billion (+63% YoY) and operating income of $6.6 billion as demand for enterprise AI infrastructure fueled a near-doubling of backlog to over $460 billion."
What happens to Alphabet’s cash generation if one assumption about how quickly that AI backlog converts into recurring usage quietly shifts?
If that timing risk is on your mind, the full narrative for Alphabet shows how Alphabet’s AI backlog, margins and cash generation could be decoupling from old search-only assumptions.

Curious To Explore Fresh Alternatives?
Markets move fast and the next breakout themes rarely wait around. Scan fresh ideas with real momentum while they are still under the radar for now and consider your options promptly.
- Target steady income potential from companies prioritizing reliable cash returns with the 7 dividend fortresses before yields are affected by increased attention.
- Look for potential category leaders that may be overlooked using the curated 19 high quality undiscovered gems before broader interest changes valuations.
- Evaluate opportunities linked to electrification and infrastructure demand by tracking producers inside the 16 top copper producer stocks while the strongest balance sheets may still be conservatively valued.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com