


Cheniere Energy (LNG) Files Gillis Header Update As Valuation Debate Stays In Focus
Cheniere Energy (LNG) just filed an environmental report with US regulators on its Gillis Header Project in Louisiana, updating progress on compressor station extensions and site preparation work.
The Gillis Header work lands at a time when Cheniere Energy’s momentum has cooled in the very short term but remains strong overall, with a 1-day share price return of 1.84% and year to date share price return of 38.99%, alongside a 5-year total shareholder return of 184.34%. This suggests that investors have been willing to reward the LNG build out while still reassessing near term risks.
Scan beyond Cheniere Energy and identify additional LNG infrastructure players that combine momentum and scale in a curated set of 39 power grid technology and infrastructure stocks
Cheniere Energy now trades close to recent highs, while analyst targets sit meaningfully above and some intrinsic models point lower. Where does a fair entry price really fall across that spread?
Most Popular Narrative: 11% Undervalued
Cheniere Energy closed at $274.93 against a widely followed fair value of $309.95, so the narrative leans toward a discount while still hinging on execution and risk control.
The highly contracted nature of Cheniere Energy’s LNG platform through 2030 and into 2035, combined with an investment grade credit profile and a capital return program that targets dividend growth and share repurchases, is set to keep a large portion of future EBITDA and distributable cash flow tied to recurring, contracted revenue.
See why 69 investors see Cheniere Energy as 11% undervalued.
Result: Fair Value of $309.95 (UNDERVALUED)
Still, Cheniere Energy’s exposure to large LNG-linked derivative swings and the federal alternative fuel tax credit investigation could quickly challenge that undervaluation story.
Find out about the key risks to this Cheniere Energy narrative.
Another View on Cheniere Energy’s Valuation
The earlier fair value of $309.95 leans on earnings forecasts and contract strength. A second lens tells a different story. Our DCF model, which focuses on future cash flows, values Cheniere Energy at $128.42, so the current $274.93 level screens as overvalued on this method. Which cash flow path do you trust more?
Look into how the Look into how the SWS DCF model arrives at its fair value.
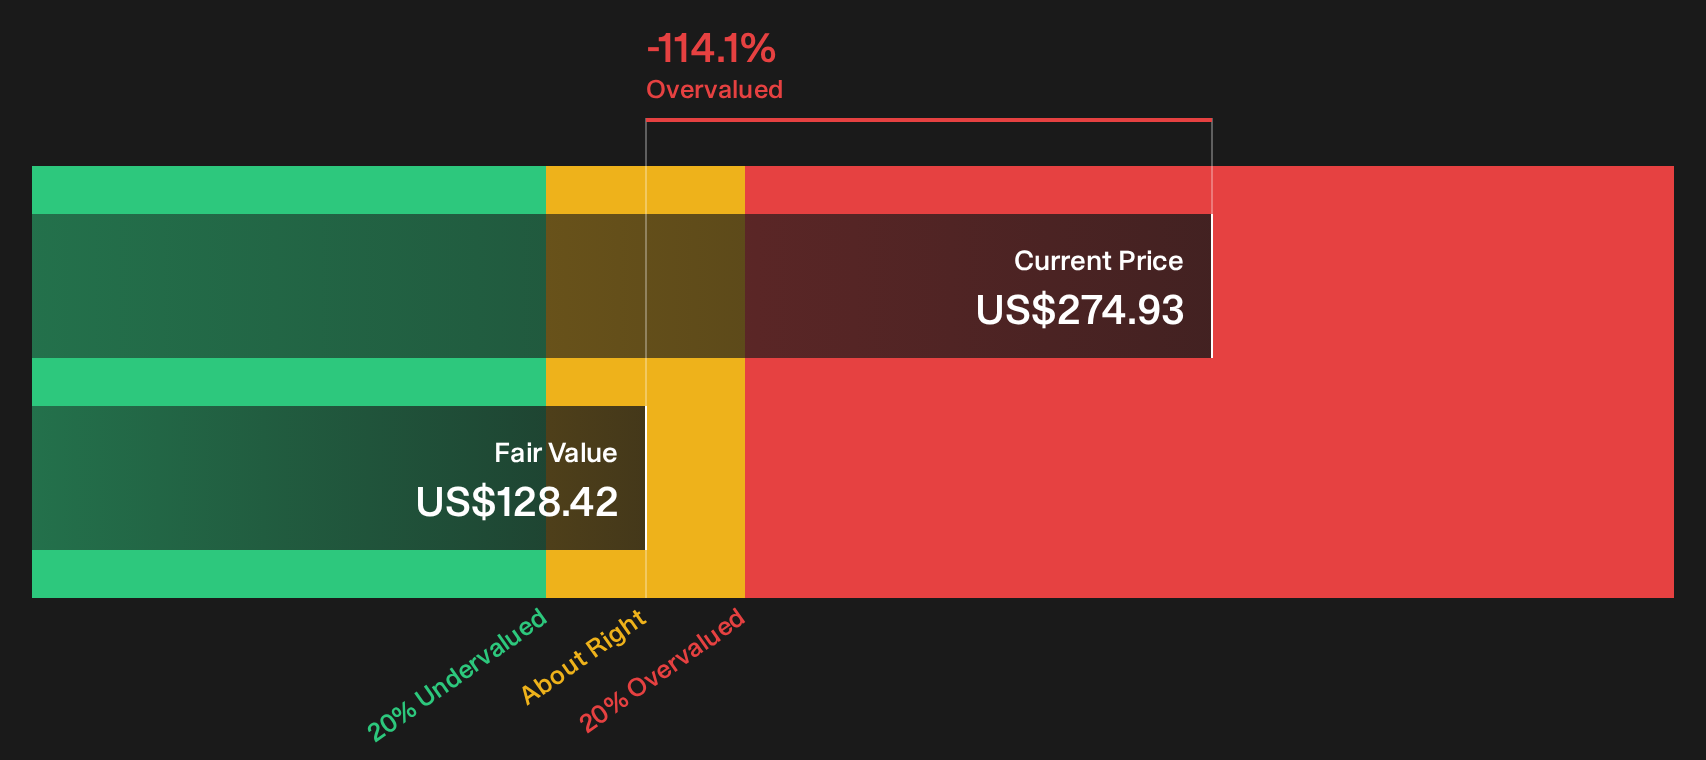
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cheniere Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Cheniere Energy’s value and risk profile can feel messy, so move quickly, test the numbers yourself and weigh up the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Cheniere Energy?
If Cheniere Energy has your attention, do not stop here. Use the Simply Wall St screener to pressure test your thesis and surface fresh opportunities.
- Spot potential bargains early by scanning a curated pool of 19 high quality undiscovered gems that pair quality fundamentals with limited market attention.
- Build a sturdier core portfolio by focusing on businesses with cleaner finances using a targeted list of solid balance sheet and fundamentals (25 results).
- Strengthen capital preservation by concentrating on companies that score well on stability metrics with a focused 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com