


Does Rapid Heart Attack Test Change The Bull Case For bioMérieux (ENXTPA:BIM)?
- bioMérieux has launched SPINCHIP®, a compact point-of-care immunoassay platform, with its first CE-marked high-sensitivity cardiac troponin I test delivering results in about 10 minutes from a single drop of blood for adult patients with suspected acute myocardial infarction.
- The SPINCHIP® rollout in Europe is directly tied to bioMérieux’s GO•28 plan, using the SpinChip Diagnostics acquisition to extend testing beyond central labs and deepen its presence inside emergency care workflows.
- We will examine how bioMérieux’s investment narrative is reshaped by SPINCHIP® bringing lab-grade cardiac troponin testing directly into emergency settings.
Scan other diagnostics players that could echo bioMérieux’s point of care push by focusing on financially resilient healthcare stocks in our curated list of solid balance sheet and fundamentals (207 results)
bioMérieux Investment Narrative Recap
To own bioMérieux, you need to believe the diagnostics group can keep turning its broad infectious disease franchise and strong R&D spend into steady new product rollouts, while tightening profitability through its GO.Simple initiatives. The SPINCHIP launch fits that story, but on its own it does not rewrite the near term earnings profile.
In the shorter term, the key swing factor still looks like how BIOFIRE and SPOTFIRE volumes hold up as pandemic era contracts roll off and U.S. competition nudges pricing. The main risk remains contract churn and margin pressure, not whether SPINCHIP scales quickly from day one.
The SPINCHIP platform itself is tightly linked to the GO•28 plan and bioMérieux’s push to move testing closer to emergency care. It gives the group another way to embed systems directly into acute workflows, alongside BIOFIRE and SPOTFIRE, and it supports the broader goal of driving higher utilization across installed instruments.
For catalysts, that matters because management has been leaning on cross selling, new panels, and high margin assays to support earnings growth. SPINCHIP can contribute to that mix if adoption builds, but investors still need to watch known pressure points, including U.S. reimbursement dynamics, foreign exchange headwinds in 2025, and contract renewals on existing BIOFIRE placements.
bioMérieux Consensus Expectations Behind SPINCHIP
Analysts are effectively asking investors to view SPINCHIP as one contributor inside a broader bioMérieux story that already incorporates steady expansion. The current consensus points to revenue growing by 5.4% a year over the next three years, supported by broader test menus and deeper penetration of hospital workflows rather than a single blockbuster launch.
On profitability, earnings today are cited at €462.6 million with a margin of 11.6%. Forecasts move that to €583.2 million by 2029 and a margin of 12.5%. That represents an earnings increase of about €120.6 million from the current base, with some analysts modelling an upper case of €646.4 million if execution on panels, automation and cost discipline is stronger.
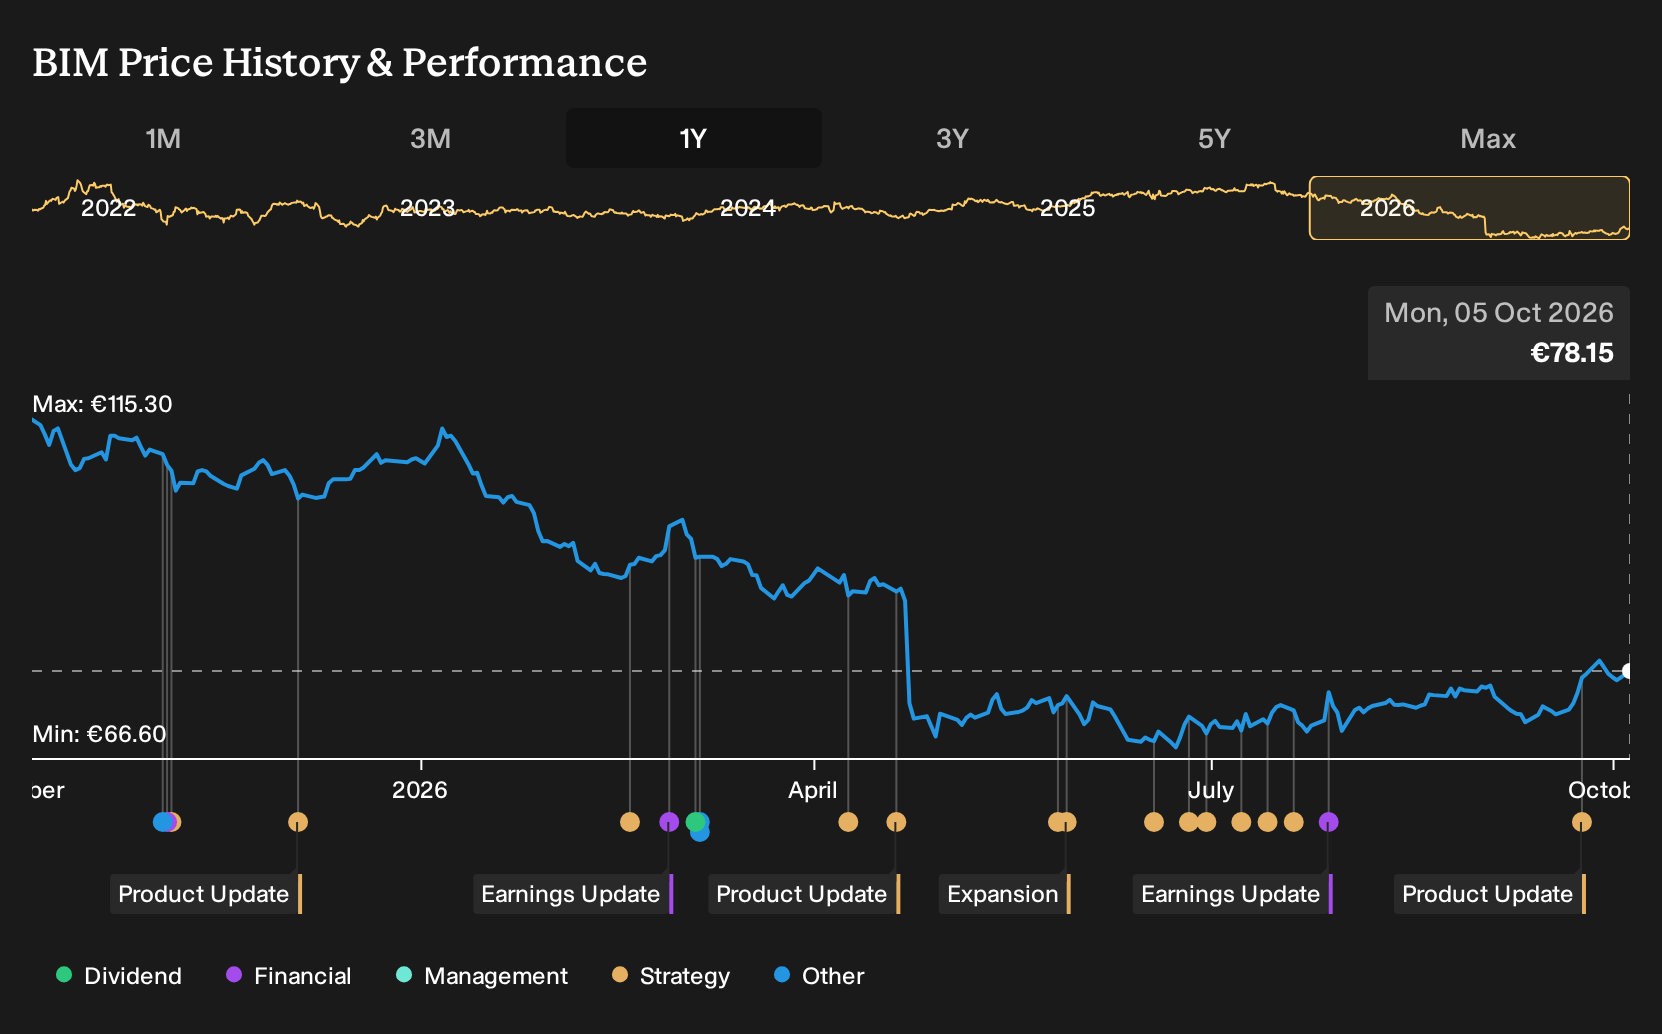
The valuation bridge that links those operating assumptions to today’s share price is described as fairly tight. For the current analyst price target of €79.04 to align with a spot price of €72.85, the group would need to reach about €4.7 billion of revenue and €583.2 million of earnings by 2029 and trade on a P/E of 19.3x. That multiple would sit slightly below the 21.4x cited for the wider GB medical equipment peer group, so the expectation is for bioMérieux to maintain a solid position inside its sector rather than command a premium rating.
bioMérieux's narrative references €4.7 billion of revenue and €583.2 million of earnings by 2029. This is tied to 5.4% yearly revenue growth and an earnings increase of about €120.6 million from €462.6 million today.
Uncover why bioMérieux's fair value indicates that bioMérieux is in line with its current price.
Exploring Other Perspectives
The biggest swing factor in the more cautious bioMérieux narrative is slower revenue progress. The most bearish analysts were pencilling in 4.0% yearly top line growth to about €4.5b and earnings of €547.7 million by 2029. That is a noticeably softer setup than consensus, and it did not yet reflect SPINCHIP, so opinions could shift as you compare these scenarios.
Explore 2 other bioMérieux fair value estimates, including one that suggests it could be worth just €79.04.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your bioMérieux research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for bioMérieux. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate bioMérieux's overall financial health at a glance.
Looking for more investment ideas beyond bioMérieux?
If the SPINCHIP launch has you rethinking where bioMérieux sits in your portfolio, it can help to line it up against other listed healthcare and non healthcare opportunities using a consistent framework.
- For investors who care most about balance sheet strength and durable fundamentals, start with this curated list of solid balance sheet and fundamentals (207 results) and see which businesses meet that quality bar.
- If value is your priority, compare bioMérieux with a focused group of attractively priced companies by reviewing the 186 high quality undervalued stocks that match your risk and return preferences.
- Income focused readers who want yield and resilience together can scan a hand picked pool of 162 dividend fortresses and judge whether any fit better alongside or instead of bioMérieux in their holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com