


How ETF Share Class Filing At BlackRock (BLK) Has Changed Its Investment Story
- In late September 2026, BlackRock filed initial SEC registration statements to add ETF share classes to five existing active mutual funds. This move offers an exchange-traded access point to the same underlying portfolios without requiring current fund holders to move their capital.
- This ETF share class push leans on the iShares platform and highlights how BlackRock is trying to manage product costs, distribution reach, and client preferences within its core active income and equity franchises.
- We will now explore how BlackRock's decision to add ETF share classes to key active funds could influence its broader investment narrative.
Scan how BlackRock is repositioning around ETFs, then extend that research to other potential movers in income and equity by reviewing our curated list of 31 high quality undervalued stocks.
BlackRock Investment Narrative Recap
To own BlackRock, you need to believe its scale in ETFs, active funds, technology and alternatives can offset fee pressure and higher costs over time. The new ETF share classes mainly reinforce that story by giving investors another access point to core income and equity strategies, without altering the underlying portfolios.
The biggest near term swing factor remains whether BlackRock can grow earnings faster than rising compensation, tech and integration expenses. Fee compression and softer performance fees still sit on the other side of that equation. The ETF filings look incremental rather than a major catalyst or new risk in the next few quarters.
The ETF share class registrations for five active mutual funds feel most relevant here. They directly touch BlackRock’s core challenge. The firm needs to keep attracting flows into both income and equity while clients increasingly prefer lower cost, exchange traded vehicles that can weigh on its effective fee rate.
If these products come to market, execution will hinge on building liquidity, managing spreads and communicating how tax treatment and trading behavior differ from the mutual fund sleeves. Any stumble on operations, pricing or education could undercut the intended benefit at a time when margins and net flows already matter a lot for sentiment.
BlackRock's narrative projects US$36.2b revenue and US$10.8b earnings by 2029. That profile assumes 9.9% yearly revenue growth and an earnings increase of about US$4.2b from the current US$6.6b level.
Discover how BlackRock's fair value indicates a 25% potential upside to its current price that may not last much longer.
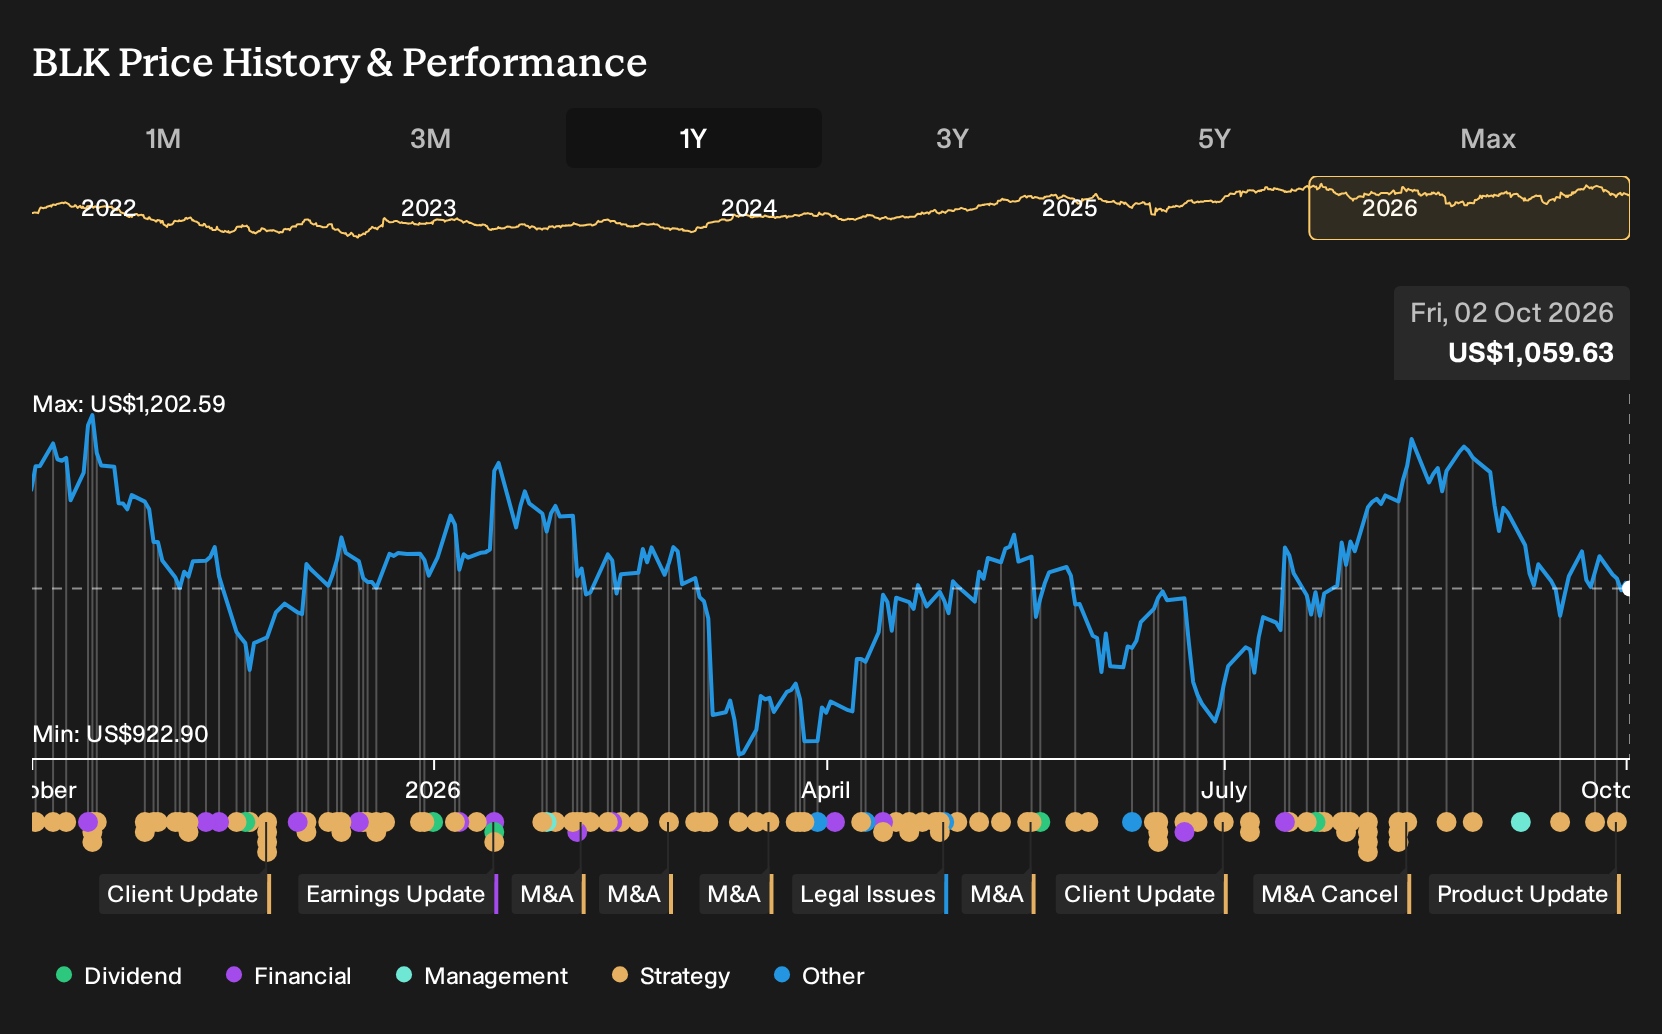
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community cluster between US$1,148.71 and US$1,323.31, which already shows how far opinions on BlackRock can stretch. Those views do not yet reflect the new ETF share class filings or the potential APAC data center deal. Use them as starting points and explore several contrasting viewpoints before deciding how the story fits your own expectations.
Explore 4 other BlackRock fair value estimates, including one that suggests up to 25% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BlackRock research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BlackRock. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BlackRock's overall financial health at a glance.
Looking For More Investment Ideas Beyond BlackRock?
Once you have a handle on BlackRock, it can help to widen the lens and compare its setup with other opportunities that share similar qualities or risk profiles. The Simply Wall St Screener lets you do that quickly by surfacing focused groups of companies built around fundamentals, not hype.
- If you want income that aims to be more durable, start with a shortlist of higher yielding payers by reviewing our hand picked 7 dividend fortresses.
- For investors who care most about resilient balance sheets and cleaner financial footing, scan the list of solid balance sheet and fundamentals (25 results) to see which businesses clear those hurdles.
- If you are hunting for opportunities that the market may not be paying full attention to yet, check out a curated group of potential under the radar ideas through our 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com