


How Investors Are Reacting To Northern Trust (NTRS) CFO Retirement Plan
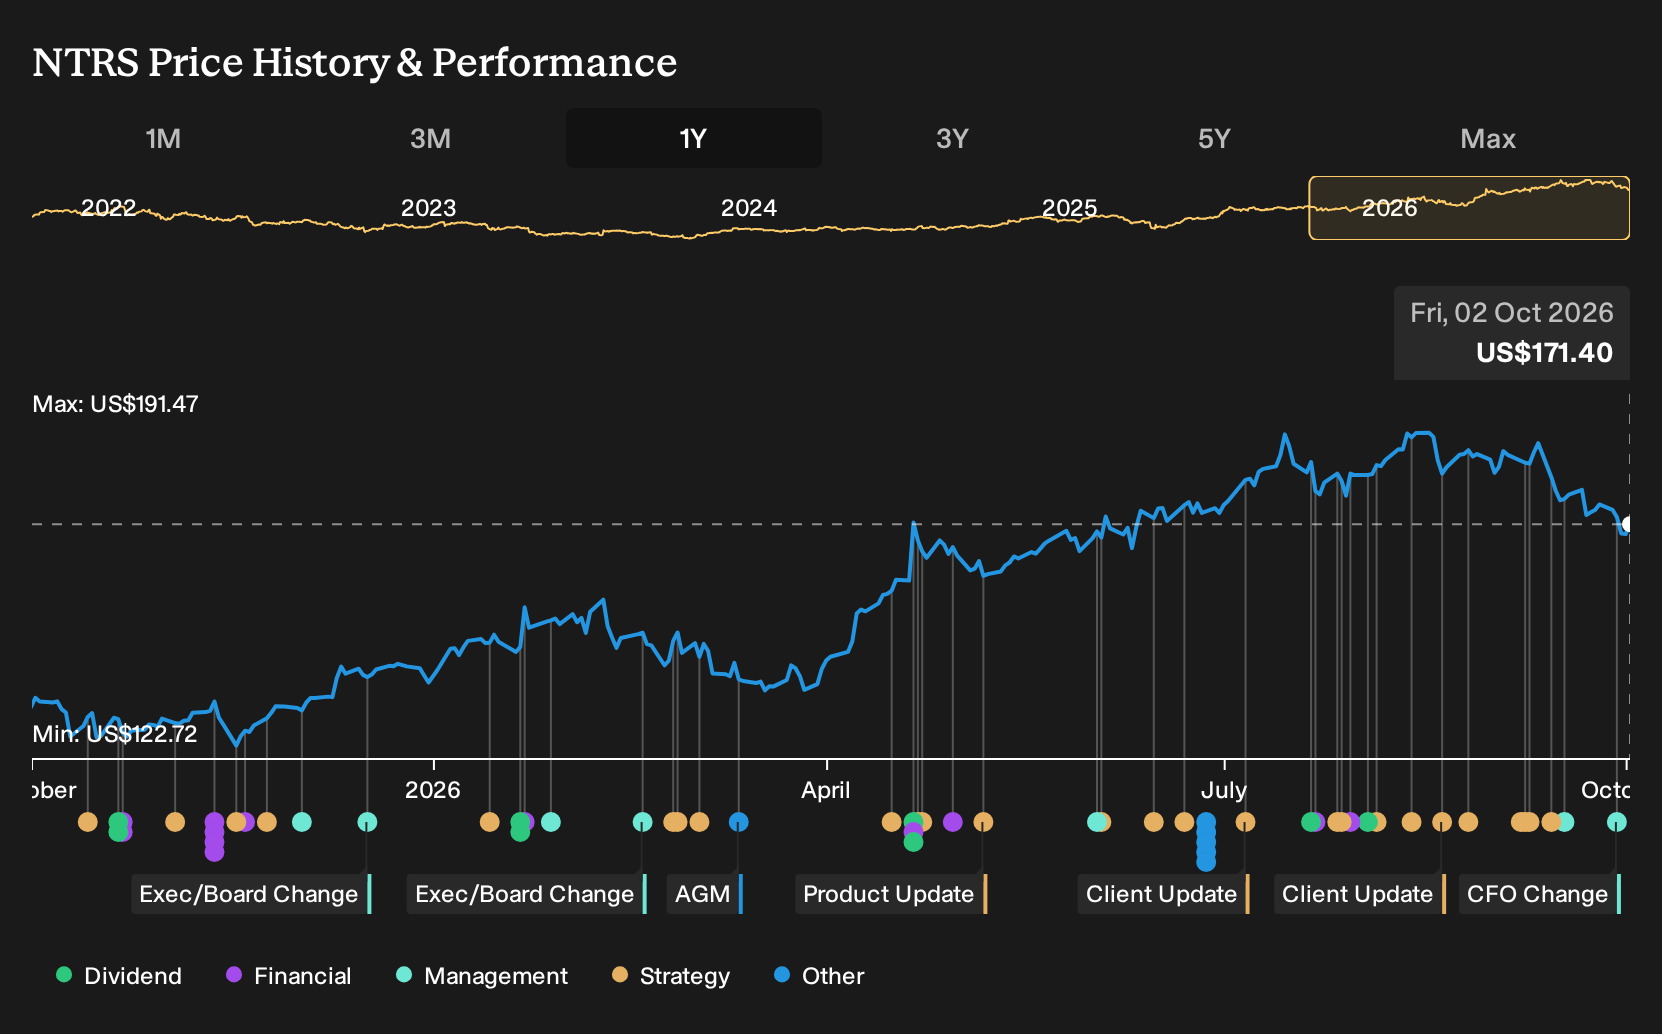
- Northern Trust announced that long serving Chief Financial Officer Dave W. Fox, Jr. plans to retire around March 31, 2027, with a structured transition and a broad internal and external search underway for his successor.
- Fox’s planned involvement through the first quarter of 2027 provides continuity for Northern Trust’s financial reporting, regulatory engagement, investor relations and capital allocation decisions during the selection process.
- We will now look at how Northern Trust's CFO retirement and transition process could influence the existing investment narrative that investors follow.
Scan how Northern Trust’s succession news compares with other financial institutions handling leadership shifts by reviewing the curated 31 resilient stocks with low risk scores that aim to pair stable balance sheets with measured risk profiles.
Northern Trust Investment Narrative Recap
Northern Trust appeals most to investors who believe its wealth management, asset servicing and capital markets franchises can continue to generate fee based income while expenses remain under tight control. The CFO transition news appears orderly and extends into 2027, so it does not materially change the near term focus on revenue growth, operating leverage and productivity gains.
The key short term swing factor still lies in execution on the earnings efficiency cycle, including technology and AI projects and pricing in liquidity products. The biggest risk remains cost pressure from talent competition and complex projects, where any misstep could erode the 24% net margin that has supported the recent improvement in profitability.
Recent guidance calling for 9% to 10% total revenue growth in 2026, with about 400 basis points of positive operating leverage, is the most relevant backdrop for assessing this CFO retirement. Investors are watching whether Northern Trust can continue to translate that mix of fee growth, higher value trading solutions and One Northern Trust cross selling into consistent margin gains.
With the outgoing CFO expected to stay in place through the first quarter of 2027, that revenue and efficiency plan remains in the same hands that helped shape it, while the board runs a broad search. For you, the focus is less on the headline change and more on whether the next finance leader can maintain discipline on technology spending, talent costs and capital allocation without disrupting the current trajectory.
Northern Trust's narrative projects US$10.1b revenue and US$2.5b earnings by 2029. This aligns with analyst assumptions of 3.6% yearly revenue growth and an earnings increase of about US$300m from current earnings of US$2.2b.
Uncover why Northern Trust's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$184.27 and US$187.53, which shows how closely some private investors view Northern Trust right now. Your own view might shift once you factor in CFO succession risk, compensation pressure, and the scale of current AI and technology spending plans.
Explore another Northern Trust fair value estimate, including one that suggests up to 9% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Northern Trust research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Northern Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Trust's overall financial health at a glance.
Looking for more Northern Trust sized ideas?
If Northern Trust sits at the center of your watchlist, it can still pay to widen the net and compare it with other companies that share some of the qualities you care about most. The Simply Wall St Screener lets you filter for the traits that matter to you, then track how those businesses measure up over time.
- For investors who want income to feel more predictable, start with steady cash generators offering elevated yields through the 7 dividend fortresses.
- If resilience and balance sheet strength are at the top of your checklist, sort for companies with low leverage and robust fundamentals using the list of solid balance sheet and fundamentals (25 results).
- When you want to get ahead of the crowd, you can scan for underfollowed businesses with strong financial profiles through the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com