


Is Brookfield Infrastructure Partners (BIP) Undervalued After Its Dividend Yield And 2026 Earnings Outlook?
Event-driven focus on Brookfield Infrastructure Partners
Brookfield Infrastructure Partners (NYSE:BIP) is drawing attention after its recent income profile update, featuring a US$0.46 quarterly distribution that equates to a 4.98% yield, alongside expectations for higher earnings in 2026.
Recent trading has been mixed for Brookfield Infrastructure Partners, with the share price up 2.04% over the last day and 4.82% over the past week. It is slightly down 1.64% across 30 days and 0.92% over 90 days, while total shareholder returns of 11.43% over one year and 52.58% over three years suggest longer term momentum has been much stronger than the shorter term price action.
Scan a curated set of income-focused infrastructure stocks with reliable balance sheets by checking out the 7 dividend fortresses alongside Brookfield Infrastructure Partners' latest distribution move.
Brookfield Infrastructure Partners now offers a near 5% yield, a long history of rising payouts, and a share price that has only inched higher recently. Do those ingredients still tilt the risk reward toward buyers at today’s level?
Most Popular Narrative: 23% Undervalued
On the most followed narrative, Brookfield Infrastructure Partners screens as undervalued, with a fair value of $47.10 against a last close of $36.52, which puts fresh attention on what is driving that gap.
A high proportion of inflation linked and regulated or contracted cash flows in utilities, transport and midstream, which has supported FFO growth alongside 6 to 9% organic expansion and a 6% increase in the 2026 distribution, provides a base for future earnings and margin resilience even as new AI projects are added.
See why 36 investors see Brookfield Infrastructure Partners as 22% undervalued.
Result: Fair Value of $47.10 (UNDERVALUED)
Still, Brookfield Infrastructure Partners carries real pressure points, including political pushback on AI data center projects and the risk that AI power contracts earn thinner margins than expected.
Find out about the key risks to this Brookfield Infrastructure Partners narrative.
Another View: Brookfield Infrastructure Partners Looks Expensive On Earnings
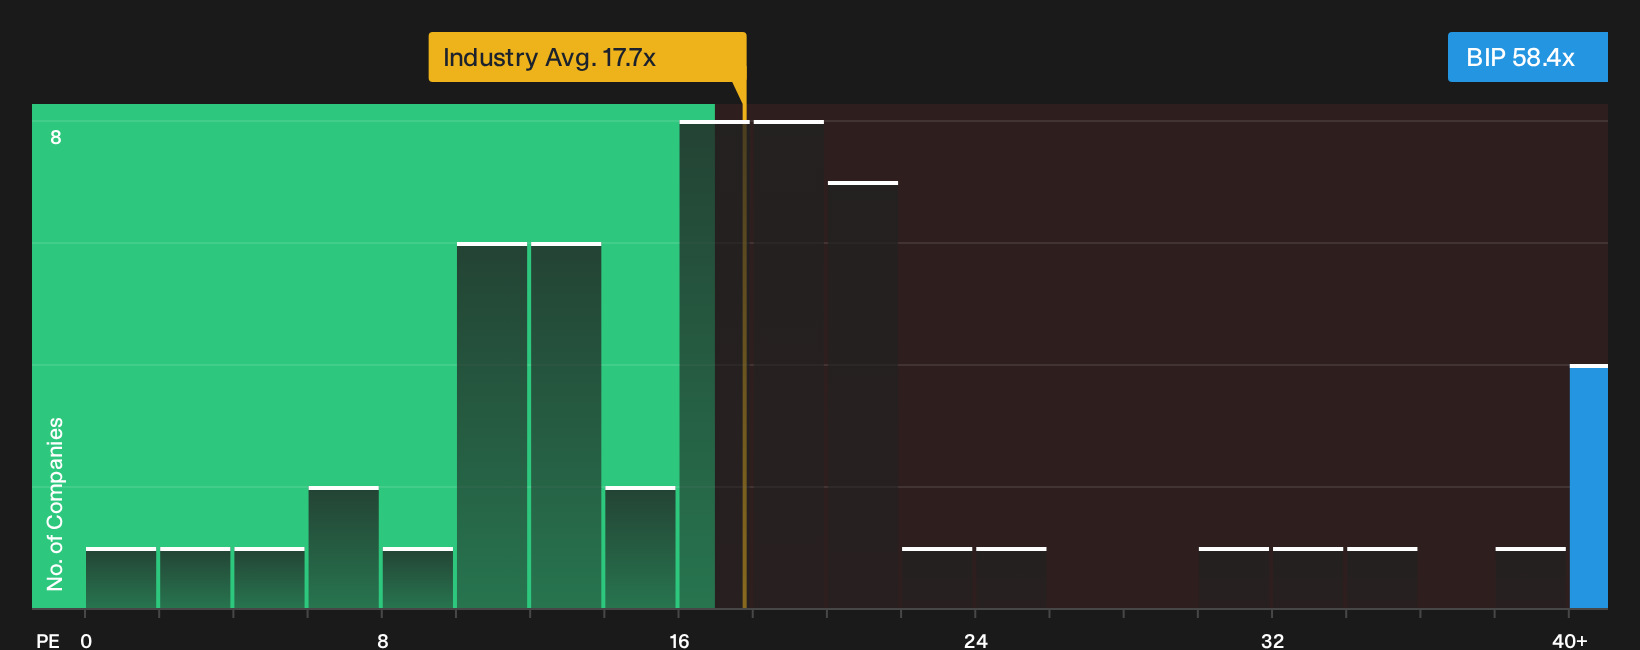
There is a sharp contrast when you stop looking at fair value models and focus on what Brookfield Infrastructure Partners costs on today’s earnings. The stock trades on a P/E of 58.4x versus 17.7x for the global integrated utilities group and 20.6x for peers, while the fair ratio sits at just 2.6x. That gap points to real valuation risk if sentiment shifts back toward current profit rather than long range AI and infrastructure stories.
Investors weighing this richer earnings multiple against the earlier undervaluation case may want to stress test their own assumptions about FFO, margins and AI project economics over the next few years before deciding which signal matters more. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Brookfield Infrastructure Partners can feel confusing, so move quickly, review the full data set, and weigh both the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Brookfield Infrastructure Partners?
If Brookfield Infrastructure Partners has you thinking harder about income, value and resilience, it makes sense to widen your watchlist with a few focused stock idea sets.
- Target stronger balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) that highlights businesses with sturdier financial footing and fewer balance sheet red flags.
- Hunt for potential mispricing through the 31 high quality undervalued stocks that filters for companies combining solid fundamentals with share prices that lag underlying metrics.
- Build a steadier income stream using the 7 dividend fortresses that surfaces higher yielding payers with distributions backed by real cash flow strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com