


A $1 Billion Reason to Buy Synopsys Stock
Synopsys (SNPS) has a fresh $1 billion reason for investors to pay attention as the chip-design software provider expands its relationship with Amazon (AMZN). Last week, Synopsys announced a multiyear agreement worth more than $1 billion with Amazon to expand the use of its semiconductor intellectual property (IP) for Amazon’s custom silicon. The deal also broadens collaboration around Synopsys’ electronic design automation, simulation and analysis, and artificial intelligence (AI)-powered engineering technologies.
The agreement is particularly significant as Amazon continues developing purpose-built chips, including its Graviton processors and Trainium AI chips, to support its cloud and AI infrastructure. Synopsys said Amazon will serve as its lead customer for application-optimized silicon IP as the company evolves toward a license-plus-royalty model, potentially allowing revenue from the IP business to scale with production volumes.
Moreover, the deal also provides a notable example of how the company is positioning itself to benefit from the growing complexity of AI chips rather than simply facing AI-related disruption. The announcement came alongside Synopsys’ 2026 Investor Day, where the company outlined a stronger long-term growth strategy. Thus, the stock could be worth buying now.
About Synopsys Stock
Synopsys is a leading provider of electronic design automation (EDA) software, semiconductor intellectual property (IP), and engineering solutions that help companies design, verify, and develop advanced chips and electronic systems. Headquartered in Sunnyvale, California, Synopsys serves semiconductor manufacturers, technology companies, and automotive and industrial businesses. The company has a market cap of around $93.9 billion.
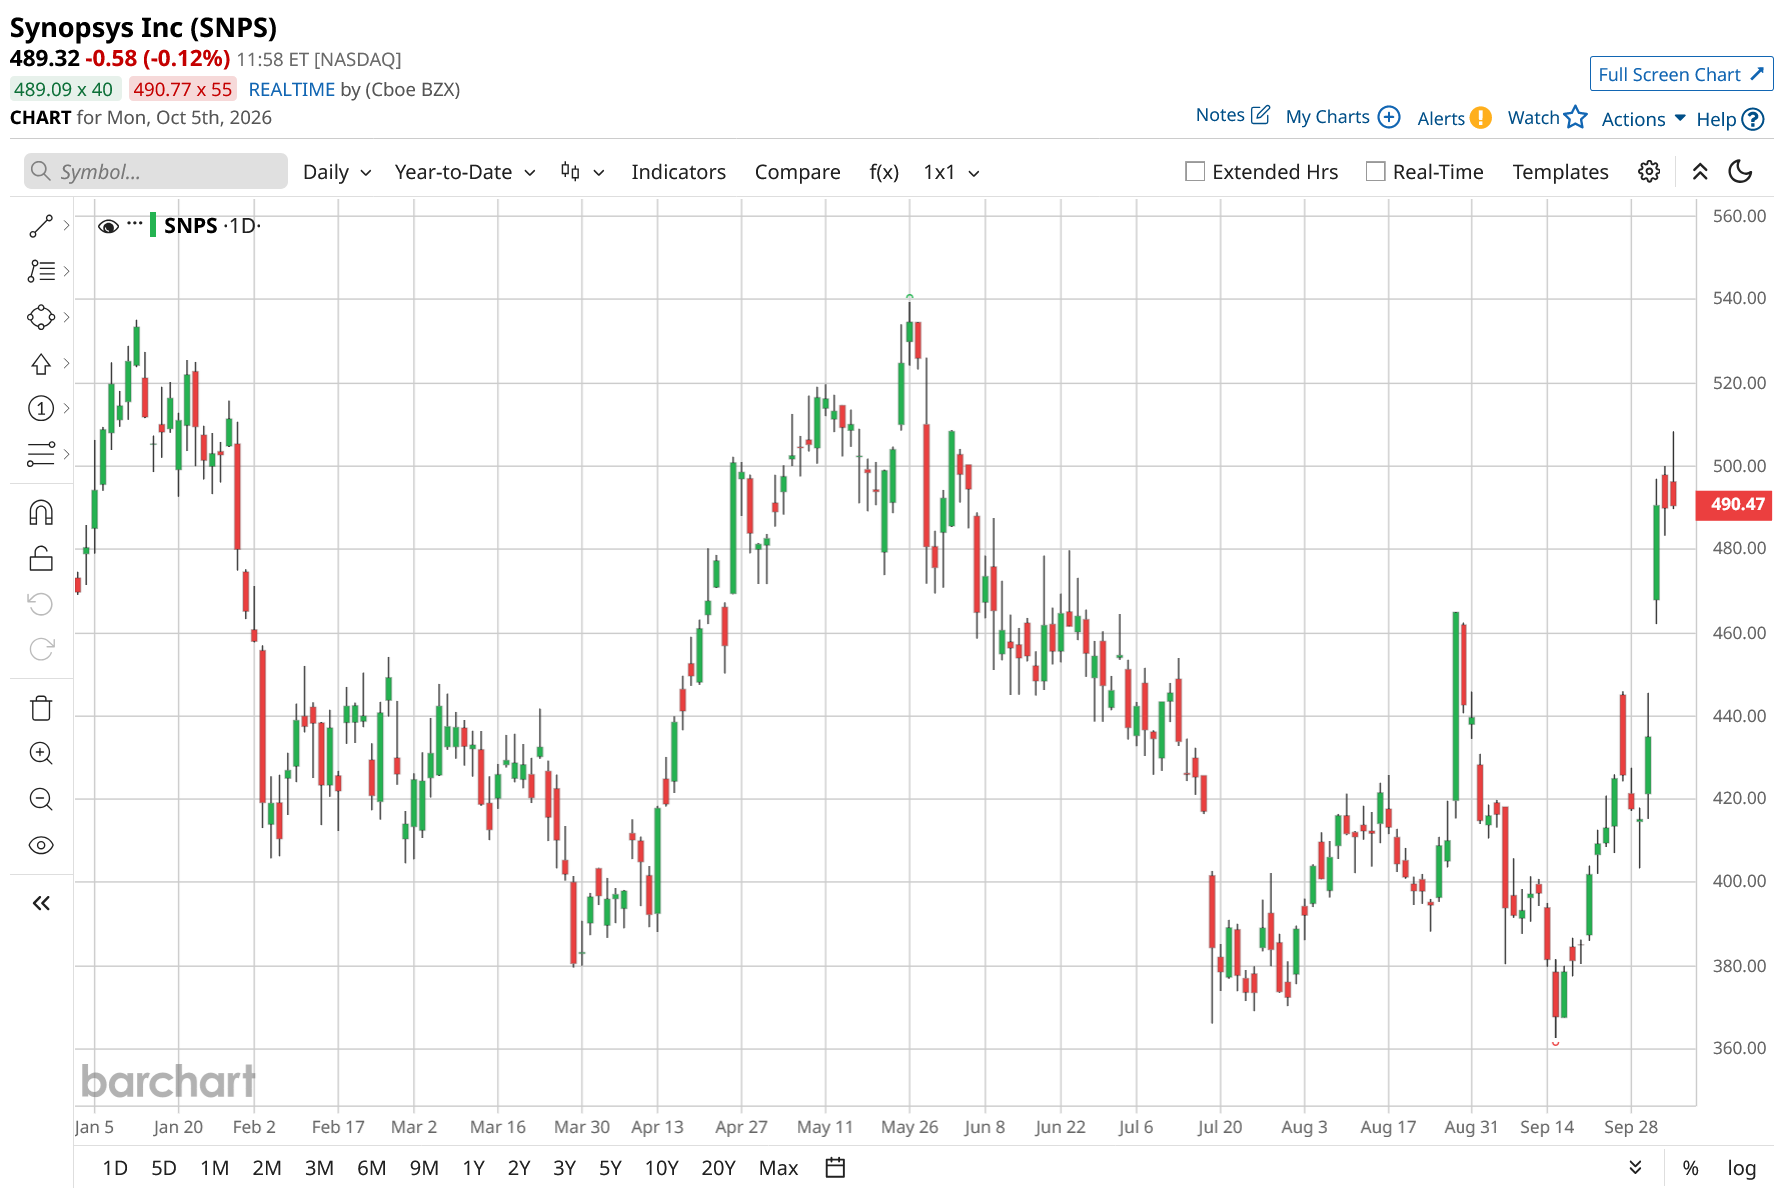
Synopsys shares have staged a sharp rebound in recent trading, gaining 18% over the past five days. However, the stock’s longer-term performance remains relatively modest, with shares up 5.3% over the past year and 5.2% year-to-date (YTD).
The recent rally followed the company’s Sept. 30 Investor Day, when Synopsys announced new AI partnerships and outlined stronger growth targets. These developments helped renew investor interest in the chip-design software provider after concerns about AI-driven disruption and the integration of its Ansys acquisition had weighed on sentiment.
A major driver of the rally was Synopsys’ announcement of a multiyear agreement with Amazon worth more than $1 billion to support custom chip development using its semiconductor intellectual property and design software. The company also partnered with OpenAI to develop GPT-Synopsys, a specialized AI model designed to assist engineers with chip-design tasks. These collaborations could create new revenue opportunities while reinforcing Synopsys’ role in the increasingly complex semiconductor design process.
Investor sentiment also improved after management projected 15% revenue growth in fiscal 2027, above expectations, and outlined a long-term plan targeting approximately mid-20% range annualized growth in earnings per share from fiscal 2026 through fiscal 2030. The planned $1 billion share repurchase program added another potential source of shareholder support.
Synopsys' stock is currently trading at 44.70 times forward earnings, which is a premium compared to industry peers.
Stable Q3 Results
Synopsys reported its third-quarter fiscal 2026 financial results on Aug. 26, delivering strong revenue growth and higher earnings. For the quarter ended July 31, revenue increased 42.4% year-over-year (YoY) to $2.5 billion. The growth reflected contributions from Ansys, acquired in July 2025, alongside demand for Synopsys’ semiconductor design and engineering solutions.
Net income attributable to Synopsys increased to $545.8 million from $242.5 million in the year-ago quarter. On a non-GAAP basis, net income grew to $752.5 million from $548.9 million in the year-ago quarter, and EPS increased to $3.91 from $3.39, exceeding the high end of the company’s previous guidance and topping analysts’ expectations.
Across its business segments, Design Automation showed solid strength with revenue rising approximately 52.7% YoY to $2 billion, including the contribution from Ansys. Design IP revenue rebounded by 10.8% to $473.8 million, reflecting improving demand for semiconductor IP solutions.
Synopsys also raised its fiscal 2026 outlook following the results. It projected full-year revenue of $9.69 billion to $9.74 billion and non-GAAP EPS of $15.04 to $15.10. Management expected a non-GAAP operating margin of 41.5%, operating cash flow of about $2.8 billion, and free cash flow of approximately $2.6 billion. For the fourth quarter, revenue was forecast at $2.53 billion to $2.58 billion, with non-GAAP EPS of $4.10 to $4.16.
In addition, analysts expect EPS of $10.97 for fiscal 2026, representing about 26.8% YoY growth, while fiscal 2027 earnings are expected to grow 25.3% to $13.74.
What Do Analysts Expect for SNPS Stock?
Wells Fargo analyst Joe Quatrochi maintained an “Overweight” rating on SNPS on Oct. 1 while raising his price target to $540 from $475. The move followed Synopsys’ Investor Day, where the company unveiled a stronger long-term growth outlook and announced major AI-related partnerships with Amazon and OpenAI.
KeyBanc also remained bullish on Synopsys following the company’s Investor Day, with analyst Jason Celino reiterating an “Overweight” rating and raising the price target slightly to $605 from $600.
Plus, Rosenblatt maintained its “Buy” rating while raising its price target to $620 from $575 on Oct. 1.
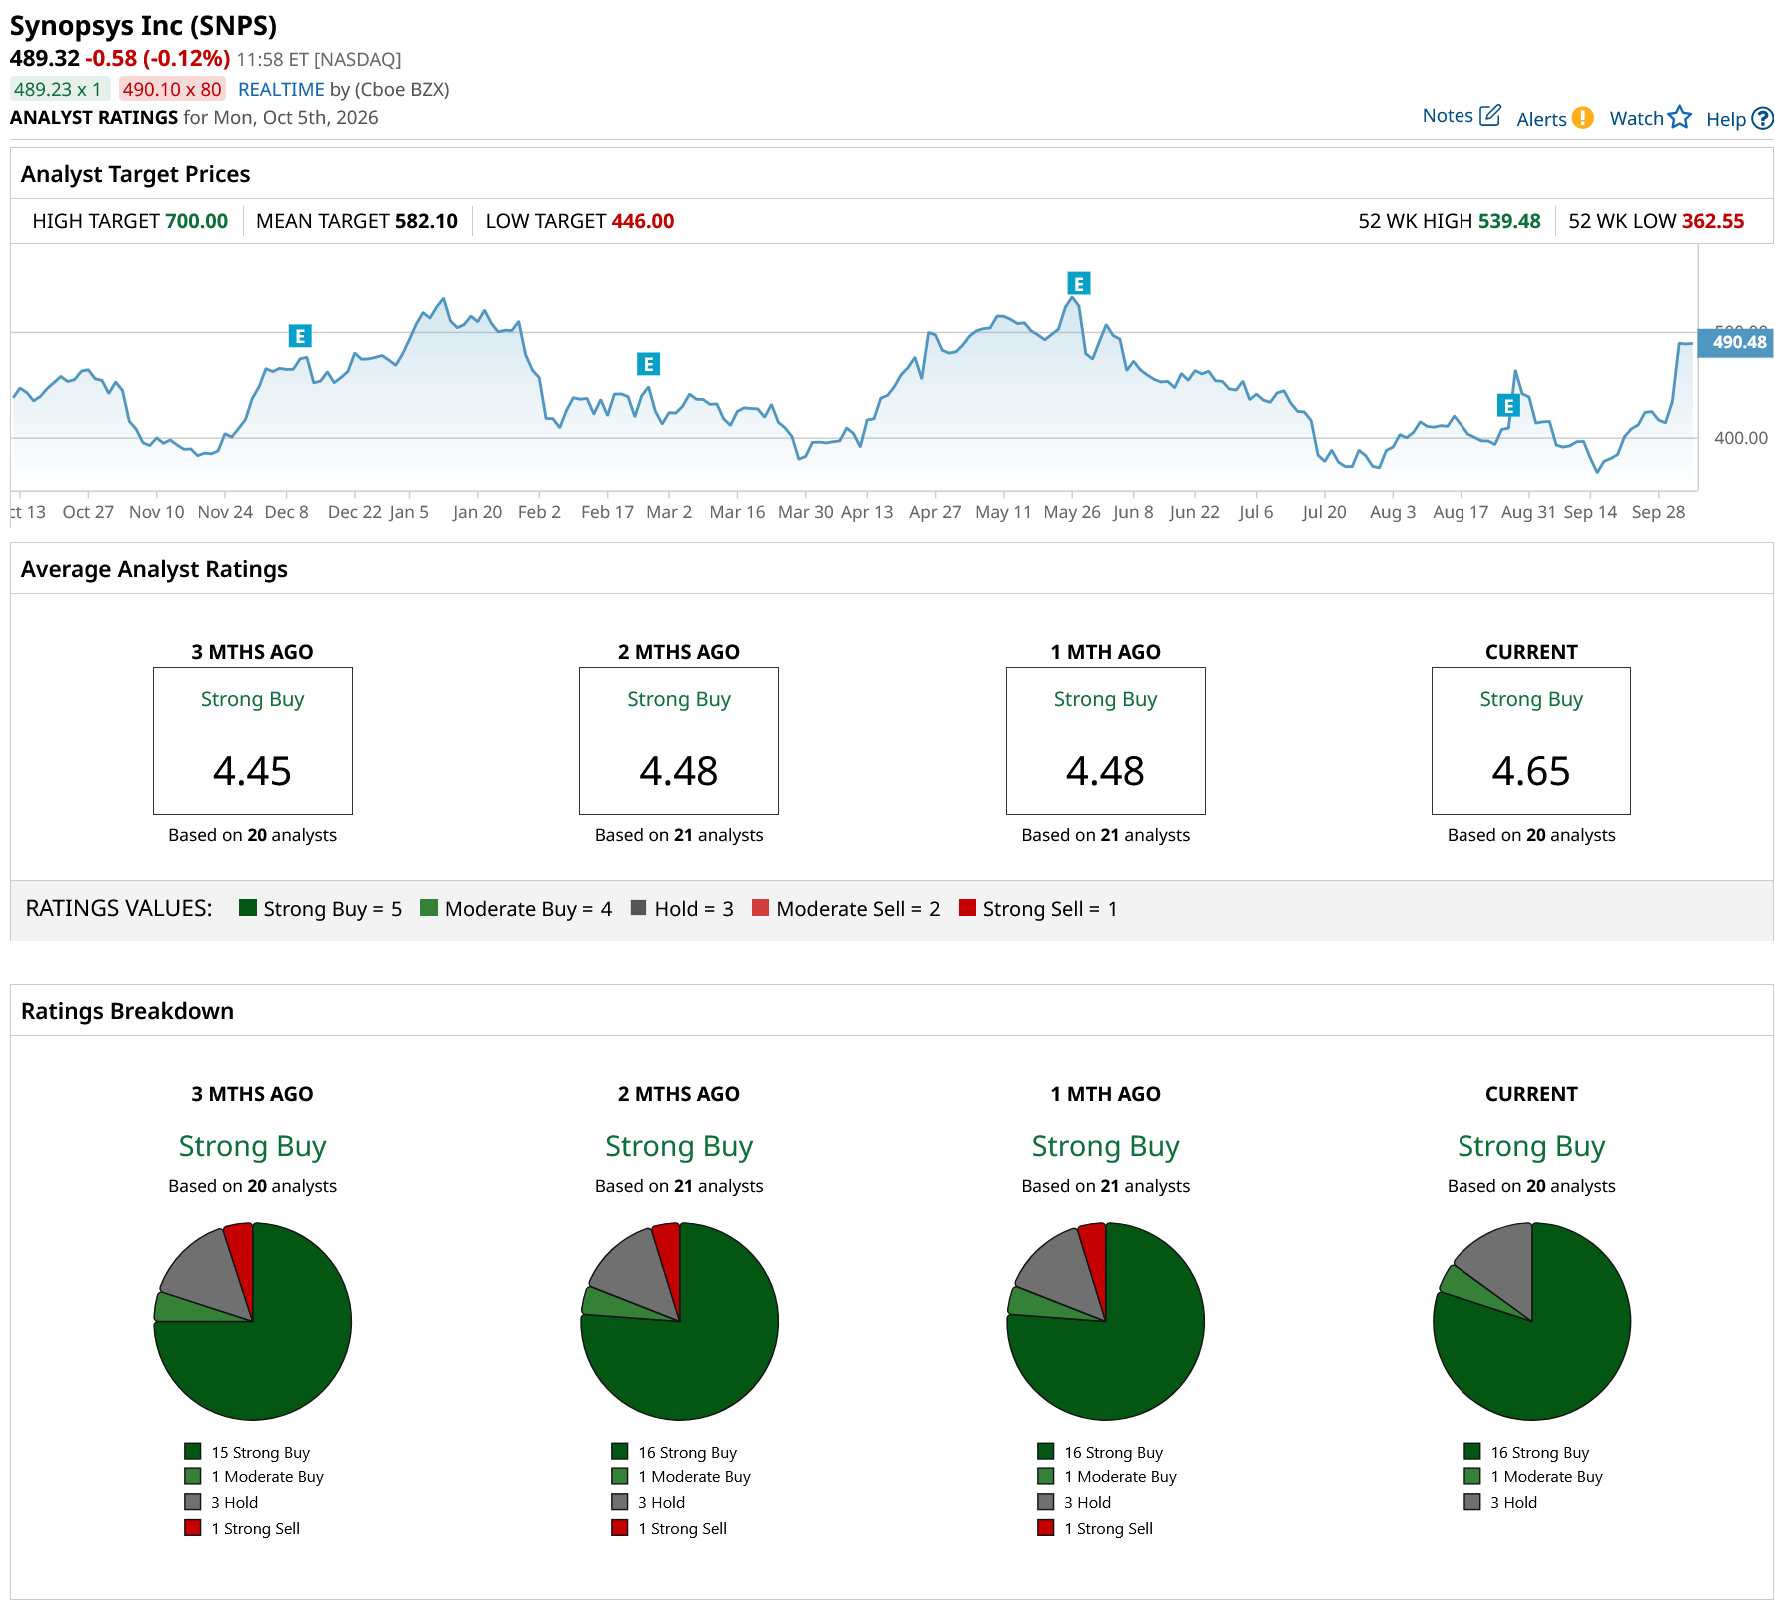
Overall, SNPS stock has a consensus “Strong Buy” rating. Out of 20 analysts covering it, 16 recommend a “Strong Buy,” one suggests a “Moderate Buy,” and three analysts stay cautious with a “Hold” rating.
SNPS’ average analyst price target of $582.10 reflects an upside of 19%, while the Street-high target price of $700 suggests 43% upside ahead.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.