


Will Square Seller Sync Change Apple (AAPL) Narrative
- Square previously announced a new integration with Apple that lets Square sellers manage and sync their business location details to Apple Business directly from the Square Dashboard. This means information on Apple Maps, Siri AI, Apple Wallet and other Apple apps stays consistent without separate updates.
- The link between Square and Apple Business could influence how small and mid sized merchants think about Apple as a demand funnel, since menus, orders, bookings and other action links can now sit just a click away from discovery on Apple Maps place cards.
- Next, the focus shifts to how Apple’s investment narrative might be affected by this tighter Square Dashboard connection into Apple Maps discovery.
What Is Apple's Investment Narrative?
Owning Apple usually comes down to a simple belief. You think this business can keep turning a massive global device base into recurring, higher margin services while still refreshing hardware often enough to hold pricing power. That is an execution story. It depends on tight product cycles, disciplined capital spending and steady demand across iPhone, Mac, iPad and wearables, supported by services that already sit on hundreds of millions of active devices.
The Square and Apple Business integration fits that thesis as an incremental support for services engagement rather than a major earnings catalyst. It strengthens Apple Maps, Siri AI and Wallet as daily touchpoints. This can help protect the broader ecosystem but likely does not move revenue forecasts on its own. The class action settlement around Apple Intelligence powered Siri shows the legal and product promise gap risk that sits alongside a premium P/E multiple and very high forecast return on equity.
That said, there is a quieter pressure point around Apple that rarely makes the headline narrative...
There's only one way to know the right time to buy, sell or hold Apple. Head to Simply Wall St's company report for the latest analysis of Apple's Fair Value.
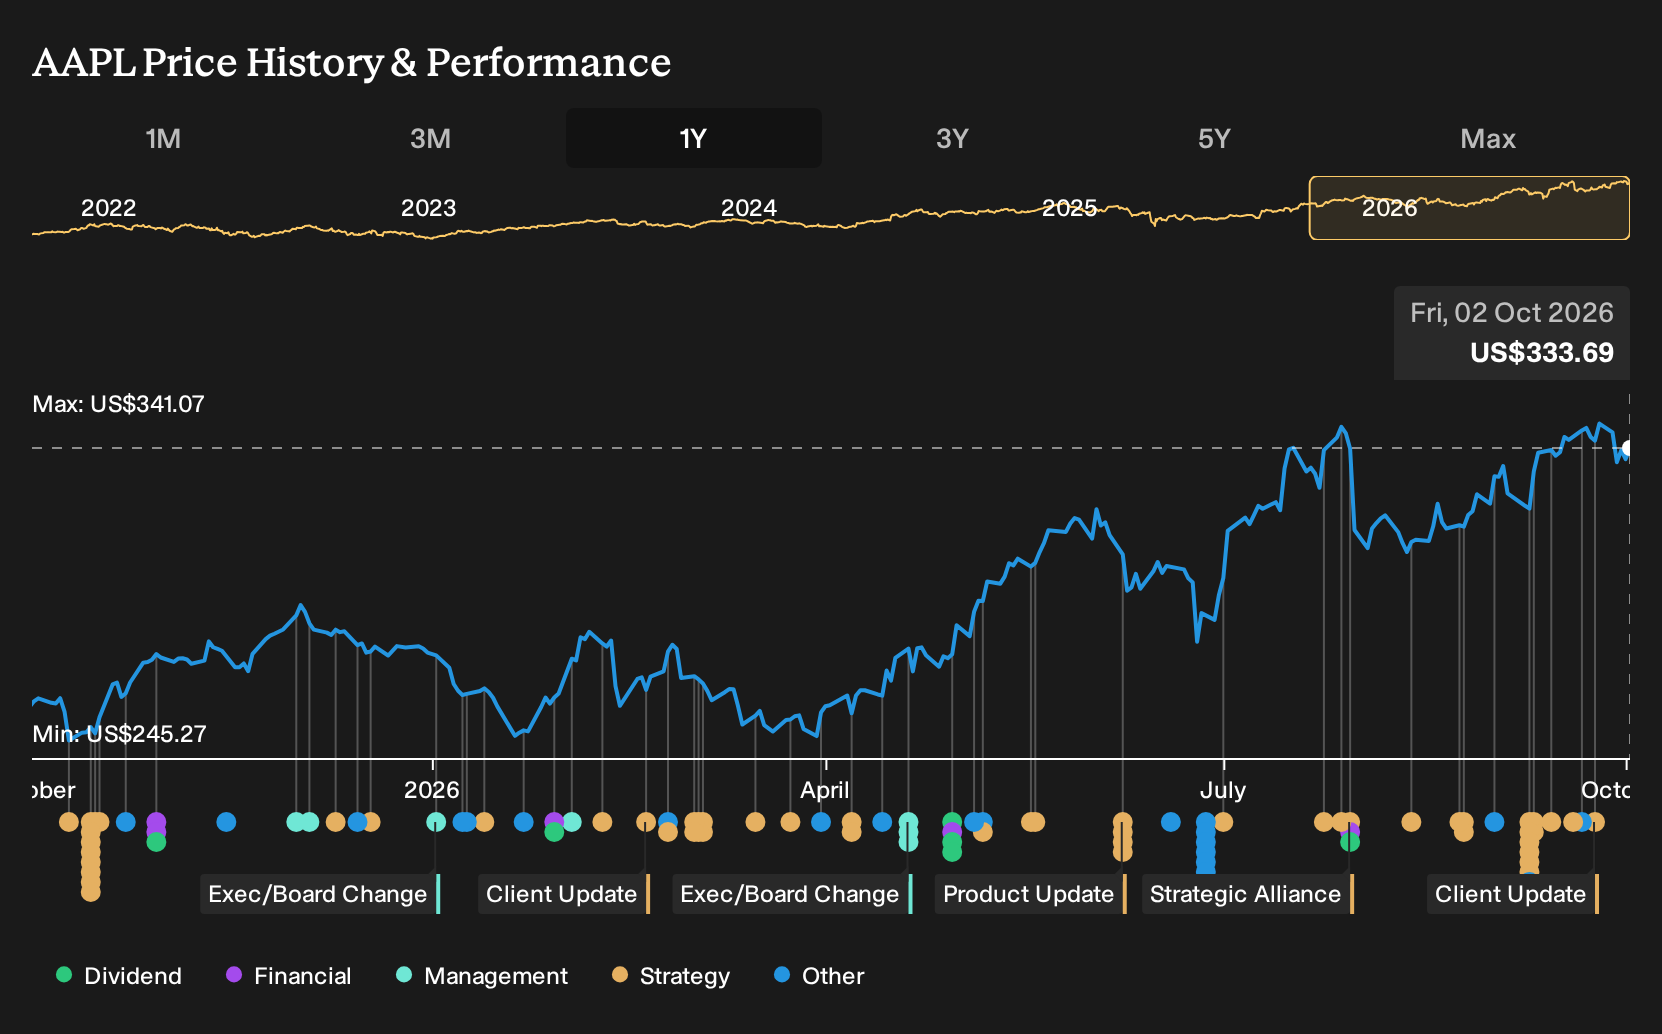
Exploring Other Perspectives
One alternate view around Apple focuses on legal and component cost risk rather than ecosystem strength. The most bearish analysts were already baking in margin pressure, with revenues of about US$623.9b and earnings of US$156.0b by 2029, before this Square Maps integration. You could see those cautious expectations shift if this discovery funnel proves more powerful than they assumed.
Explore 41 other Apple fair value estimates, including one that suggests as much as 45% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Apple research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Apple. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Apple's overall financial health at a glance.
Looking For More Investment Ideas Beyond Apple?
Once you have a handle on Apple's story, it can help to widen the lens and compare it with other opportunities that share some of the same qualities you value or intentionally offer something different.
- If you want potential mispricings with strong fundamentals, scan through our 31 high quality undervalued stocks and see which companies merit a closer look next.
- For investors who care most about consistency and resilience, filter for sturdier balance sheets using the list of solid balance sheet and fundamentals (25 results) to see which businesses meet that threshold.
- If you are hunting for lesser known opportunities with solid metrics, sort through our 19 high quality undiscovered gems and line them up against your view on Apple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com