


UMH Properties (UMH) Faces Activist Board Push, Is It Still 21% Below Fair Value?
Erez Asset Management has gone public with a campaign to reshape the board at UMH Properties (UMH), arguing for governance changes that could influence strategy, capital allocation and how investors view the stock.
UMH Properties shares trade at US$15.41 after a small 1 day share price return of 0.52% and a softer 30 day share price return of 3.39% that contrasts with a 1 year total shareholder return of 14.98%. This suggests that shorter term momentum has faded even as longer term holders have still seen gains supported by regular common and preferred dividend declarations and now fresh activist pressure on the board.
Compare UMH Properties with a curated set of real estate peers by reviewing our hand picked list of 31 high quality undervalued stocks that pair balance sheet strength with cash flow support.
UMH Properties just inched higher even as short term performance softened and an activist steps up. Is that a window to start building exposure now, or a setup that rewards waiting for a cheaper entry before the valuation work stacks up?
Most Popular Narrative: 21% Undervalued
UMH Properties closed at $15.41 compared with a widely followed fair value estimate of $19.43 per share, which frames the activist noise against a backdrop of valuation support built on detailed revenue and margin assumptions.
The ongoing U.S. housing affordability crisis and the persistent shortage of conventional single-family and multifamily homes continue to drive high demand for quality, affordable manufactured housing, supporting strong occupancy rates and long-term rent growth, benefitting top-line revenue.
UMH's active expansion into energy-rich, high-growth regions (e.g., Marcellus and Utica Shale) and high-demand markets in the Midwest, Northeast, and Southeast is associated with above-industry property appreciation and consistently strong occupancy gains, which in turn is linked to higher rental income and asset value accretion.
See why 9 investors see UMH Properties as 21% undervalued.
Result: Fair Value of $19.43 (UNDERVALUED)
Still, the bullish UMH Properties story can fray if acquisition opportunities remain scarce, or if heavier reliance on debt funding further squeezes already modest profit margins.
Find out about the key risks to this UMH Properties narrative.
Another View On UMH Properties Valuation
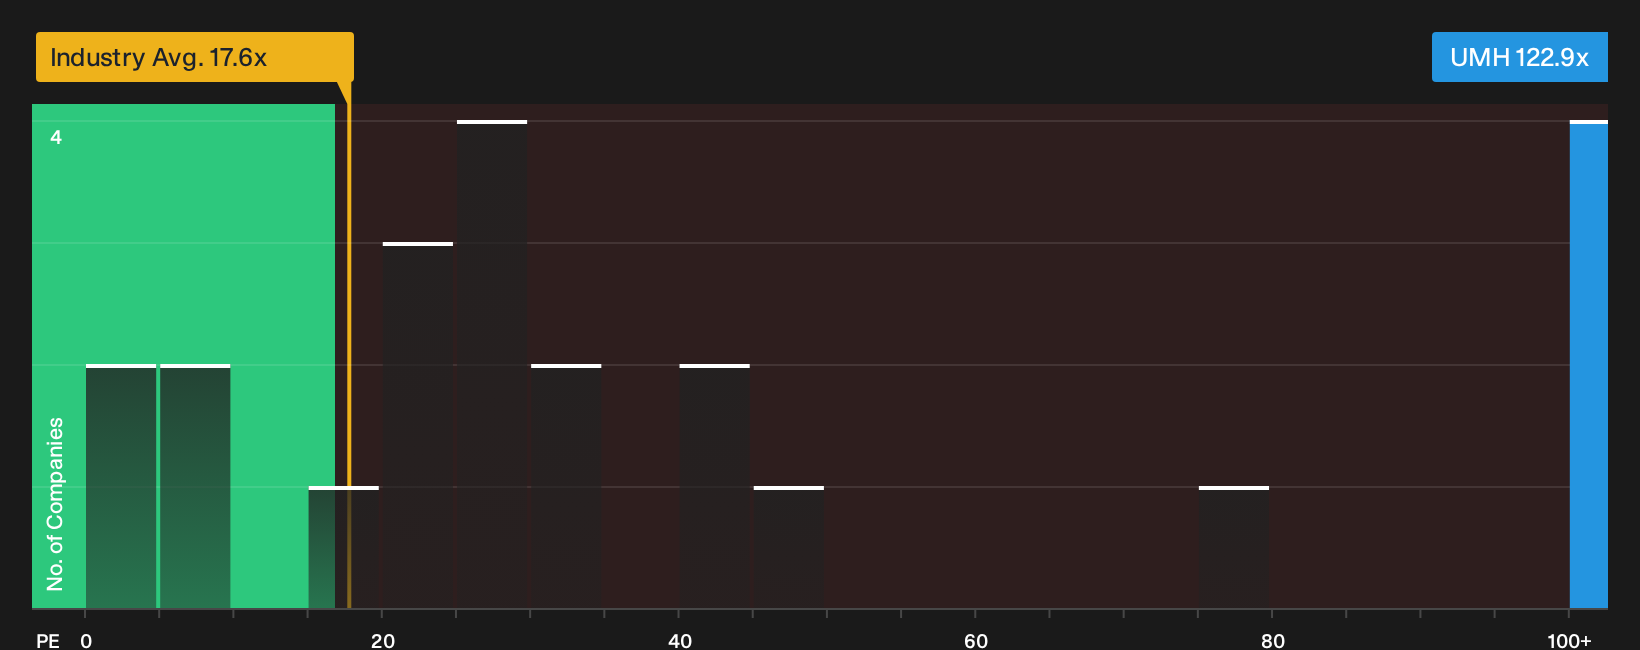
The first fair value anchor of $19.43 paints UMH Properties as undervalued, yet the market is attaching a very rich P/E of 122.9x today. That compares with 17.6x for the global Residential REITs group, peers at 43.4x, and a fair ratio of 35.9x that our model suggests markets could gravitate toward over time.
Such a wide premium points to meaningful valuation risk if sentiment or growth expectations cool, even with a discounted fair value estimate already in hand. It raises a simple question for investors: Is the current price reflecting opportunity, or optimism that may be hard to live up to over the next few years?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mix of activism, valuation signals and boardroom questions around UMH Properties points to opportunity or just extra noise. Take a few minutes to review the data, weigh both the upside arguments and the concerns that other investors flag, and then ground your own stance in the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond UMH Properties?
If UMH Properties has sharpened your thinking, do not stop there. Fresh ideas often come from comparing it with very different businesses uncovered by targeted screeners.
- Hunt for mispriced quality and see which companies currently line up as potential bargains through the 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused set of higher yielding opportunities using the 7 dividend fortresses.
- Sleep easier at night by scanning companies that pair resilience with measured risk profiles via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com