


HP (HPQ) Unveils AI Ready Laptops, Is The Rally Already Priced In?
HP (HPQ) just rolled out two fresh laptops, the consumer focused HP OmniBook 5 and the business oriented HP ProBook 4, both built around AI ready chips, long battery life and portability.
These launches land while HP’s share price has climbed 42.12% over the past 90 days and 45.21% year to date to US$32.12, with a 26.72% 1 year total shareholder return. This suggests recent momentum has been strong as the market reassesses the company’s prospects.
Scan beyond HP to see what other AI focused PC and hardware plays are gaining traction in the curated list of 90 AI infrastructure stocks.
HP now trades above the average analyst target, yet still appears to sell at a sizeable intrinsic discount. After a 42% 90 day surge, is the market being too cautious or correctly pricing in the risk?
Most Popular Narrative: 8% Overvalued
HP’s most followed valuation narrative pegs fair value at $29.66 using a 9.56% discount rate, compared with the current $32.12 share price, which points to a modest premium that still sits alongside a sizeable implied discount in the SWS DCF work.
Persistent structural cost reduction initiatives, including manufacturing diversification outside China, AI-enabled automation, and a $2B annualized savings target, are set to drive sustainable improvements in net margins and bottom-line earnings resilience. HP's focus on responsible innovation and sustainability, exemplified by significant recycled content in devices and advances toward net zero, aligns with growing enterprise and consumer preference for eco-friendly technology, strengthening competitive positioning and supporting revenue and margin growth over the long term.
See why 60 investors see HP as 8% overvalued.
Result: Fair Value of $29.66 (OVERVALUED)
Still, structural pressure in HP's print business and intense PC price competition could easily challenge the current AI driven optimism around margins and valuation.
Find out about the key risks to this HP narrative.
Another View On HP Using Earnings Multiples
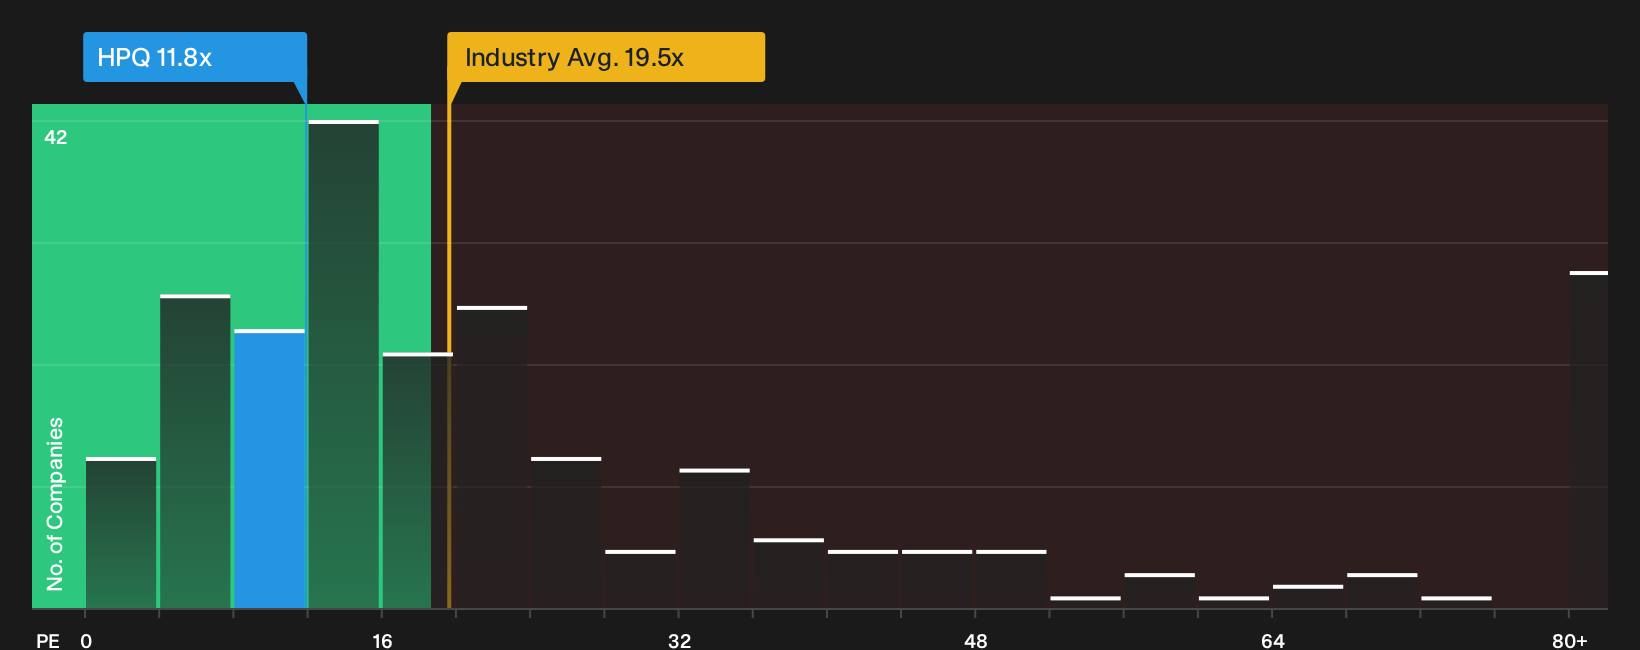
While the SWS DCF work points to HP trading at a sizeable discount to estimated future cash flows, the earnings multiple presents a different perspective. HP changes hands at a P/E of 11.8x, compared with a fair ratio of 25.6x, a global tech average of 19.5x and a peer average of 65.8x. That wide gap suggests the market is pricing in meaningful risk even after the recent rally. The key question is whether those concerns match your view of HP's long term earnings power.
See what the numbers say about this price, and how the market could move closer to that fair ratio, in our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed messages around HP leave you undecided, look at the actual numbers and sentiment data. Then stress test the bull and bear angles yourself with 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond HP?
HP might be front of mind today, but your next strong opportunity could sit in a completely different corner of the market. Use screeners to quickly filter noisy markets into focused shortlists built around financial strength, return potential and risk profile.
- Target potential upside by scanning a curated set of quality companies trading at what may be attractive valuations through the 31 high quality undervalued stocks.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with sturdier financial footing.
- Sharpen your watchlist by surfacing 19 high quality undiscovered gems that many investors may be overlooking right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com