


Is Rogers (ROG) Fully Priced On Its 2030 Guidance And Acquisition Upside?
Rogers (ROG) outlined its long term ambitions at its 2026 Analyst and Investor Day, issuing revenue targets for 2028 and 2030 while highlighting potential acquisitions as an additional upside lever.
Rogers has seen momentum build quickly into and around the Analyst Day, with a 1-day share price return of 2.70%, a 7-day share price return of 16.14% and a year-to-date share price return of 73.97% at a latest share price of US$160.0.
Scan for other materials and electronics players showing similar guidance driven momentum by checking our hand picked 40 power grid technology and infrastructure stocks alongside Rogers.
After a near 74% year to date surge in Rogers, the real tension now sits in the valuation question. Is the meaningful upside still in front of the stock, or has most of it already played out?
Most Popular Narrative: 17% Undervalued
Rogers closed at $160.0 against a widely followed narrative fair value of $193.33, so the current price sits below that modeled estimate while still embedding strong expectations for execution.
Rogers is poised to benefit from long-term growth in electric vehicles and broader electrification trends globally, as evidenced by an expanding customer base in China's rapidly growing EV market and design wins with leading local power module manufacturers. This should drive sustained revenue growth and increase market share over time.
See why 1 investors see Rogers as 17% undervalued.
Result: Fair Value of $193.33 (UNDERVALUED)
Still, Rogers faces pressure if weaker EV demand persists or if Chinese competitors continue to gain share, which could challenge the growth narrative that investors are leaning on.
Find out about the key risks to this Rogers narrative.
Another View On Rogers Valuation
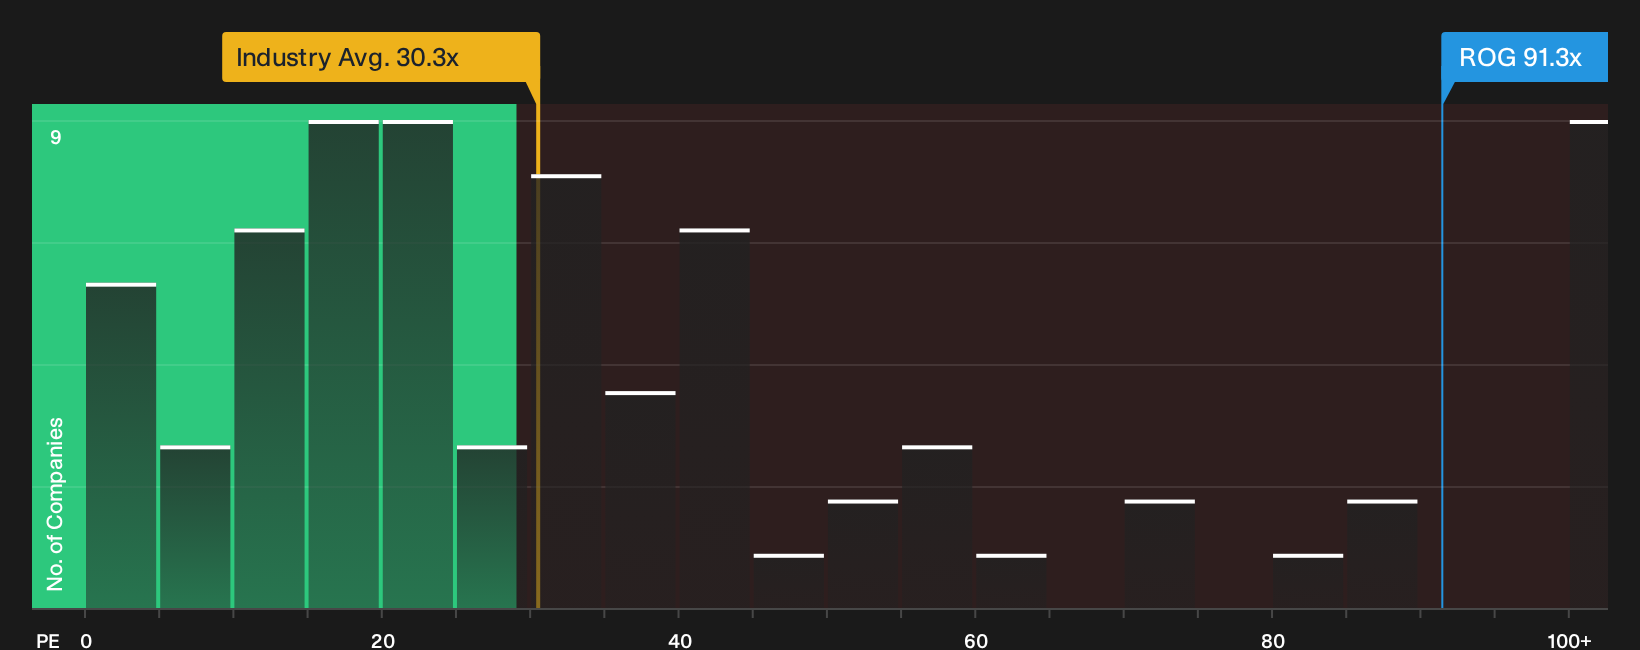
There is a catch. While the narrative fair value suggests Rogers is undervalued, its current P/E of 91.3x is far above both the US Electronic industry at 30.3x and the peer average at 39.1x, and more than double the fair ratio of 39.3x. That gap points to meaningful valuation risk if sentiment cools.
To see how those numbers stack up in more detail, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Rogers so far. If you want to move quickly and ground your own take in the data, start with the 3 key rewards and 1 important warning sign.
Looking for more Rogers investment ideas?
If you are serious about sharpening your edge beyond Rogers, use the Simply Wall St screener to spot opportunities others might ignore while you still have time.
- Target dependable compounding by scanning companies that combine yield with resilience through the 7 dividend fortresses.
- Hunt for quality at a discount by filtering for fundamentals that stack up attractively using the 31 high quality undervalued stocks.
- Protect your downside first by focusing on sturdier balance sheets and earnings profiles with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com