


Why Did Precigen (PGEN) Stock Climb After Its Latest Update?
Precigen (PGEN) just received platform technology designation from the US Food and Drug Administration for its AdenoVerse immunotherapy platform, tying the stock story directly to the regulatory pathway behind PAPZIMEOS and future candidates.
Short term, momentum in Precigen has been strong, with a 1-day share price return of 4.02%, 7-day move of 10.19% and 30-day gain of 20.28%. The 90-day share price return of 52.50% and year-to-date rise of 99.53% sit against a 1-year total shareholder return of 162.77% and a 3-year total shareholder return that is a little over 6x. This suggests that recent enthusiasm around developments like the FDA platform technology designation is building on a much longer run of shifting expectations around the business.
Scan for other platform-driven biotech opportunities moving on real clinical catalysts by reviewing the curated 35 healthcare AI stocks alongside Precigen's latest FDA designation.
Bulls see Precigen’s FDA platform nod and first approved product as the start of a broader franchise. Bears focus on losses and biotech cyclicality. Which story does the current valuation lean toward?
Most Popular Narrative: 37% Undervalued
Precigen's most followed valuation storyline pins fair value at $13.65 compared with the last close of $8.54, so the pricing debate now revolves around how durable the PAPZIMEOS launch and platform economics really are.
A potential transition to cash flow breakeven funded by current cash plus projected PAPZIMEOS revenues, along with a simplified capital structure with preferred shares converted to common, could limit dilution risk and allow operating leverage to flow through to earnings as SG and A launch spending normalizes.
See why 12 investors see Precigen as 37% undervalued.
Result: Fair Value of $13.65 (UNDERVALUED)
Still, the Precigen narrative leans heavily on a single early-stage product and ambitious margin targets, so any slowdown in PAPZIMEOS uptake or pricing pressure could quickly challenge that 37% undervalued story.
Find out about the key risks to this Precigen narrative.
Another View: Precigen Through A Sales Multiple Lens
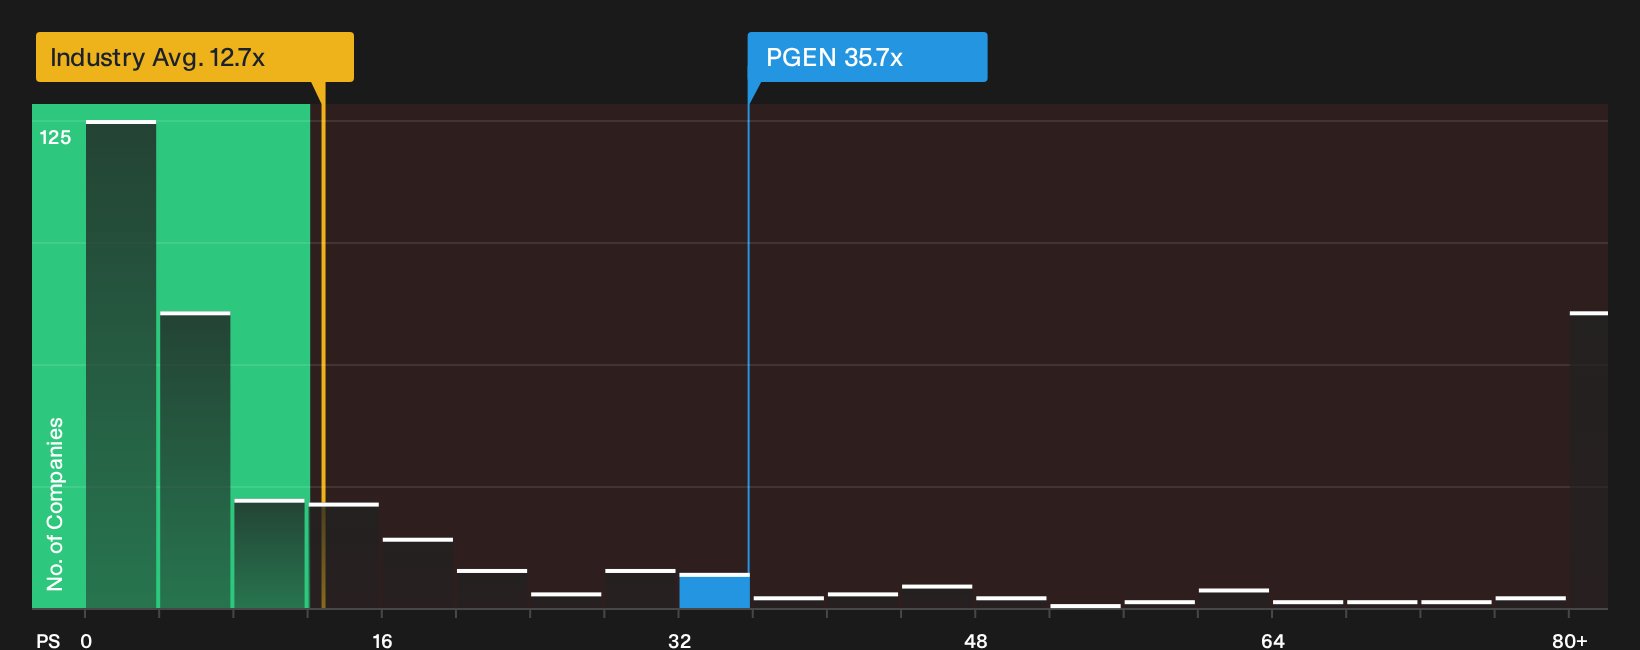
While Precigen looks 37% undervalued on the fair value narrative, its P/S of 35.7x is far higher than both US Biotechs at 12.7x and the 9.6x fair ratio. That gap points to meaningful valuation risk if sentiment cools or growth assumptions get marked down.
For investors weighing that trade off, it helps to see what the numbers imply in detail, not just the headline multiple. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So with Precigen pulled in two directions by optimism on the platform and concern about execution risk, move quickly and test the data against your own risk tolerance, timeframe, and return expectations, then anchor that view with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Precigen?
If Precigen has sharpened your appetite for opportunity, do not stop here. The next portfolio upgrade often comes from the ideas you almost skipped.
- Target potential mispricings by scanning a curated pool of quality candidates through the 31 high quality undervalued stocks that could complement or contrast your Precigen thesis.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (25 results) so you can balance higher risk biotech exposure with sturdier businesses.
- Hunt for future market leaders early by checking a focused set of 19 high quality undiscovered gems before they attract wider attention and capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com