


Is Affirm Holdings (AFRM) Undervalued Following Its Crate And Barrel Partnership?
Crate & Barrel partnership puts Affirm’s model back in focus
Affirm Holdings (AFRM) just expanded its pay over time network through a new partnership with Crate & Barrel Holdings, giving eligible shoppers installment options across Crate & Barrel, Crate & Barrel Kids and CB2.
The arrangement covers online and in store purchases in the United States and Canada, with biweekly or monthly payments that can start at 0% APR and no late or hidden fees, which matters for how customers perceive Affirm’s offering.
Affirm Holdings’ latest partnership lands at a time when momentum has cooled, with the 90 day share price return down 17.5% and the year to date share price return down 4.4%, even as the 3 year total shareholder return is up almost 3x.
Scan beyond Affirm Holdings and see how other pay over time and specialty finance players line up in our hand picked 19 high quality undiscovered gems.
Affirm Holdings now pairs a fresh Crate & Barrel deal with a share price that has slipped over the past year. Are you being paid to wait for a better entry, or to lean in today based on valuation?
Most Popular Narrative: 29% Undervalued
Analysts following Affirm Holdings see a fair value of $99.23 against a last close of $70.77, which frames the current pullback as a discount based on their long term forecasts and risk assumptions.
Rapid growth and strong engagement with Affirm Card, an actively invested product moving toward high attach rates and greater offline usage, expands Affirm's addressable market beyond online retail, diversifies revenue streams, and drives higher frequency of transactions, which should accelerate GMV and contribute to margin improvement.
See why 51 investors see Affirm Holdings as 29% undervalued.
Result: Fair Value of $99.23 (UNDERVALUED)
Still, Affirm Holdings faces real pressure if a key merchant relationship rolls off as planned and if 0% APR products weigh on profitability more than analysts expect.
Find out about the key risks to this Affirm Holdings narrative.
Another View On Affirm Holdings’ Valuation
While analyst targets frame Affirm Holdings as undervalued, the SWS DCF model tells a different story. On that measure, AFRM at $70.77 sits above an estimated future cash flow value of $61.67, which points to a premium rather than a discount. Which signal matters more to you: analyst optimism or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
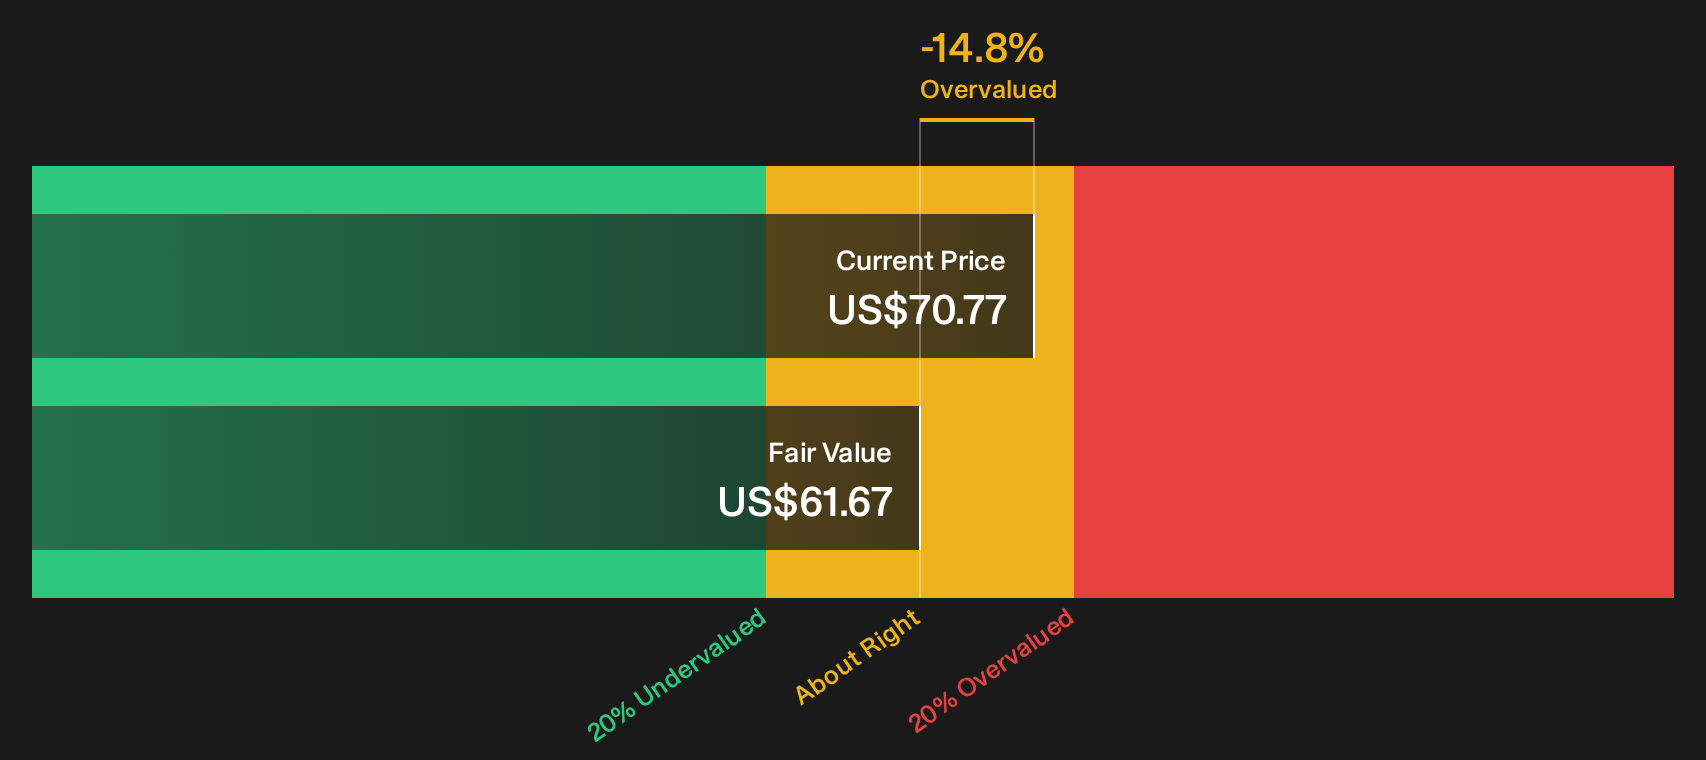
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Affirm Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Affirm Holdings are clear, with bulls pointing to upside and skeptics circling the open questions. If you want to move quickly and ground your own view in the underlying data, start with the balance of 5 key rewards and 3 important warning signs
Looking for more investment ideas beyond Affirm Holdings?
Do not stop with Affirm Holdings. Use the Simply Wall St screener to quickly surface fresh opportunities that fit your style before everyone else chases them.
- Target potential upside in quality opportunities that trade below fair value by scanning the 31 high quality undervalued stocks built from fundamentals.
- Strengthen your income stream by focusing on companies that combine higher yields with resilience through the 7 dividend fortresses.
- Dial down volatility in your portfolio by concentrating on businesses with healthier finances using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com