


Lamb Weston Holdings (LW) Faces Earnings Pressure As Valuation Debate Builds
Earnings pressure and fresh equity overhang set the stage
Lamb Weston Holdings (LW) heads into its October 6 quarterly report with analysts expecting earnings per share to decline compared with last year, while a recent US$182.9m ESOP shelf registration adds fresh potential equity supply.
The Lamb Weston Holdings share price has been choppy, with a 1-day share price return of 5.88% after the ESOP shelf news. However, the 30-day share price return is down 12.57% and the 1-year total shareholder return has declined 28.54%, pointing to fading momentum as investors reassess both growth prospects and equity dilution risk.
Spot opportunities beyond Lamb Weston Holdings by scanning a curated 31 high quality undervalued stocks that may appeal if you are watching for potential value plays after earnings and equity issuance news.Bulls point to Lamb Weston Holdings trading below analyst targets and generating profits, while bears focus on the earnings pressure and fresh ESOP overhang. Which side does the current valuation actually support?
Most Popular Narrative: 21% Undervalued
Lamb Weston Holdings is valued at a narrative fair value of $55.25 against a last close of $43.60, which frames the current debate around whether the pullback and ESOP overhang already reflect the key business risks.
The main thing that has to go right is successful execution of cost discipline and international restructuring, including lower recurring capex, plant closures, and a reset of the EMEA network so that international earnings begin to recover from the currently weaker base.
See why 22 investors see Lamb Weston Holdings as 21% undervalued.
Result: Fair Value of $55.25 (UNDERVALUED)
Still, Lamb Weston Holdings faces real swing factors, including ERP related class actions and pressure on international profitability that could unsettle the current valuation story.
Find out about the key risks to this Lamb Weston Holdings narrative.
Another View: Multiples Paint A Tougher Picture For Lamb Weston Holdings
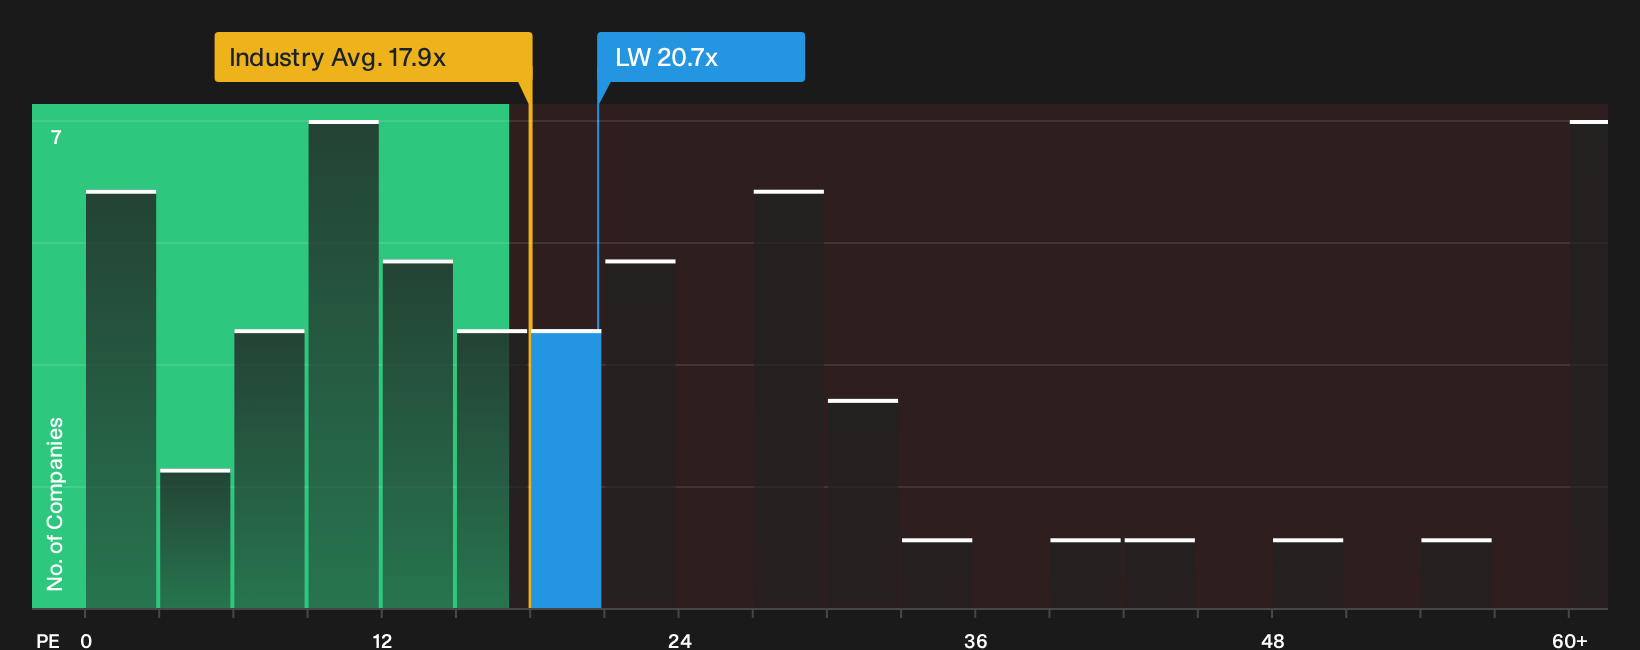
The SWS DCF model casts Lamb Weston Holdings as undervalued, yet the simple earnings multiple tells a different story. LW trades on a P/E of 20.7x, compared with 17.9x for the US Food industry, 9.9x for peers, and a fair ratio of 19.6x that the market could move toward. That gap points to real valuation risk if sentiment shifts back toward sector norms.
For a closer look at how this earnings multiple compares to peers and the fair ratio, and what that might mean for future pricing power, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Torn between the risks and rewards around Lamb Weston Holdings, or already leaning one way? Act while the information is fresh and pressure test that view against 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lamb Weston Holdings?
If you stop with Lamb Weston Holdings, you only see one angle. Broaden your watchlist now and give yourself more ways to respond when conditions change.
- Target upside potential by scanning a focused 19 high quality undiscovered gems that highlights under-the-radar companies with strong underlying fundamentals.
- Prioritize resilience first and sort through a 31 resilient stocks with low risk scores tailored to businesses with sturdier risk profiles than the broader market.
- Zero in on balance sheet strength using a curated list of solid balance sheet and fundamentals (25 results) that filters for financial stability alongside core fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com