


Glaukos (GKOS) Could Be 17% Below Fair Value After Its Strong Share Price Run
Glaukos (GKOS) has been drawing fresh attention after a strong run in its share price this year, with the latest close at US$163.75 bringing investor focus to what is already priced in.
Recent trading has been choppy, with a 6.0% 7 day share price return but a 30 day share price return that is down 7.7%. However, the 90 day share price return of 10.1% and 1 year total shareholder return of 87.3% indicate that momentum has been building over a longer stretch.
Scan beyond Glaukos and compare this price run to a curated 35 healthcare AI stocks that are also catching attention for their role at the intersection of medicine and advanced tech.
After a near 50% year to date climb and an 87.3% 1-year total return, the question around Glaukos is simple: Is meaningful upside still ahead, or has the recent surge already done the heavy lifting on valuation?
Most Popular Narrative: 16.7% Undervalued
Glaukos is trading at $163.75 against a widely followed fair value estimate of about $196.46, which frames the recent share price strength as still leaving room according to that narrative.
Glaukos' pipeline diversification into corneal health (Epioxa approval expected in late 2025/early 2026), novel glaucoma devices, and early-stage retinal programs positions the company to benefit from increased diagnostic rates and expanding access to ophthalmic interventions globally, providing avenues for future top-line growth and risk mitigation against single-product dependency.
See why 2 investors see Glaukos as 17% undervalued.
Result: Fair Value of $196.46 (UNDERVALUED)
Still, the Glaukos narrative can be knocked off course if reimbursement turns less favourable or if key launches like iDose TR or Epioxa disappoint expectations.
Find out about the key risks to this Glaukos narrative.
Another View on Glaukos Valuation
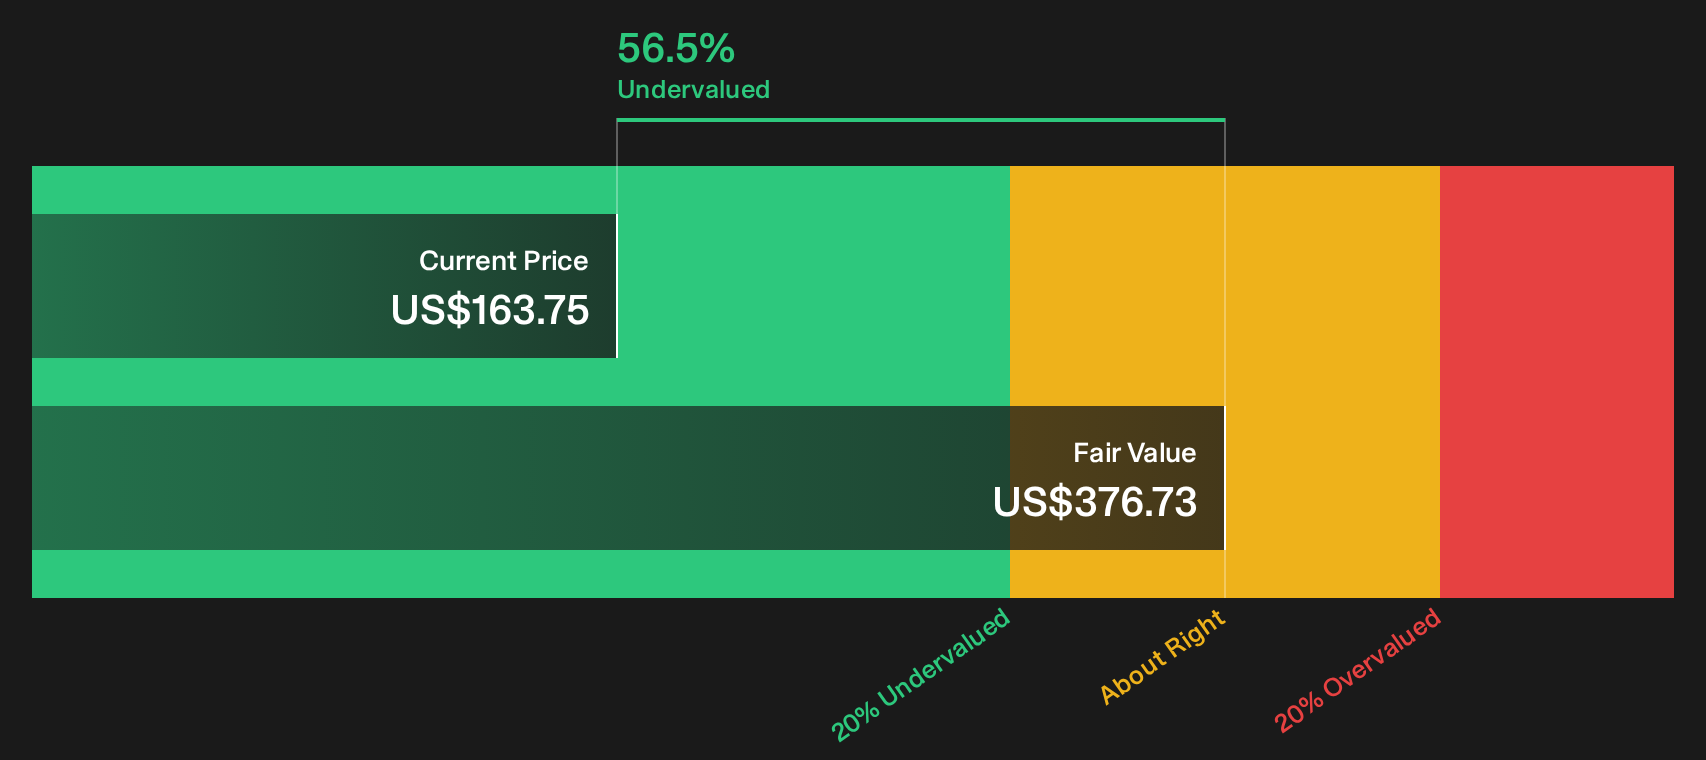
The first story around Glaukos leans heavily on long term forecasts and a fair value of $196.46. A very different picture comes from our DCF model, which points to a future cash flow value of $376.73 and describes the stock as deeply undervalued based on that approach.
The gap between price and modeled cash flows raises a simple question. Are the growth and profitability paths embedded in those cash flow assumptions realistic for you, or does this signal more optimism than you are comfortable with?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Glaukos valuation can be confusing. Move quickly, review the underlying numbers, then weigh the 1 important warning sign against the 3 key rewards and 1 important warning sign flagged in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Glaukos?
If Glaukos has you thinking differently about what is already priced in, do not stop here. Fresh ideas often appear where the market pays less attention.
Use the Simply Wall Street Screener to scan for new opportunities that match your risk profile and goals before others spot them.
- Target potential mispricing by reviewing a curated set of 31 high quality undervalued stocks that pair quality fundamentals with appealing entry points.
- Prioritise resilience by filtering for a list of solid balance sheet and fundamentals (25 results) that can better handle funding pressure or earnings volatility.
- Get ahead of the crowd by checking a focused group of 19 high quality undiscovered gems that have strong underlying metrics but limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com