


Amazon.com (AMZN), Is There More To Its Latest Attention?
Amazon.com (AMZN) is back in the labor spotlight after warehouse employees at its SWF1 facility in Rock Tavern, New York, walked off the job over safety concerns and unfair productivity discipline.
Against this backdrop, Amazon.com’s recent share price moves have been relatively steady, with a 1-day share price return of 1.33% and a 90-day share price return of 3.01% supporting an 11.05% year-to-date gain. The 3-year total shareholder return of 96.56% points to momentum built over a longer stretch, despite shorter term share price softness such as the 30-day return declining 2.70%.
Stress test how you think about Amazon.com’s labor and logistics risks by scanning other large retailers and logistics operators screened as 31 resilient stocks with low risk scores in one place.
Amazon.com has eased higher this year, yet the recent 30 day slip and fresh labor flashpoints leave a practical choice: lean into today’s price, or wait and see what the valuation says about patience.
Most Popular Narrative: 47% Undervalued
On price alone, Amazon.com last closed at $251.52, while the most followed valuation story on Simply Wall St puts fair value nearer to $475.09, which frames the current share price as a sizable discount in that narrative.
Amazon is a company of two sides: a high tech, high margin side, comprising its AWS, Advertising and subscription services segments, and its more traditionally known low margin, high volume stores and third-party seller segments. These two sides form a cohesive whole. The Amazon online store motivates customers to purchase subscriptions and hosts its advertising. AWS underpins the functioning of the online store, but is also easy to integrate with for Amazon's many third-party sellers, encouraging adoption.
See why 275 investors see Amazon.com as 47% undervalued.
Result: Fair Value of $475.09 (UNDERVALUED)
Still, the Amazon.com narrative leans heavily on AWS and higher margin services, so any slowdown in those areas or prolonged retail labor disputes could challenge those assumptions.
Find out about the key risks to this Amazon.com narrative.
Another View On Amazon.com’s Valuation
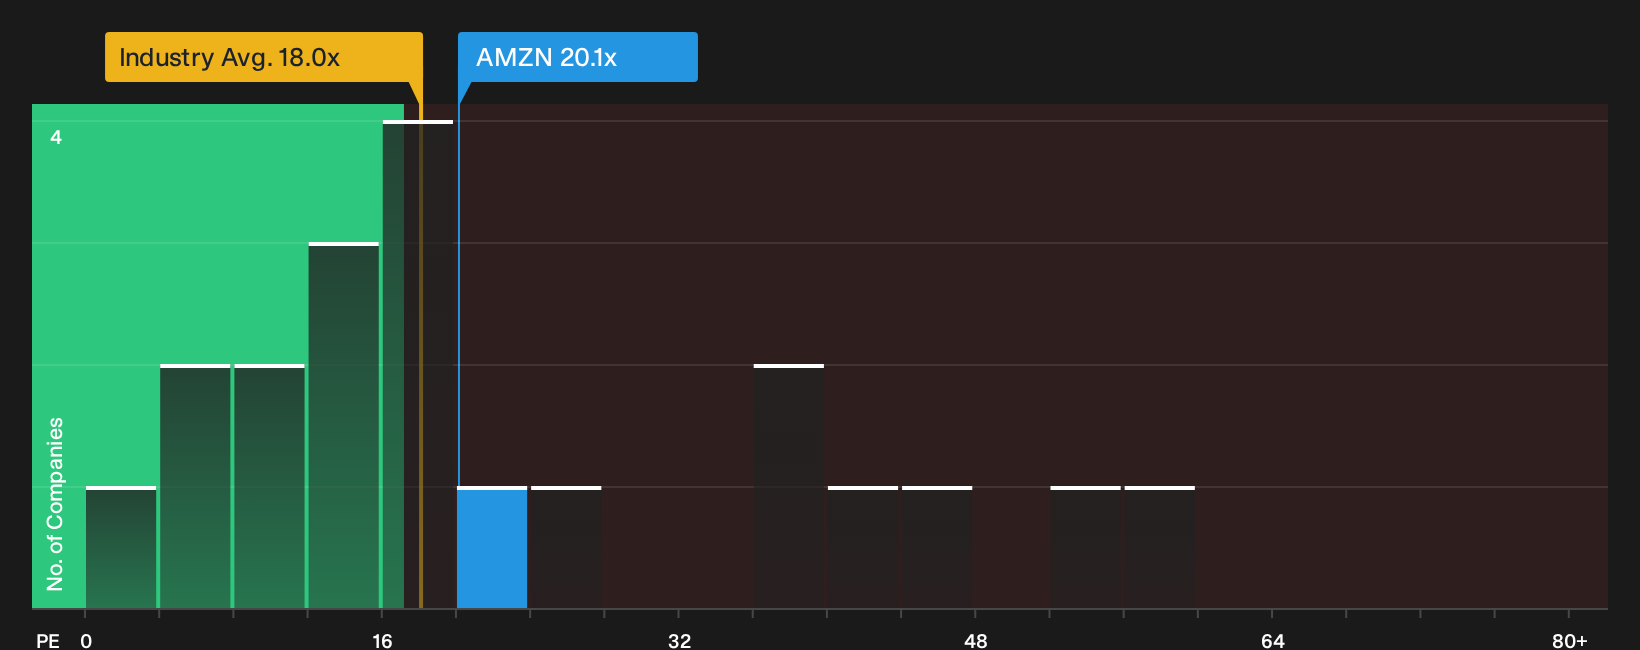
There is a different story when looking at Amazon.com through its P/E ratio. The stock trades at 20.1x earnings, richer than the global Multiline Retail average of 18x, yet below peers at 24.9x and the fair ratio of 29.2x. This mix raises the question of whether the valuation provides a degree of safety or creates pressure if expectations slip.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about Amazon.com after reading this? Act while the details are fresh and weigh both sides by reviewing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Amazon.com?
Do not stop at Amazon.com. Put this momentum to work by lining up a few fresh watchlist candidates while the details of this analysis are still clear.
- Target long term upside potential by scanning a focused set of quality companies that screens as 19 high quality undiscovered gems.
- Strengthen your core holdings with financially resilient businesses highlighted in the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by reviewing the 31 high quality undervalued stocks before prices shift away from you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com