


Savaria (TSX:SIS) Could Be 14% Undervalued As Dividend Rises 5.36%
Savaria (TSX:SIS) has drawn fresh attention after announcing a 5.36% increase to its monthly dividend starting in October 2026, linking the higher payout to record adjusted EBITDA, low net debt, and strong operating cash flow.
Recent trading has broadly supported that dividend message, with Savaria’s share price up 3.18% on the day, 6.50% over the past month, and 30.66% year to date. Long-term total shareholder returns of 47.88% over one year and 134.63% over three years point to momentum that investors continue to reward.
Scan other income-focused stocks that show a similar mix of dividend growth, earnings coverage, and cash generation with our hand picked 1 dividend fortresses.
Some investors now see Savaria’s higher dividend and cash generation as proof the stock deserves a richer multiple. Others view the recent run as froth. Which side do the current valuation gauges lean toward?
Most Popular Narrative: 14% Undervalued
Compared to Savaria’s last close at CA$30.13, the most followed narrative pegs fair value at CA$35.00, implying a discount that many investors are now weighing against the recent share price run and the richer dividend.
Strong balance sheet and expanding free cash flow provide firepower for strategic M&A and global expansion, supporting revenue diversification and underpinning expectations for above-market earnings growth as international demand accelerates.
See why 78 investors see Savaria as 14% undervalued.
Result: Fair Value of CA$35.00 (UNDERVALUED)
Still, if government subsidy cuts deepen in Europe or new offerings like Luma and VPL Multi Lift take longer to gain traction, Savaria’s upbeat thesis could soften.
Find out about the key risks to this Savaria narrative.
Another View: Multiples Put Savaria In Context
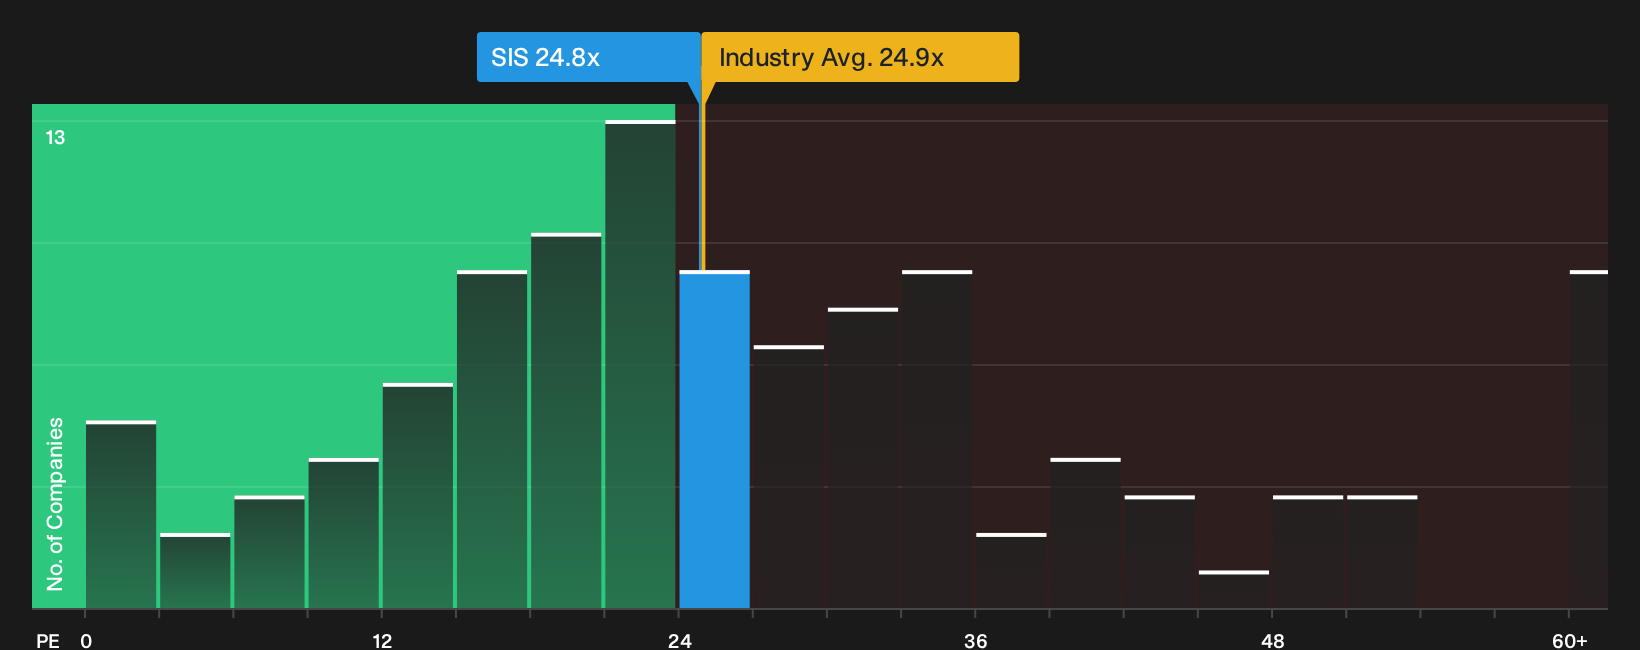
There is a catch. While the SWS DCF model flags Savaria as trading about 39% below an estimated fair value of CA$49.41, the current P/E of 24.8x sits above a fair ratio of 20x, even though it is roughly in line with the North American Machinery sector at 24.9x and below peers at 36.3x. Is that a margin of safety or a sign expectations are already rich?
For investors who lean more on earnings multiples than cash flow models, this kind of comparison can help frame whether today’s P/E leaves much room for error or already prices in the optimism embedded in the most popular narratives about Savaria, which is where the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear opportunity? Take a closer look at Savaria, review the full picture, and weigh both sides with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Savaria?
If Savaria has sharpened your focus on quality opportunities, do not stop here. Broader idea hunting with focused screeners can reveal what you might otherwise miss.
- Target resilient income by reviewing companies in our 1 dividend fortresses that pair higher yields with balance sheets designed to support ongoing distributions.
- Hunt for value by scanning the 6 high quality undervalued stocks where pricing and fundamentals align to flag potential mispriced opportunities.
- Prioritize capital preservation by checking the 8 resilient stocks with low risk scores and see which businesses score well on stability before sentiment moves ahead of you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com