


EuroCTP Launch Could Strengthen The Case For EPAM Stock
- EPAM Systems reported that it co-architected, built and delivered the cloud-native portion of EuroCTP's hybrid infrastructure, supporting the European Union's first mandated consolidated tape for shares and ETFs that has been live since 14 September 2026.
- The engagement gives EPAM Systems a central role in real-time market data processing, from low-latency analytics using its TimeBase database to client-facing portals and FIX-based outbound connectivity. This speaks directly to its execution capabilities in complex, regulated financial workflows.
- We will now see how EPAM Systems' role in EuroCTP's real time tape infrastructure could influence the broader investment narrative.
Scan how EPAM Systems' EuroCTP role compares with other high quality automation and data plumbing plays by reviewing the curated 90 robotics and automation stocks shaping real time infrastructure across markets.
EPAM Systems Investment Narrative Recap
To own EPAM Systems, you need to believe the consultancy can keep shifting work toward complex, AI native and data heavy projects where its engineering roots matter. The EuroCTP win fits that story by showcasing real time data and cloud expertise in a regulated setting. It is helpful proof of capability, but by itself it does not change the near term revenue picture.
The immediate swing factor stays the same. EPAM Systems still needs to re accelerate North American activity while getting free cash flow back in line with earnings after recent quarterly losses and softer conversion guidance. If macro caution or slower client decisions persist, this EuroCTP role will not offset those headwinds.
The EuroCTP launch is arguably the most relevant recent development for this narrative. It shows EPAM Systems winning a high stakes infrastructure role in European market data, with work spanning cloud architecture, low latency analytics using its TimeBase database and client facing interfaces. That aligns closely with analyst focus on AI and data centric transformation programs.
For you as an investor, the interest is how this type of deal could feed into the existing pipeline of large AI led and vendor consolidation opportunities, especially in regulated sectors. Execution on EuroCTP may help EPAM Systems argue for similar multi year, mission critical mandates, although the main operational tests remain revenue progress in North America and normalization of free cash flow.
EPAM Systems' narrative projects US$6.3b revenue and US$539.8m earnings by 2029. This implies 4.1% yearly revenue growth and an earnings increase of about 34% from US$401.7m today.
Uncover how EPAM Systems' fair value indicates a 13% potential upside to its current price before the market closes the gap.
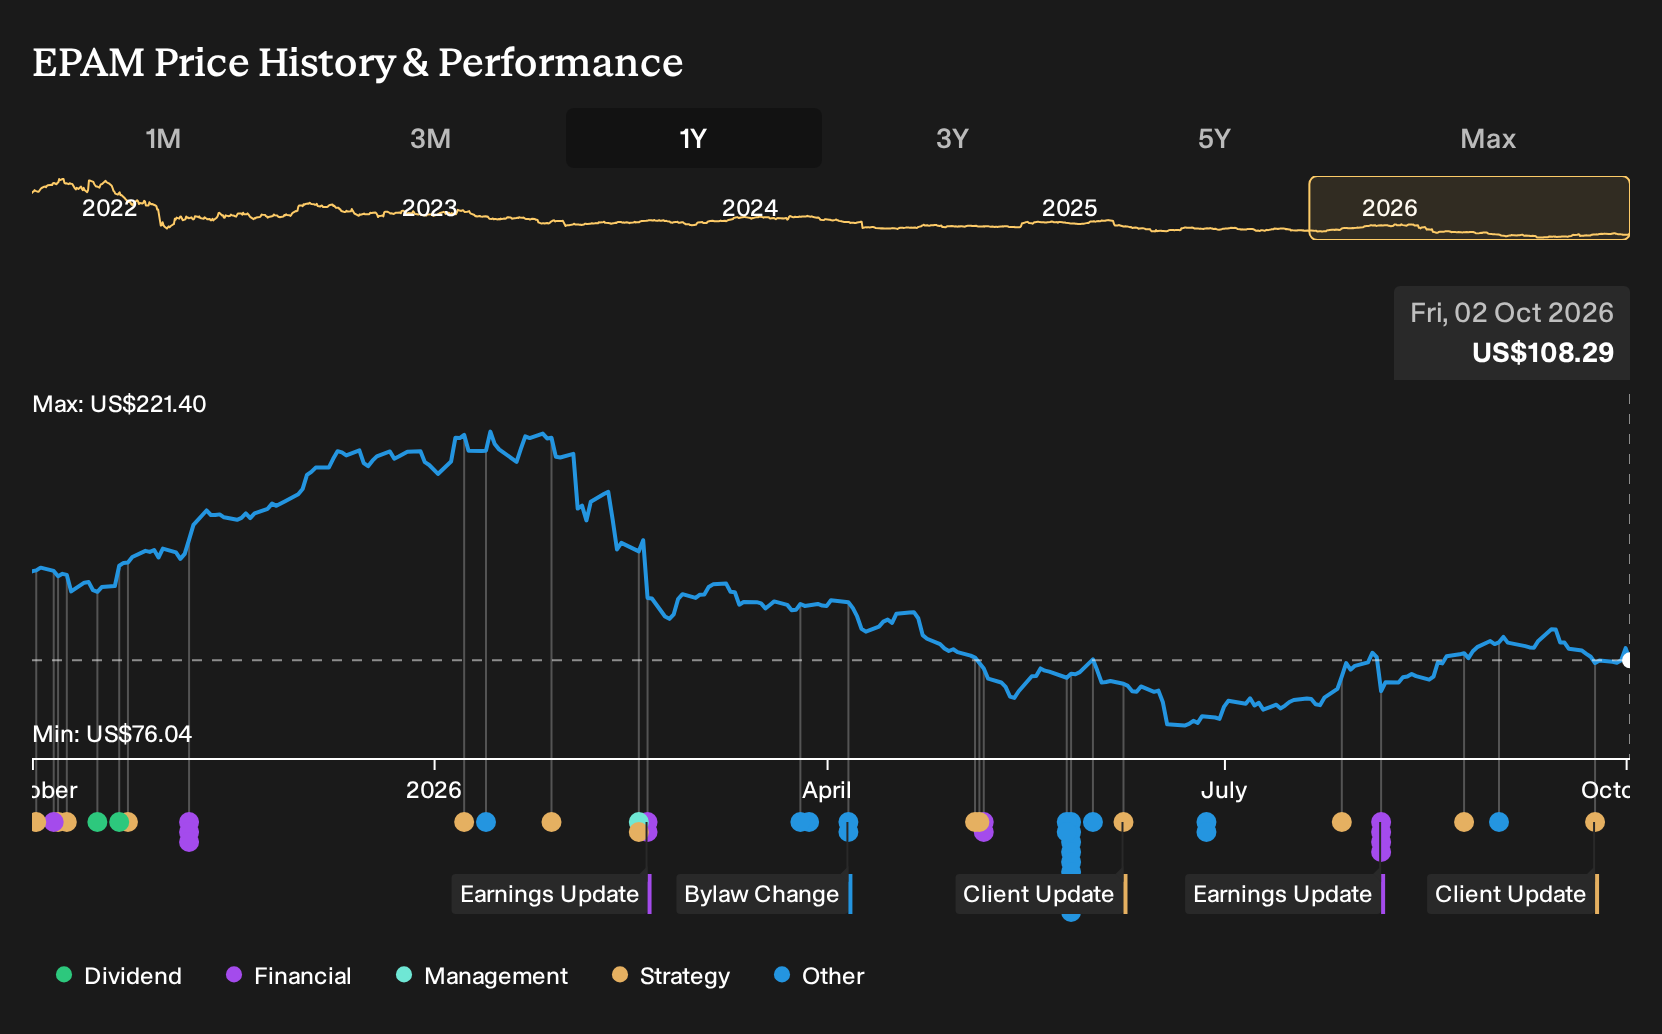
Exploring Other Perspectives
One alternative view focuses on pricing risk. Some of the lowest EPAM Systems forecasts still saw only 3.1% yearly revenue growth and about US$529.8m in earnings by 2029, paired with a 9.7x P/E. That cohort looked for continued pressure in North America. You can now ask whether the EuroCTP win shifts those expectations.
Explore 6 other EPAM Systems fair value estimates, including one that suggests it could be worth just $107.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EPAM Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for EPAM Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EPAM Systems' overall financial health at a glance.
Looking for more EPAM Systems sized ideas?
If the EuroCTP story has sharpened your interest in data heavy platforms and real time infrastructure, it can help to line EPAM Systems up against a wider watchlist. The Simply Wall St Screener lets you filter for very different types of opportunities so you keep your portfolio grounded in clear criteria instead of headlines.
- For investors who want potential upside with tighter risk controls, consider scanning a curated 31 resilient stocks with low risk scores to help keep volatility and financial stress in check.
- If dependable balance sheets matter most to you, work through the list of solid balance sheet and fundamentals (26 results) to focus on businesses with stronger fundamentals behind their stories.
- When the goal is to uncover less crowded ideas, use the 19 high quality undiscovered gems that combine solid underlying metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com