


Learn Why The Bull Case For Insperity (NSP) Could Change Following HRScale Rollout Progress
- Insperity reported continued progress with its HRScale solution, which combines Workday technology with the company’s full-service PEO for rapidly growing and midsized businesses, and highlighted that early adopters are seeing faster, more cost-effective HR, payroll and workforce management implementations.
- The 3Sixty Insights research cited by Insperity underscores a key gap: most organizations underuse their HCM platforms, and almost half say they would pay more for better support, which directly aligns with HRScale’s service-plus-technology approach.
- We will now look at how Insperity's investment narrative could be influenced by HRScale’s push to improve HCM utilization and support.
Insperity Investment Narrative Recap
For an investor to stay with Insperity, the core belief is that demand for bundled HR and compliance support from small and midsized employers continues, and that technology driven offerings such as HRScale improve efficiency enough to matter. The recent HRScale progress update supports that operating story but does not by itself change the near term focus on restoring profitability from a current loss of US$16.0 million.
The near term swing factor still sits in benefits and healthcare costs and how effectively Insperity aligns pricing and plan design with those trends. HRScale’s early traction helps address execution risk around the Workday partnership and the multi year investment tied to it. Competitive pressure, SMB cyclicality and the dividend not being covered by earnings remain key operational watchpoints.
The HRScale ramp is the announcement that ties closest to the existing catalyst list. Analysts already framed the Workday partnership as a way to reach larger mid market clients and potentially support better operating leverage. Evidence that early adopters are seeing faster, more cost effective deployments suggests the combined service and software model is functioning operationally as described.
For catalysts, the interesting link is between HRScale and the effort to manage healthcare and compliance complexity for clients. If more midsized customers move to a service enabled HCM platform and experience fewer HR and benefits incidents, Insperity may build stronger retention and pricing power over time. That could help offset risks from competition, SMB exposure and the sizable capital committed to the Workday relationship.
Insperity's analyst narrative assumes revenues reach US$7.7b and earnings reach US$145.3 million by 2029. That profile relies on 3.7% yearly revenue growth and an earnings swing of about US$161 million from a loss of US$16.0 million today to the 2029 consensus figure.
Uncover why Insperity's fair value indicates an 11% potential upside to its current price that may not last much longer.
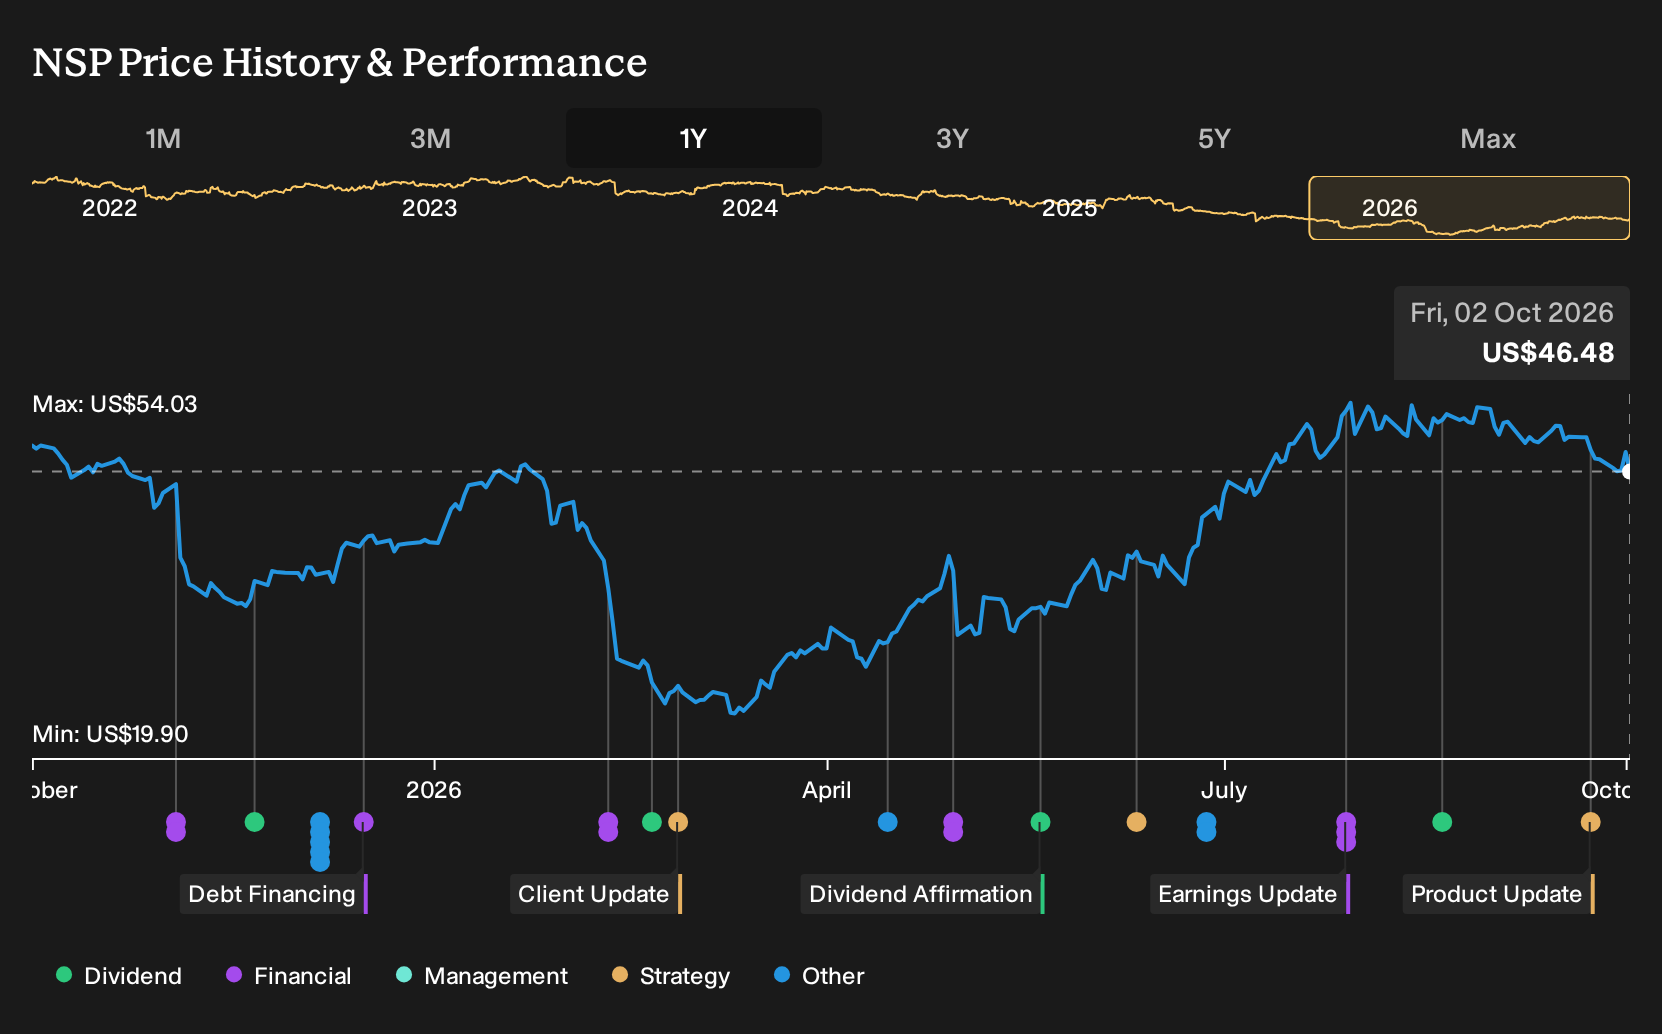
Exploring Other Perspectives
You are seeing one very optimistic angle around Insperity’s margin recovery story. The most bullish analysts were already baking in revenue of about US$7.8b and earnings of roughly US$147.8 million by 2029, slightly above the consensus US$7.7b and US$145.3 million. This new HRScale progress update could push those views even further apart.
Explore 3 other Insperity fair value estimates, including one that suggests potential upside of up to 265% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Insperity research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Insperity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insperity's overall financial health at a glance.
Looking For More Investment Ideas Beyond Insperity?
If the Insperity story has you thinking about where else bundled services, strong balance sheets, or steady income streams might show up, it can help to widen the search across a broader watchlist using the Simply Wall St Screener.
- For investors who want potential upside with smaller companies, review a focused group of 9 elite penny stocks with strong financials that already clear basic quality hurdles.
- If capital preservation matters most to you, scan a 31 resilient stocks with low risk scores that screens for businesses with more resilient financial and risk profiles.
- For readers aiming to build a steadier income stream, shortlist a 7 dividend fortresses that may help support more reliable cash returns from the portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com