


Quantum (QMCO) Gets A Turnaround Test Following COO Hire And A Pricey Valuation Narrative
Quantum (QMCO) has drawn fresh attention after appointing James C. Clancy as Chief Operating Officer, a veteran of Dell and Dell EMC with deep experience in data protection and enterprise storage.
Recent trading has been brisk, with Quantum’s share price up 51.45% over the past 30 days and delivering a 239.57% 90 day share price return. The 1 year total shareholder return of 193.37% contrasts with a 5 year total shareholder return that declined 66.76%.
Compare Quantum’s surge under new leadership with hand picked peers by scanning 19 high quality undiscovered gems that are also drawing attention for their transformation potential.
Bulls see Quantum’s surge and new COO as the start of a credible turnaround. Bears point to the loss-making profile and long term value erosion. Which side do the current valuation markers lean toward next?
Most Popular Narrative: 30% Overvalued
Quantum closed at $34.50 against a narrative fair value of $26.50, so the most followed thesis views the recent surge as richly priced and demanding cleaner execution.
The analysts have a consensus price target of $26.5 for Quantum based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $512.2 million, earnings will come to $71.0 million, and it would be trading on a PE ratio of 23.1x, assuming you use a discount rate of 8.6%.
See why 15 investors see Quantum as 30% overvalued.
Result: Fair Value of $26.50 (OVERVALUED)
Still, the narrative can crack if Quantum struggles to move from heavy losses on US$296.1 million of revenue, or if extended supply chain lead times choke conversion of record demand.
Find out about the key risks to this Quantum narrative.
Another View On Quantum’s Valuation
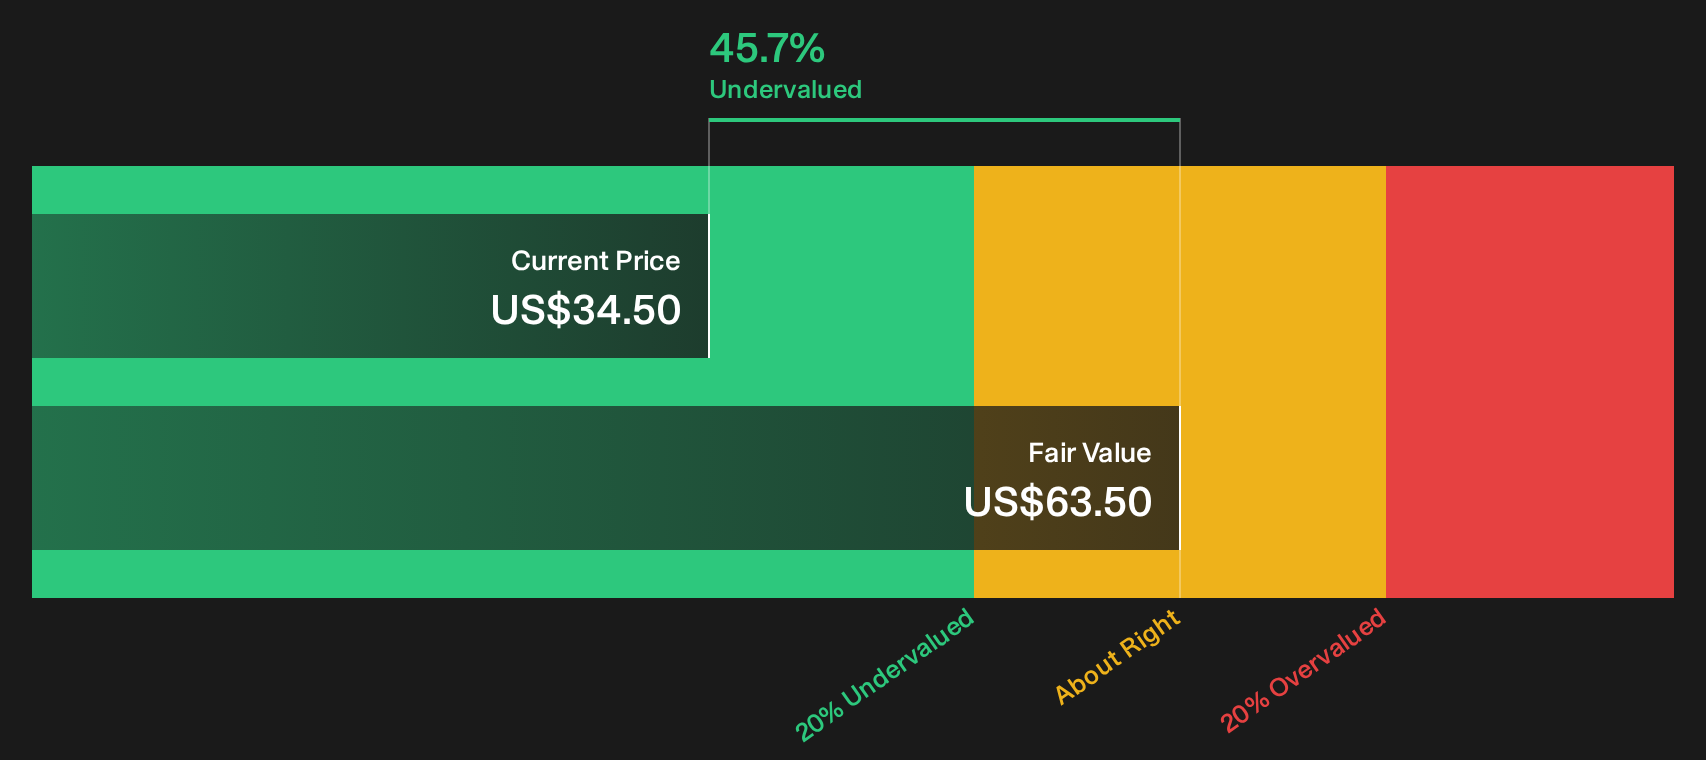
The fair value narrative anchored on $26.50 suggests Quantum is 30% overvalued, yet our DCF model points in the opposite direction. Based on projected future cash flows, the SWS DCF model places fair value closer to $63.50, which frames the current $34.50 price as materially below that estimate. Which story feels more realistic to you: a multiple based on 2029 earnings assumptions, or a cash flow path that already incorporates execution risk?
For readers who want to see how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Quantum for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Quantum is split, so consider acting promptly, review the underlying data, and weigh the 2 key rewards and 4 important warning signs against your own expectations for the business.
Looking for more Quantum and market ideas?
If Quantum has your attention, do not stop here. Broaden your watchlist with fresh opportunities that match your risk profile, income goals, and quality filter.
- Target steady compounding by scanning a 31 high quality undervalued stocks list that blends strong fundamentals with prices that sit below their estimated worth.
- Secure potential income streams by reviewing a 7 dividend fortresses that focuses on high-yield payers with an emphasis on resilience.
- Dial down portfolio stress by checking a 31 resilient stocks with low risk scores that filters for businesses with more robust financial and risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com