


Earnings Upgrade Might Change The Case For Investing In BJ's Stock (BJRI)
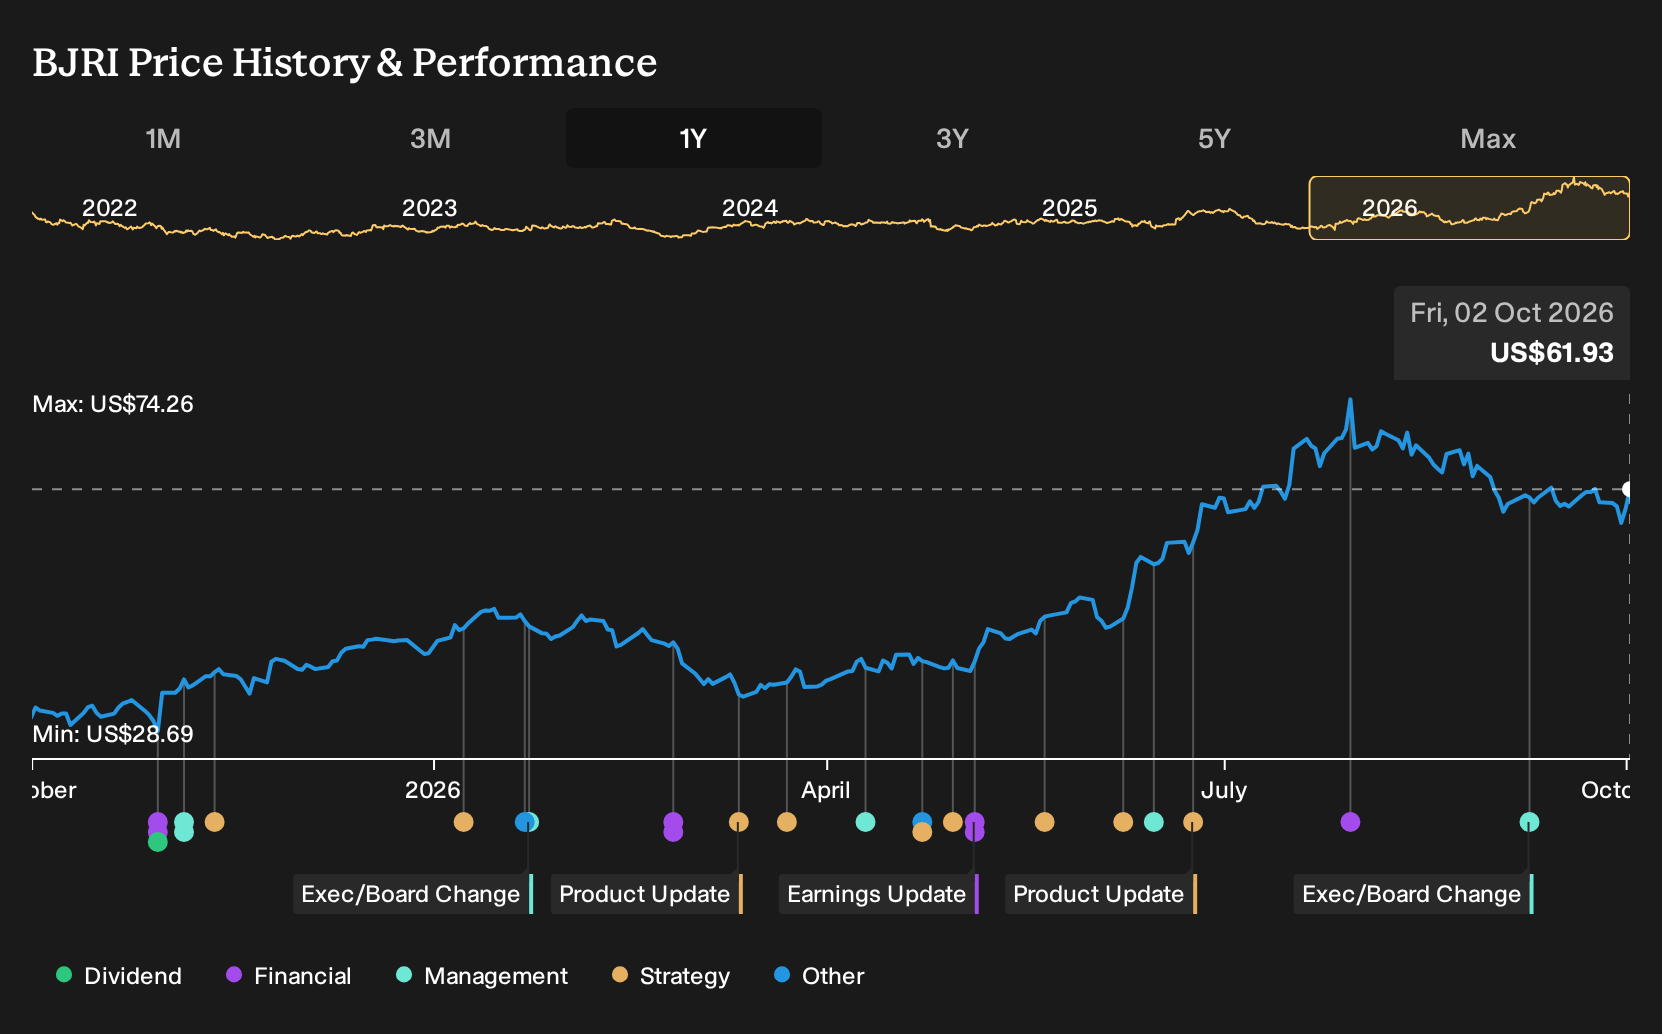
- BJ's Restaurants recently received higher full year earnings estimates, with forecasts raised by 7.4% over the past 90 days alongside a Zacks Rank of #2.
- The business has outperformed both Retail Wholesale peers and the broader restaurant group, which points to investor focus on its operating outlook rather than sector weakness.
- We will now look at how BJ's Restaurants' upgraded earnings outlook could reshape the longer term investment narrative around the chain.
Scan how BJ's Restaurants compares with other resilient consumer stocks by running the curated 31 resilient stocks with low risk scores that filters for companies with sturdier risk profiles.
BJ's Restaurants Investment Narrative Recap
For BJ's Restaurants, the big picture you would need to believe in is fairly clear. The chain has to keep getting more out of each dining room through menu platforms like Pizookie deals, tighter labor models, and smoother digital ordering, rather than relying on rapid new unit growth. The recent earnings upgrade reinforces confidence in that operating formula but does not change it.
The near term swing factor is margin execution. Labor and food costs sit on one side, while guest traffic, check size, and off premise orders sit on the other. A key risk is that slower progress in digital and delivery, or a shift away from heavy comfort food, could affect that balance.
Recent commentary around BJ's Restaurants has centered on expected earnings growth and margin improvement tied to operational projects. That links directly to this upgraded outlook. Activity based labor, better forecasting, and tech upgrades are already built into the story and help explain why analysts see room for earnings expansion from here.
Another important thread is the focus on digital and off premise channels. Management has been investing in online ordering and menu optimization for takeout and delivery, which matters if guests lean more into at home dining. Execution here can support the current earnings momentum, while slow progress would leave the business more exposed to rising wage and occupancy costs.
BJ's Restaurants is modeled to reach US$1.6b in revenue and US$72.0m in earnings by 2029, based on analysts assuming 4.4% yearly revenue growth and an earnings increase of about US$31.1m from US$40.9m today.
Discover how BJ's Restaurants' fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on BJ's Restaurants leans heavily on valuation risk. You have bearish analysts assuming revenue of roughly US$1.7b and earnings of US$69.9m by 2029, yet still landing at a US$65.0 price target. That points to a more cautious story, and the latest earnings upgrade could eventually lead to a shift in those narratives.
Explore another BJ's Restaurants fair value estimate, including one that suggests as much as 10% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BJ's Restaurants research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BJ's Restaurants. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BJ's Restaurants' overall financial health at a glance.
Looking for more BJ's Restaurants sized ideas?
Once you have a view on BJ's Restaurants, it can help to line that up against other potential opportunities. The Simply Wall St Screener gives you a quick way to scan for different profiles rather than getting stuck on a single story.
- For investors who care most about sturdier financial footing and lower volatility, start by comparing BJ's with companies highlighted in the 31 resilient stocks with low risk scores.
- If you prefer to focus on steadier cash returns from your portfolio, you can zero in on reliable income payers using the 7 dividend fortresses.
- Those hunting for mispriced opportunities with solid underlying fundamentals can broaden their watchlist with the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com