


3 Canadian Energy Stocks as Rising Fuel Prices Lift Cash Flow Potential
Spiking fuel and heating bills are squeezing Atlantic Canada just as global energy prices react to the U.S.-Iran conflict, and that stress is rippling through Canadian energy producers and infrastructure stocks. Some businesses may see stronger cash flows, others face demand risks if higher costs hit consumer spending harder. This article unpacks the backdrop and then walks through three stocks from the Canadian Energy Producers and Infrastructure screener most exposed to this news.
The three stocks below are only a small sample from this theme, and the full screen surfaced 11 more Canadian energy producers and infrastructure plays with equally compelling narratives that are not covered here. To identify and analyze the broader opportunity set, head straight to the Canadian Energy Producers and Infrastructure screener.
Total Energy Services (TSX:TOT)
Total Energy Services is one of the clearest picks in this Canadian Energy Producers and Infrastructure theme because it supplies the rigs, compression gear, and field services that oil and gas producers need when drilling and production activity tightens alongside higher fuel and heating prices.
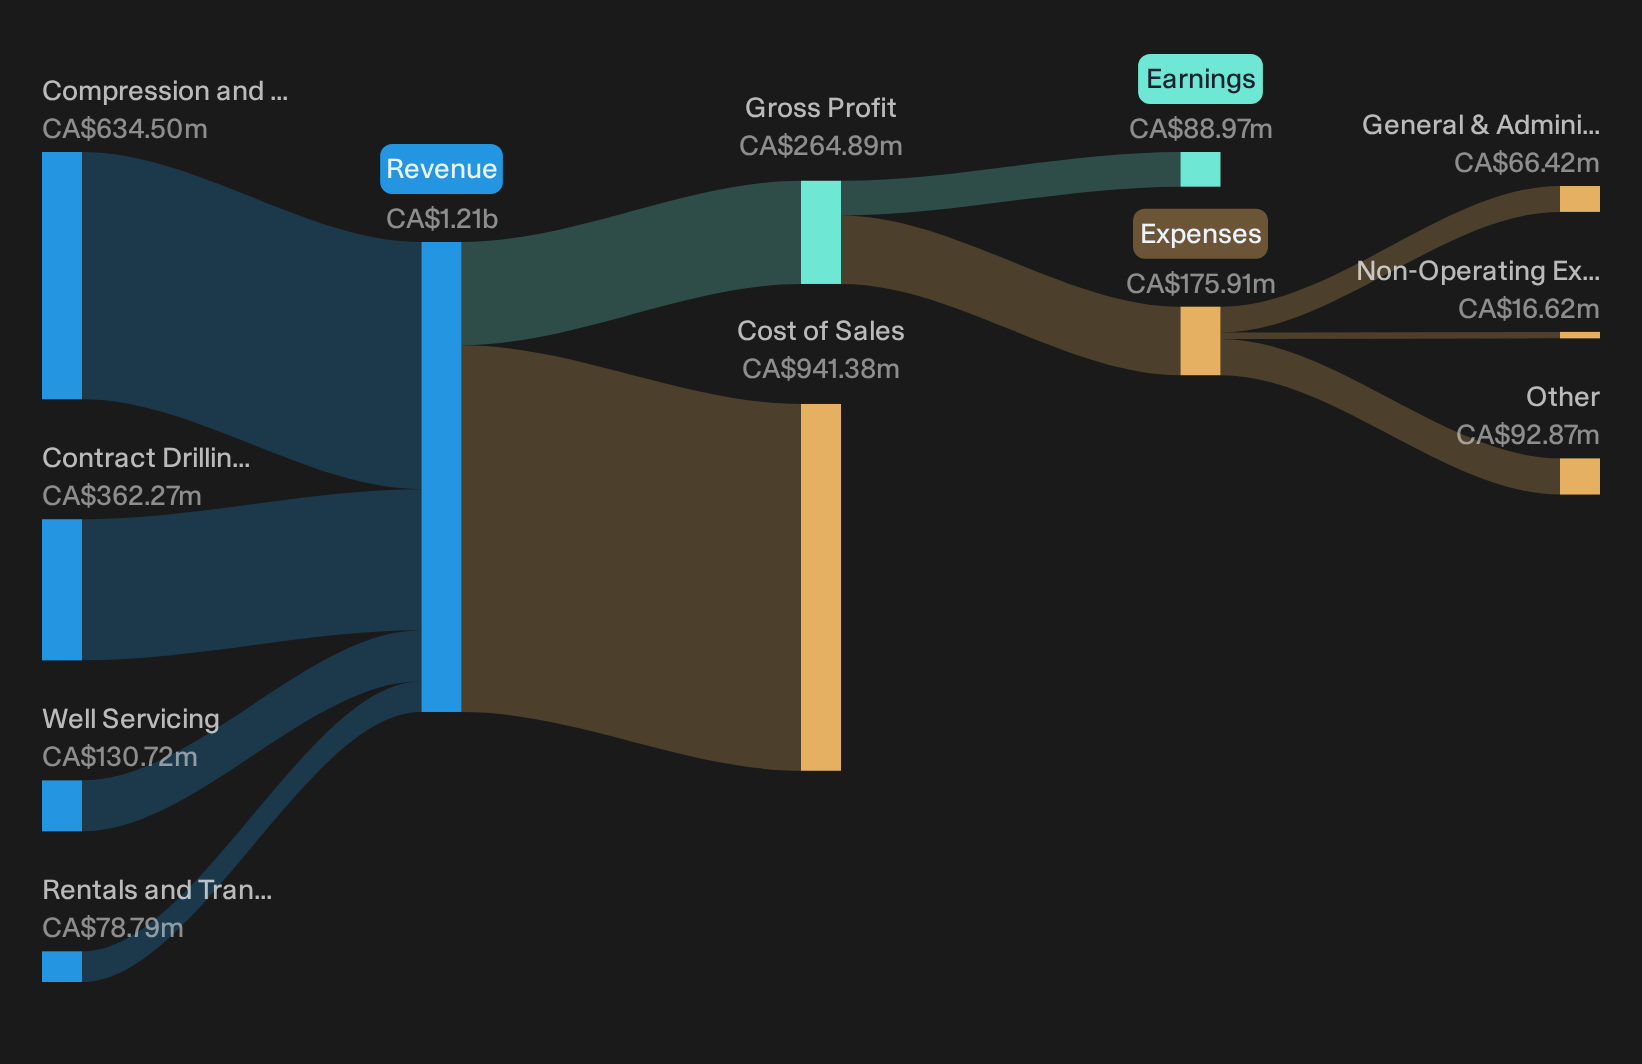
Total Energy Services runs four main segments, with Compression and Process Services generating about CA$634 million of revenue, Contract Drilling CA$362 million, Well Servicing CA$131 million, and Rentals and Transportation CA$79 million, and the group carries a market value of roughly CA$1.24 billion.
"The company is experiencing strong and growing demand for large-horsepower compression equipment, driven by the expansion of North American LNG export capacity and increased use of natural gas for power generation."
The real swing factor is what happens to margins and contract pricing if one less visible pressure on service capacity tightens further from here.
If that pressure keeps building, read the full narrative for Total Energy Services to see how Total Energy Services could turn tightening capacity into pricing power, contract quality, and resilience.
Cardinal Energy (TSX:CJ)
Cardinal Energy is one of the purest plays in this Canadian Energy Producers and Infrastructure theme. It earns all its money pulling petroleum and natural gas out of Western Canadian fields that feed directly into the same fuel and heating markets now under pressure.
Cardinal Energy generated about CA$550 million from its Oil and Gas Exploration and Production business in Canada and has a market value near CA$2.1b. As a result, movements in commodity prices feed straight into its top line and equity value.
Investors looking for producers most tightly tied to fuel and heating price swings often end up circling back to Cardinal Energy before long.
"Low debt, with room to issue more to cover dividend or existing growth project if needed by YE 2025 as a low fiscal risk position."
What that balance sheet really means for future cash returns and growth hinges on how one pressure point in the oil market resolves.
That pressure point is exactly where the story gets interesting, and the full narrative for Cardinal Energy shows how Cardinal Energy could turn balance sheet flexibility into accelerating optionality for investors.

Strathcona Resources (TSX:SCR)
Strathcona Resources is one of the purest ways to play the Canadian Energy Producers and Infrastructure theme, with heavy oil and thermal barrels feeding directly into the same crude and natural gas pricing that is pushing fuel and heating costs higher across the country.
Strathcona Resources focuses on Canadian oil and gas, with Cold Lake generating about CA$2.2b of revenue, Lloydminster Thermal CA$1.1b, Lloydminster Conventional CA$649 million, and Corporate and Midstream CA$131 million, all from Canadian operations, and the business carries a market cap near CA$8.3b.
"The acquisition of the largest crude-by-rail terminal in Western Canada not only hedges against WCS differential volatility, but also positions Strathcona to benefit from potential market access constraints and potential premium pricing events, supporting above-peer free cash flow and earnings resilience even in challenging takeaway scenarios."
What ultimately matters for Strathcona Resources is how one less visible pressure on future thermal oil profitability resolves as fuel and heating prices stay in focus.
If that pressure starts to shift margins or capital plans, the full narrative for Strathcona Resources lays out how Strathcona Resources could turn rail capacity into accelerating, less correlated cash generation.

Seeking Fresh Alternatives Before Others?
Markets move fast and the best breakout stories rarely stay under the radar for long. Scan fresh ideas with real momentum before the crowd catches up and act now.
- Spot income opportunities that could steady your portfolio and still keep it moving with yield by running the 1 dividend fortresses.
- Hunt for under followed operators that pair quality balance sheets with falling valuations using the curated 6 high quality undervalued stocks.
- Target potential future leaders in automation and factory efficiency while sentiment is still catching up through the focused 90 robotics and automation stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com