


LTC Properties (LTC) Recasts Its Portfolio On Senior Housing Deal As Valuation Stays In Focus
LTC Properties (LTC) has drawn fresh attention after agreeing to pay nearly $160 million for three senior housing communities, while selling two non SHOP portfolios for more than $260 million.
Investors have rewarded this portfolio reshaping, with LTC Properties’ share price up 24.1% year to date and supported by a 26.84% 1 year total shareholder return. A 64.33% 3 year and 83.27% 5 year total shareholder return hint at momentum building over a longer horizon.
Scan how LTC Properties compares with other income-focused real estate plays by reviewing our hand picked group of 7 dividend fortresses sitting at the crossroads of yield and resilience.
LTC Properties has already banked a strong run on the back of its portfolio reshaping. The real tension now is whether recent buyers have captured most of the upside or if the valuation still leaves meaningful room ahead.
Most Popular Narrative: 4% Undervalued
LTC Properties closed at $43.00 against a widely followed fair value view of $45, which frames the current debate around how much of the repositioning story is already reflected in the price.
The company's ability to recycle capital out of older skilled nursing assets (via portfolio sales and potential loan prepayments) and redeploy proceeds into higher-yielding, modern properties enhances rent growth potential and operating efficiency, which supports higher net margins and long-term NAV growth.
See why 48 investors see LTC Properties as 4% undervalued.
Result: Fair Value of $45 (UNDERVALUED)
Still, the LTC Properties story can falter if acquisition prices compress returns, or if tenant concentration leaves earnings exposed to a few key operators.
Find out about the key risks to this LTC Properties narrative.
Another View On What LTC Properties Is Worth
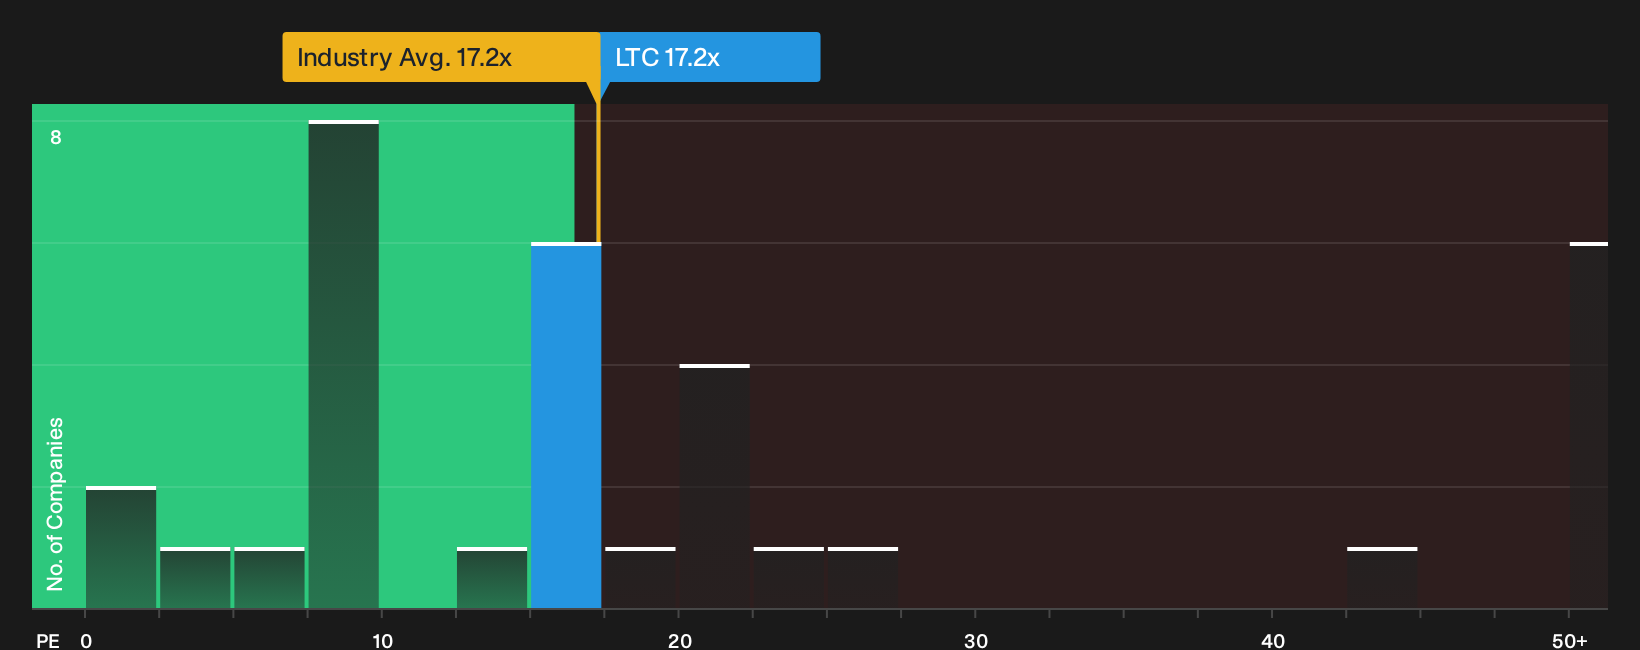
The first fair value anchor around $45 leans on future cash flow and narrative. A simpler cross check sits in the current P/E of 17.2x, which is almost identical to the global Health Care REITs average at 17.1x yet below a fair ratio of 26.3x.
That mix hints at a stock the market prices in line with the sector today, while leaving room for sentiment to move closer to the higher fair ratio over time. This could be upside or a value trap depending on how the senior housing story unfolds.
To stress test that trade off against hard numbers, it is worth digging into how the current P/E compares with peers and where the fair ratio suggests pricing could drift, especially if LTC Properties keeps recycling capital at similar terms to recent deals. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment on LTC Properties feels mixed after this, that is the point. Act while the facts are fresh and evaluate both the potential risks and rewards using the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond LTC Properties?
Do not stop your research with LTC Properties. Use fresh screeners to widen your opportunity set and assess whether this stock truly earns a place in your portfolio.
- Target potential mispricing by reviewing a curated spread of 31 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Strengthen portfolio resilience by scanning a list of solid balance sheet and fundamentals (26 results) that can help you lean toward sturdier financial profiles.
- Pursue reliable income by comparing LTC Properties with a hand picked group of 7 dividend fortresses designed for investors who want yield without ignoring quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com