


Did Earnings Beat Just Shift ScanSource (SCSC) Investment Narrative?
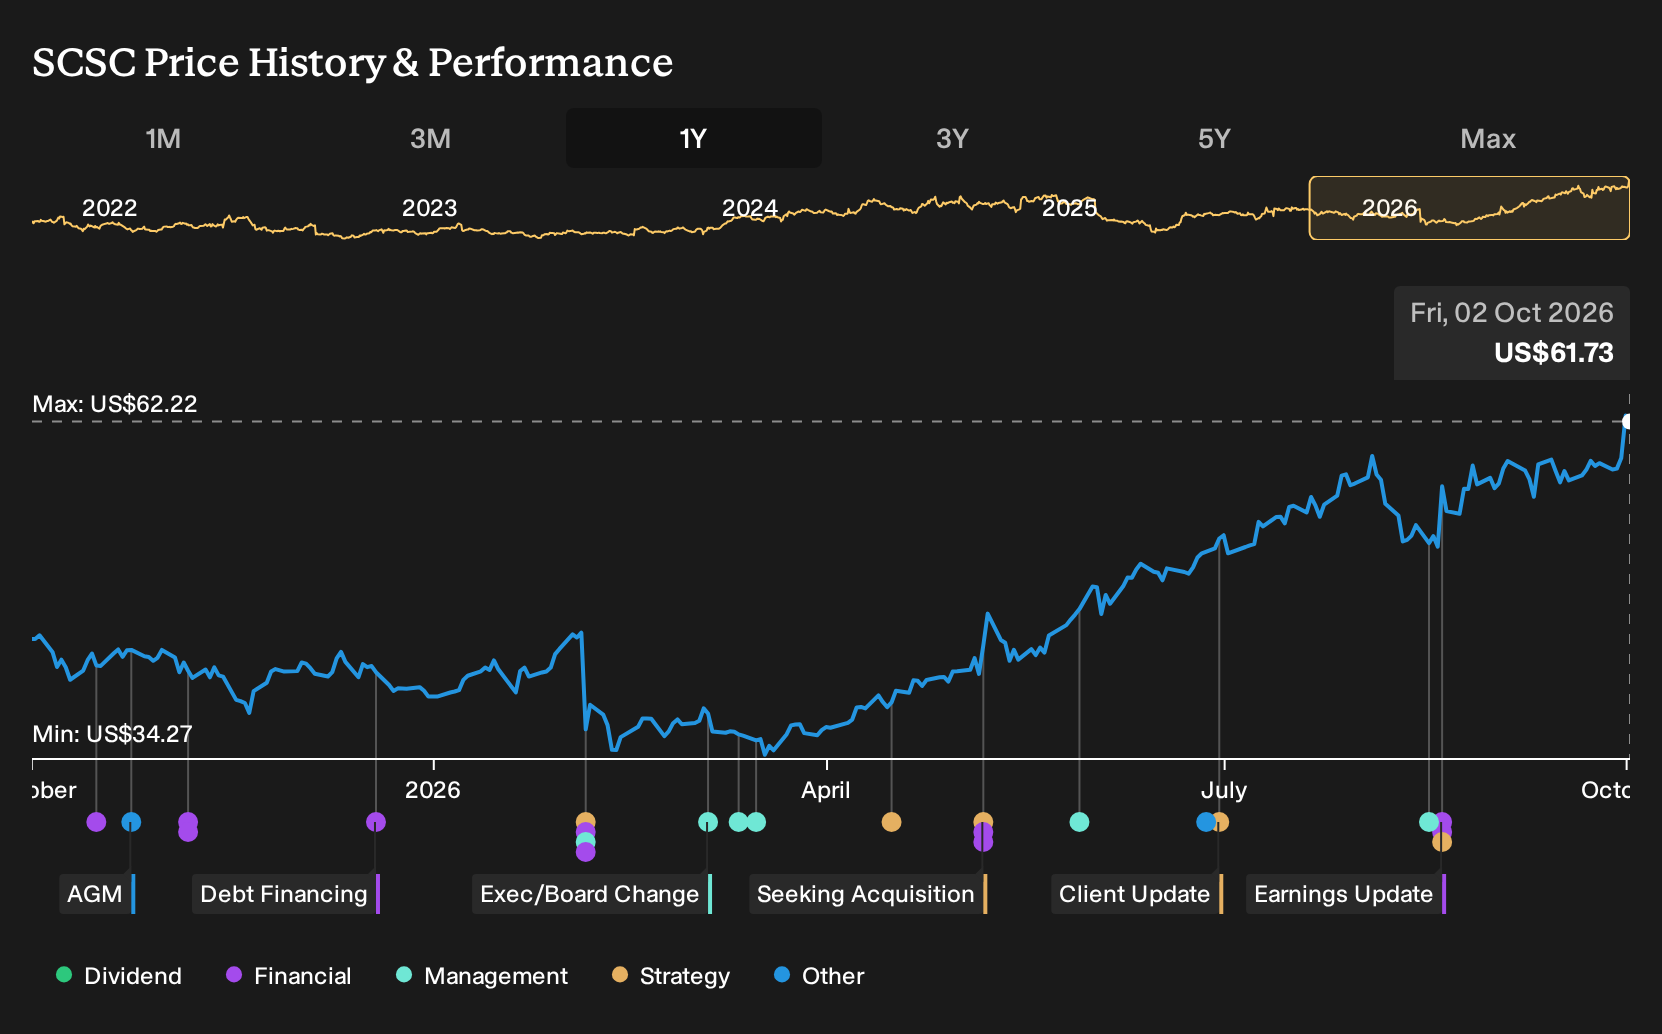
- ScanSource recently reported quarterly revenue of US$953.1 million, which was 17.3% higher year on year and ahead of analyst expectations by 18.8%, alongside an EPS result that exceeded estimates.
- The company delivered the largest analyst estimate beat within its IT distribution and solutions peer group, which points to strong execution against demand across its portfolio rather than a one off uplift.
- We will now look at how ScanSource's investment narrative is shaped by this earnings beat and stronger than expected revenue performance.
Scan for more companies posting stronger than expected quarters, similar to ScanSource, by checking our curated 19 high quality undiscovered gems that have not yet drawn broad market attention.
ScanSource Investment Narrative Recap
To own ScanSource, you need to be comfortable with a distributor that is leaning harder into recurring IT, cloud and connectivity solutions while still relying heavily on hardware volumes. The recent revenue and EPS beat supports the idea that demand across those core categories is holding up, but it does not remove execution risk around mix, pricing, or working capital in the near term.
The key short term swing factor is how consistently ScanSource can convert this stronger demand into higher quality, recurring gross profit, especially within Intelisys and advisory services. The biggest current risk remains integration and execution around newer focus areas like cloud, security and AI services, where any slowdown or misstep could affect margins.
The planned MicroAge acquisition sits closest to this earnings story. ScanSource has demonstrated performance relative to expectations on its existing portfolio, and MicroAge adds more exposure to cloud, cybersecurity, data center and AI services that sit closer to where partners are pushing their own customers.
What matters now is how cleanly MicroAge is folded into the platform. Effective integration, channel alignment and retention of key partner relationships could reinforce the shift toward higher recurring and services heavy revenue, while any disruption or cost overruns would make that transition bumpier and introduce more short term volatility around profitability.
ScanSource's narrative projects US$4.0b revenue and US$111.0 million earnings by 2029. This rests on analysts assuming 7.8% yearly revenue growth and an earnings increase of about US$32.1 million from US$78.9 million at present.
Uncover why ScanSource's fair value indicates a valuation gap that is approximately aligned with its current price.
Exploring Other Perspectives
One alternative view on ScanSource focuses on the risk that hardware stays too important for too long. The most optimistic analysts were already baking in about US$4.3b of revenue and US$115.7 million of earnings by 2029 before this surprise quarter, so you can see how far opinions stretch. Use this beat as a prompt to compare those assumptions with your own.
Explore 4 other ScanSource fair value estimates, including one that suggests up to 26% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ScanSource research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ScanSource. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ScanSource's overall financial health at a glance.
Looking for more investment ideas beyond ScanSource?
Once you have formed a view on ScanSource, it can help to cross check that thinking against opportunities in other corners of the market using the Simply Wall St Screener.
- For investors who care most about valuation support and business quality, scan through 31 high quality undervalued stocks that already combine solid fundamentals with pricing that may look appealing on a risk adjusted basis.
- If capital preservation and steadier profiles sit higher on your priority list, filter for 31 resilient stocks with low risk scores that align better with a more conservative approach to building a portfolio.
- When the focus is on balance sheet resilience and financial discipline, sort through the list of solid balance sheet and fundamentals (26 results) to find companies with stronger funding positions backing their operations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com