


Is RWE (XTRA:RWE) A Bargain After Its Strong Buy Upgrade?
RWE (XTRA:RWE) just picked up fresh attention after being added to a prominent Strong Buy list, following higher earnings estimates. This development puts a spotlight on the stock’s recent performance and risk profile.
Recent trading shows that upward momentum in RWE’s share price is still intact, with a year to date share price return of 25.99% feeding into a 1 year total shareholder return of 53.51% and a 5 year total shareholder return of 116.81% around the current €59.1 level. That performance sits alongside two recent green bond issues in late September 2031 and 2036 maturities and fresh Strong Buy attention. Together, these factors have sharpened the focus on both the company’s growth ambitions and how investors are reassessing its risk profile.
Spot 40 power grid technology and infrastructure stocks that, like RWE, are drawing fresh attention as investors focus on earnings revisions, capital investment, and the backbone infrastructure behind the energy transition.RWE has already made a sharp move higher and picked up fresh backing from analysts, so the real tension now is whether you commit at today’s price or wait for a cleaner entry before the valuation work.
Most Popular Narrative: 13% Undervalued
On the most followed narrative, RWE’s fair value of €67.58 sits above the current €59.1 share price. This raises the question of whether today’s entry already reflects its vertically integrated power ambitions and renewables build out.
RWE's multi-gigawatt pipeline of diversified wind, solar, and battery projects under construction (11 GW with over 3 GW ready for commercial operation in the near term) is set to support double-digit annual renewables capacity growth, boosting recurring revenues and EBITDA.
See why 69 investors see RWE as 13% undervalued.
Result: Fair Value of €67.58 (UNDERVALUED)
Still, the RWE narrative can be knocked off course if weak wind conditions keep squeezing generation volumes, or if supply chain delays push project costs and timelines off track.
Find out about the key risks to this RWE narrative.
Another View On RWE’s Valuation
RWE looks undervalued on the analysts’ fair value of €67.58, yet the SWS DCF model paints a different picture. On that cash flow lens, the current €59.1 price sits well above an estimated future cash flow value of €31.82, which screens as expensive rather than cheap.
The gap between those two anchors leaves you with a real question: Do you lean on long term earnings narratives and multiples, or treat the DCF signal as a warning that expectations may already be running ahead of hard cash generation potential?
Look into how the SWS DCF model arrives at its fair value.
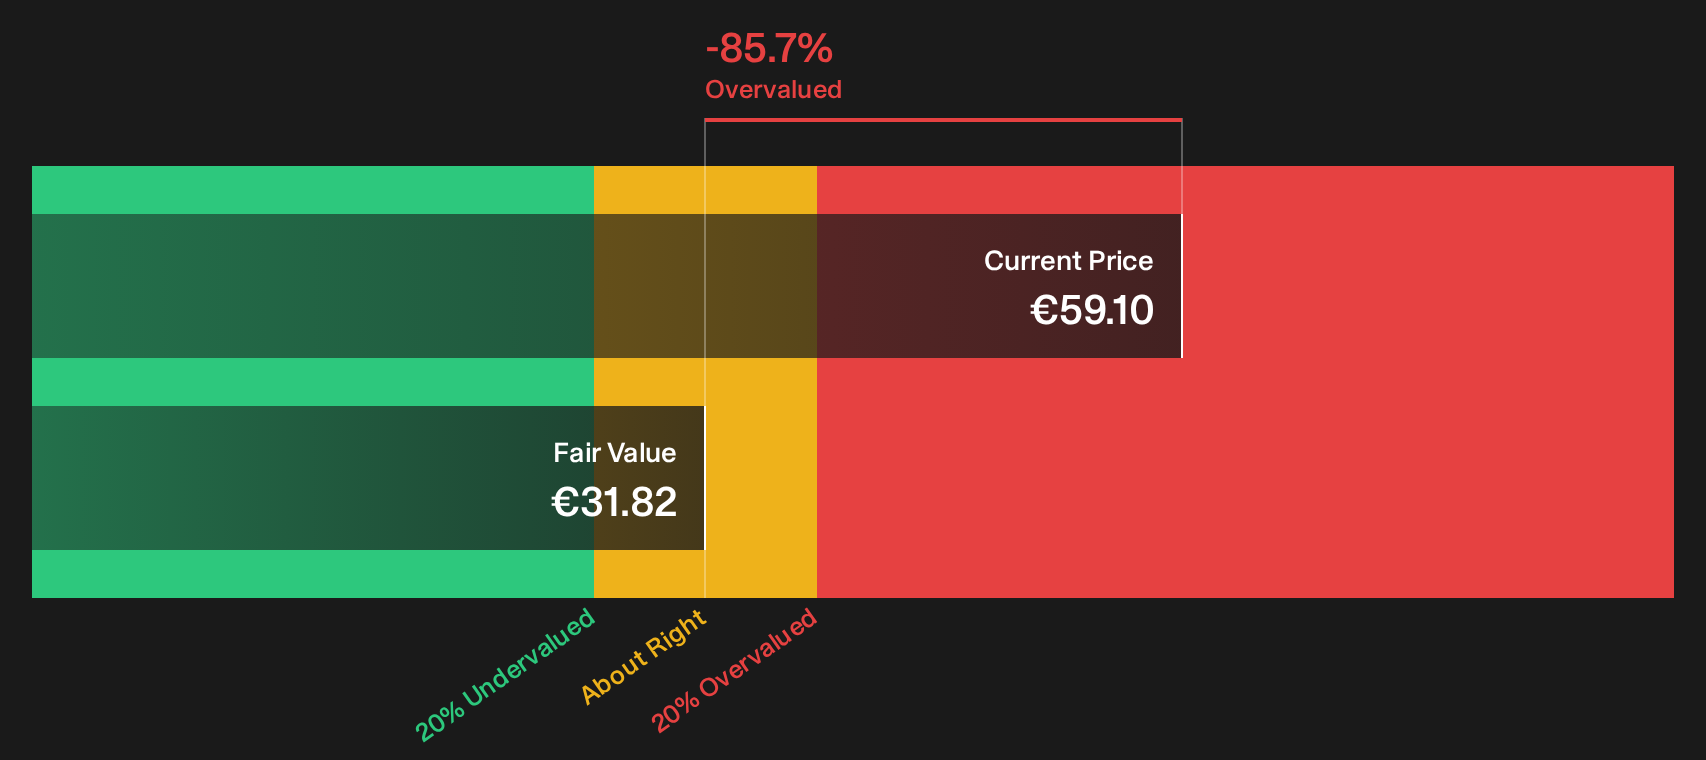
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out RWE for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around RWE is clearly split. This is exactly why you should move quickly, test the numbers yourself, and decide where you stand. To see both the key concerns and the potential upsides in one place, review the 4 key rewards and 1 important warning sign.
Looking for more RWE-style investment ideas?
If you only stop at RWE, you risk missing other opportunities that fit your approach, so put the Simply Wall St Screener to work for you now.
- Tap into resilient businesses by scanning a list of solid balance sheet and fundamentals (208 results) that can better handle shocks and still keep their financial footing.
- Hunt for mispriced opportunities using a 196 high quality undervalued stocks that combines quality metrics with lower valuations so you can focus attention where expectations may be softer.
- Build a steadier income stream by shortlisting 170 dividend fortresses that aim to pair higher yields with more durable payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com