


How Record Dividend At Amerigo Resources (TSX:ARG) Has Changed Its Investment Story
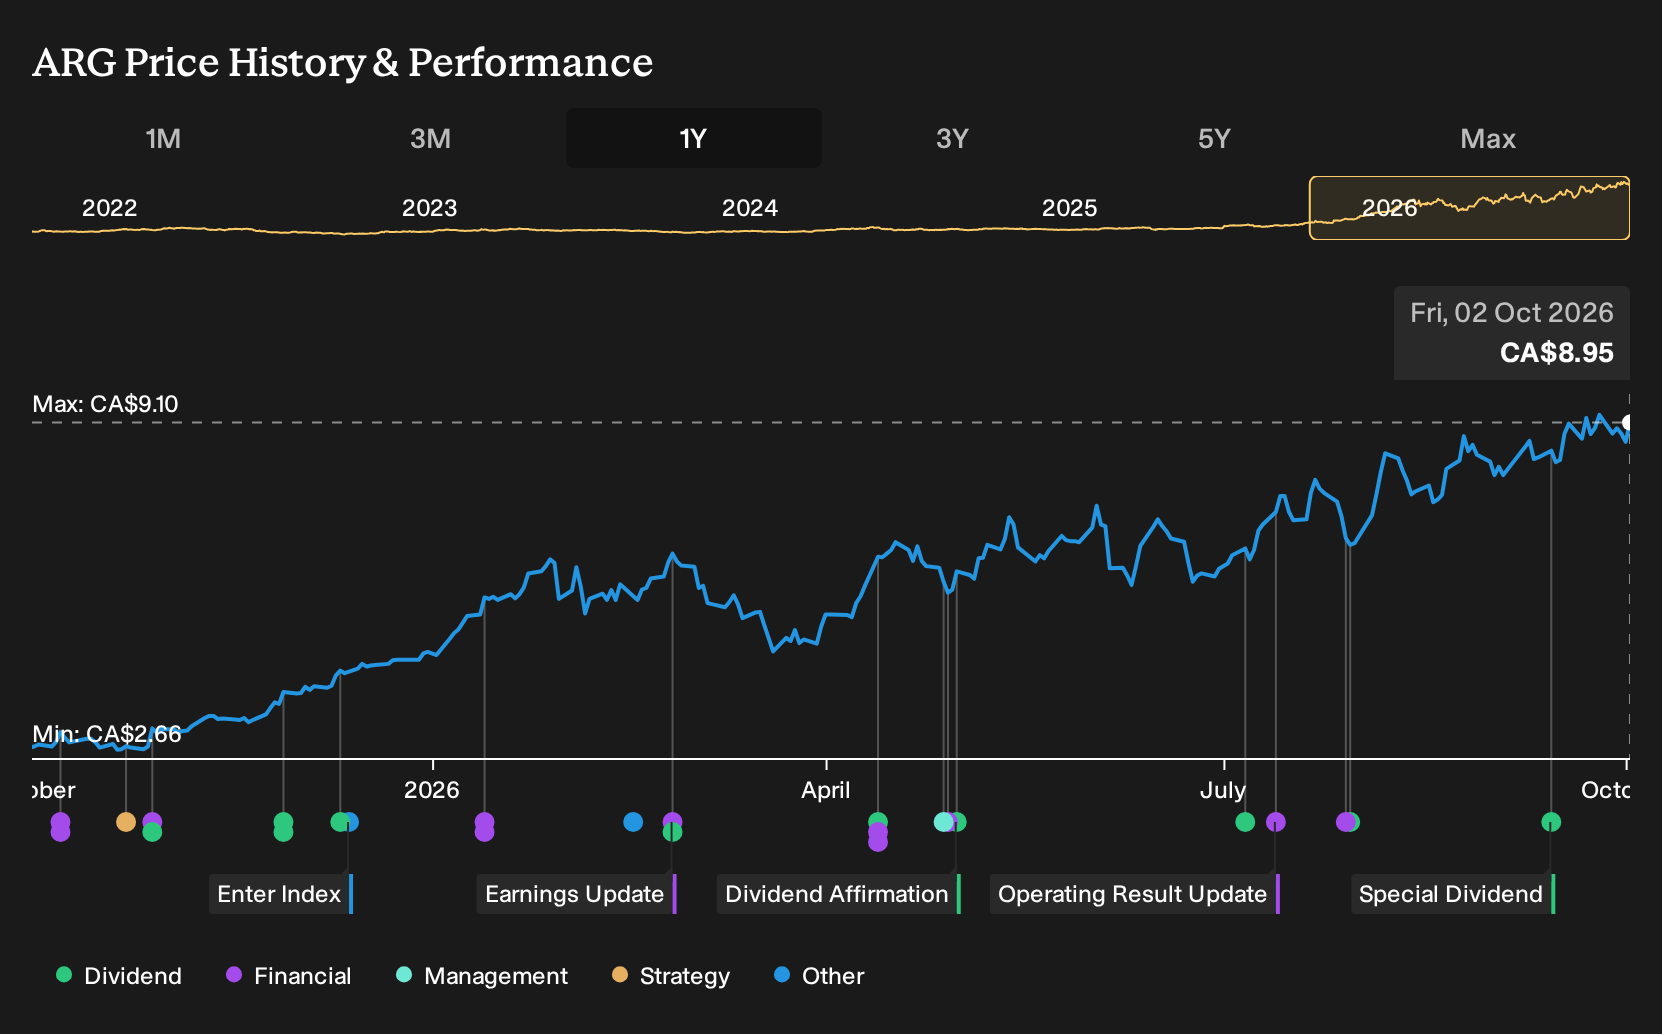
- Amerigo Resources recently declared a record CAD 0.18 per share performance dividend for July 2026, in addition to its ongoing CAD 0.04 quarterly dividend, supported by strong free cash flow, a debt free balance sheet, and cash reserves of US$50.3 million.
- The variable performance dividend structure at Amerigo Resources ties extra shareholder payouts to copper prices and surplus cash, which puts the focus on how effectively its Minera Valle Central operation in Chile converts market conditions into discretionary distributions.
- Attention now shifts to how Amerigo Resources' record performance dividend could reshape the investment narrative and highlight its free cash flow profile.
Scan how Amerigo Resources' dividend story compares with other income focused opportunities by checking our curated list of 1 dividend fortresses in the market today.
What Is Amerigo Resources' Investment Narrative?
For Amerigo Resources, the core belief is simple. You need to think its Chile focused tolling model can keep turning copper market conditions into solid free cash flow, even as revenue is forecast to decline by 16.4% per year over the next three years. The July 2026 record performance dividend leans into that story. It signals management confidence in current cash generation, backed by high quality earnings, a 20.9% net margin and an outstanding 50.7% return on equity.
Short term, the extra payout sharpens attention on how reliably Minera Valle Central can run, how sensitive earnings remain to copper prices, and how repeatable this dividend pattern really is given an unstable track record and significant recent insider selling. With the share price up 99.8% year to date and trading at a P/E of 17.6x, you are tying your thesis tightly to execution and pricing power rather than cheapness.
That said, there is one uncomfortable angle in the Amerigo Resources story that still hangs over the dividend narrative...
There's only one way to know the right time to buy, sell or hold Amerigo Resources. Head to Simply Wall St's company report for the latest analysis of Amerigo Resources's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$3.99 to US$10.02 per share, so retail views on Amerigo Resources already sit far apart. Those opinions do not yet factor in the July 2026 performance dividend; this could prompt fresh debate on how durable the current cash profile really is.
Explore another Amerigo Resources fair value estimate, including one that suggests as much as 55% downside from the current price!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amerigo Resources research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amerigo Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amerigo Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Amerigo Resources?
If the Amerigo Resources dividend story has sharpened your focus on income, value and balance sheet strength, it can help to line it up against a broader watchlist of opportunities that fit your approach.
- For investors who prioritize resilient businesses over drama, start with a 8 resilient stocks with low risk scores that aims to keep surprises to a minimum.
- If quality at a reasonable entry point is your priority, scan a 6 high quality undervalued stocks that currently meet strict fundamentals and valuation filters.
- Income focused investors can widen their search by reviewing a 1 dividend fortresses that offer elevated yields backed by fundamental checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com