


Encore Capital Group (ECPG) Stock May Look Reasonable As Earnings Stay Central
Encore Capital Group has delivered a powerful share price run over the past year, which naturally puts a spotlight on whether the current valuation lines up with what its earnings can support. With the stock now trading at US$95.92, the question is how much of that move reflects the underlying profit engine of the debt purchasing and recovery business versus shifting market expectations.
- The share price has climbed 132.2% over the past year, which raises a clear question about how far recent gains are grounded in Encore Capital Group's earnings profile.
- The group relies on converting purchased debt portfolios into cash over long collection cycles. As a result, the quality, timing and consistency of its earnings may be central to how sustainable today's valuation is.
- The analysts covering Encore Capital Group have run their own numbers. See what analysts think Encore Capital Group's shares could be worth.
For investors, the debate is whether Encore Capital Group's current share price is adequately explained by the level and reliability of its earnings today.
If you are weighing whether Encore Capital Group's P/E and earnings story justifies this share price, it can help to compare that question against 31 high quality undervalued stocks.
Does Encore Capital Group Look Undervalued on Earnings?
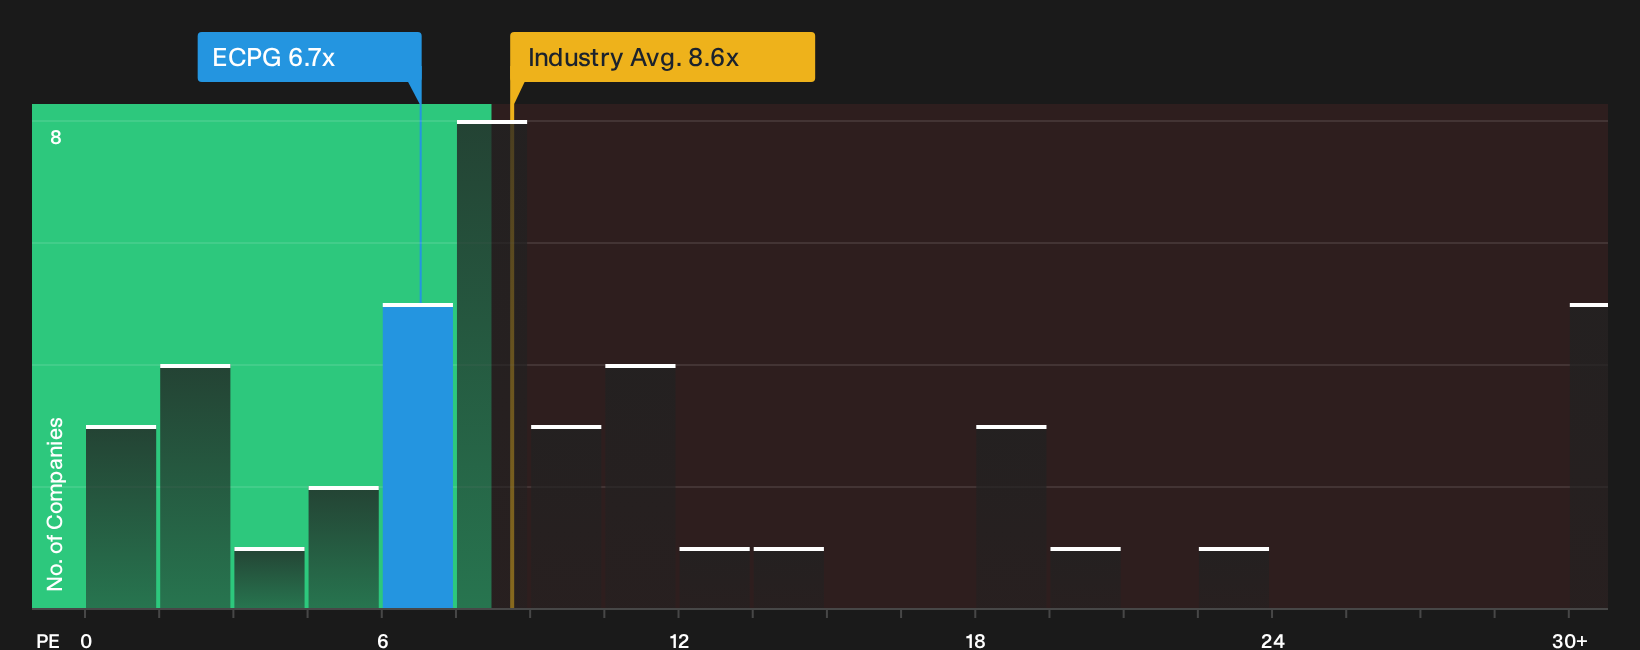
The P/E ratio fits Encore Capital Group reasonably well because earnings sit at the center of how markets judge a debt buyer and collector. At a P/E of 6.7x, the stock trades at a sizeable discount to the Consumer Finance industry average of about 8.6x, and at an even wider gap to the broader peer group on roughly 16.8x. That indicates the market is paying less for each dollar of Encore Capital Group earnings than for many comparable lenders and specialty finance businesses.
The Fair Ratio, which estimates the multiple you might expect once Encore Capital Group's growth profile, profit quality, size and risk are blended together, sits above the current 6.7x level. On this framework the shares appear undervalued relative to what those fundamentals would typically justify, although the appeal of that discount still depends on how comfortable you are with the debt purchase model and the stability of future collections. Explore the numbers behind Encore Capital Group's P/E valuation.
The Encore Capital Group Narrative: What Would Justify Today's Price?
Encore Capital Group's Simply Wall St Narratives pick up where the valuation puzzle leaves off and spell out which expectations for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today on the market. Each storyline links its numbers to a clear view of how Encore Capital Group's future performance and risks might evolve. You can revisit these views as fresh information comes through on the Community page.
One of the top community narratives on Encore Capital Group: 20% undervalued
"One of the strengths of ECPG’s business is the transparency of its cash generation, which should give investors greater confidence..."
Discover why this Narrative puts Encore Capital Group at 20% undervalued.
The share price is only one piece of the Encore Capital Group puzzle
Encore Capital Group's current valuation tells only part of the story, because analyst expectations over the next few years offer a separate lens on where earnings and risk could go from here. Explore where analysts expect Encore Capital Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com